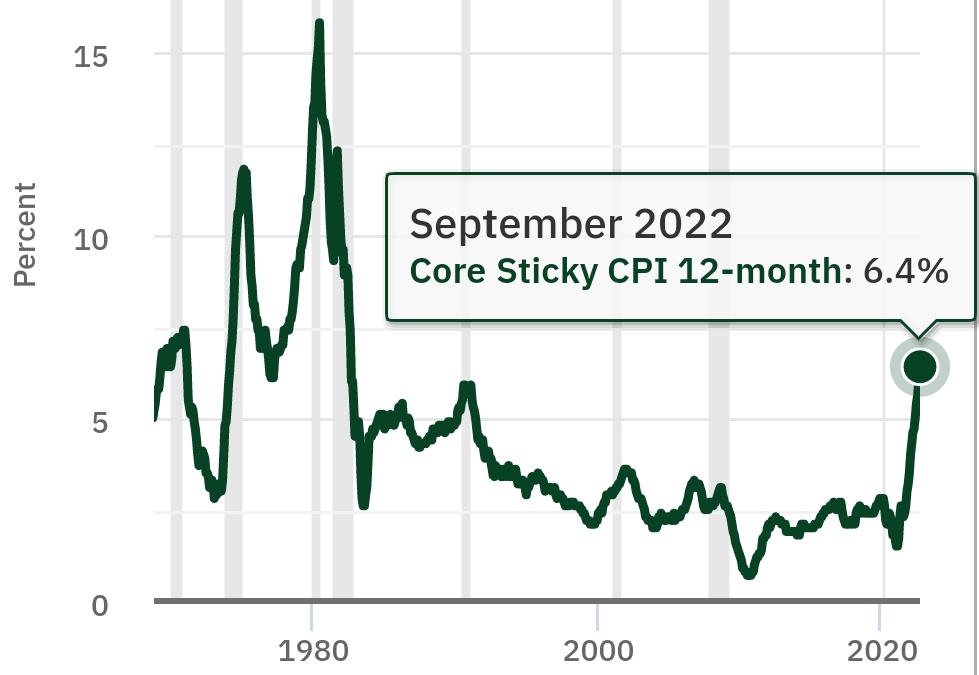
Inflation:
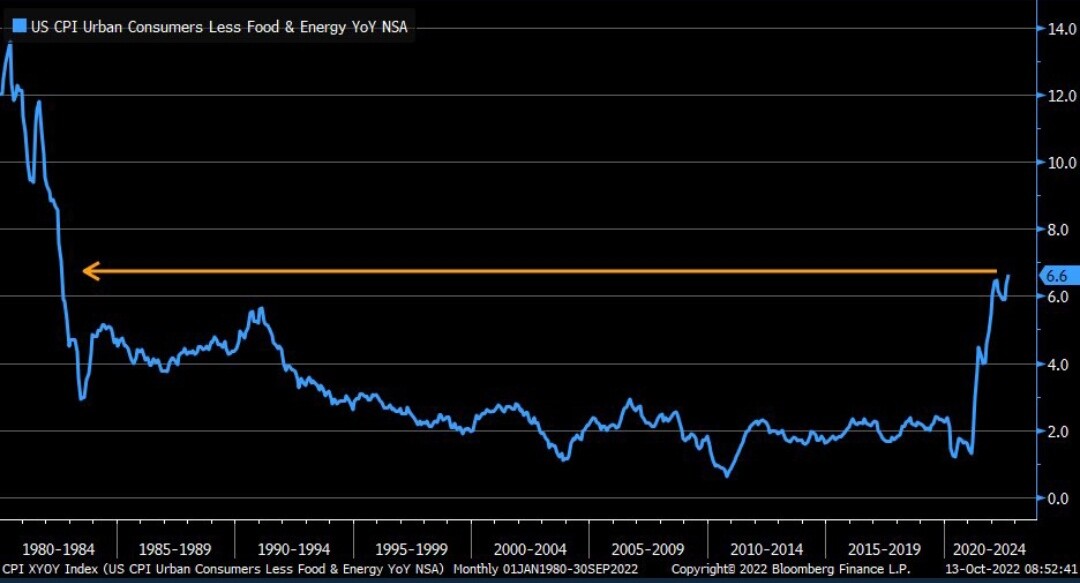
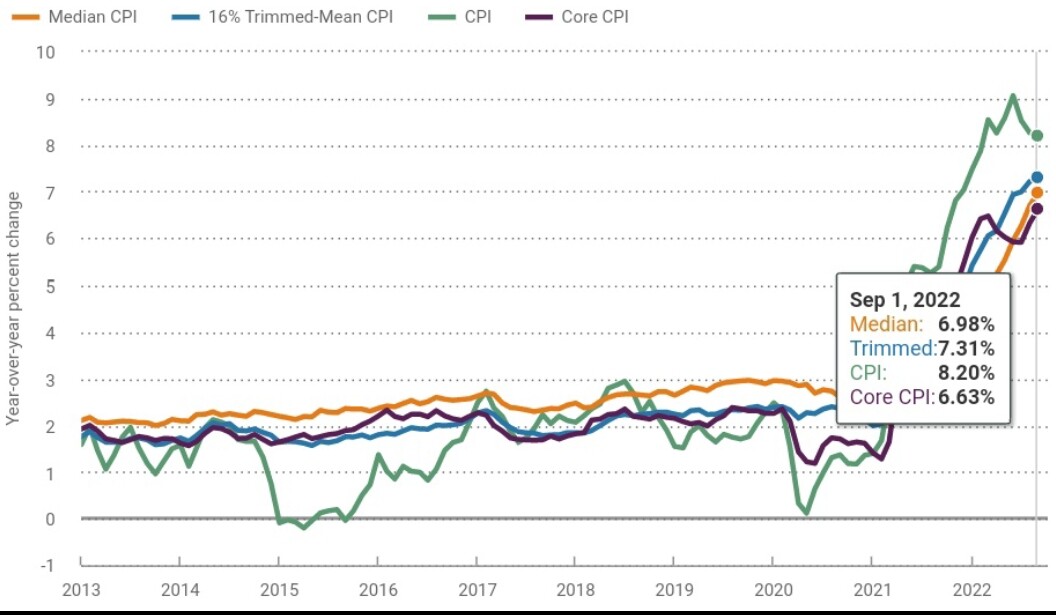
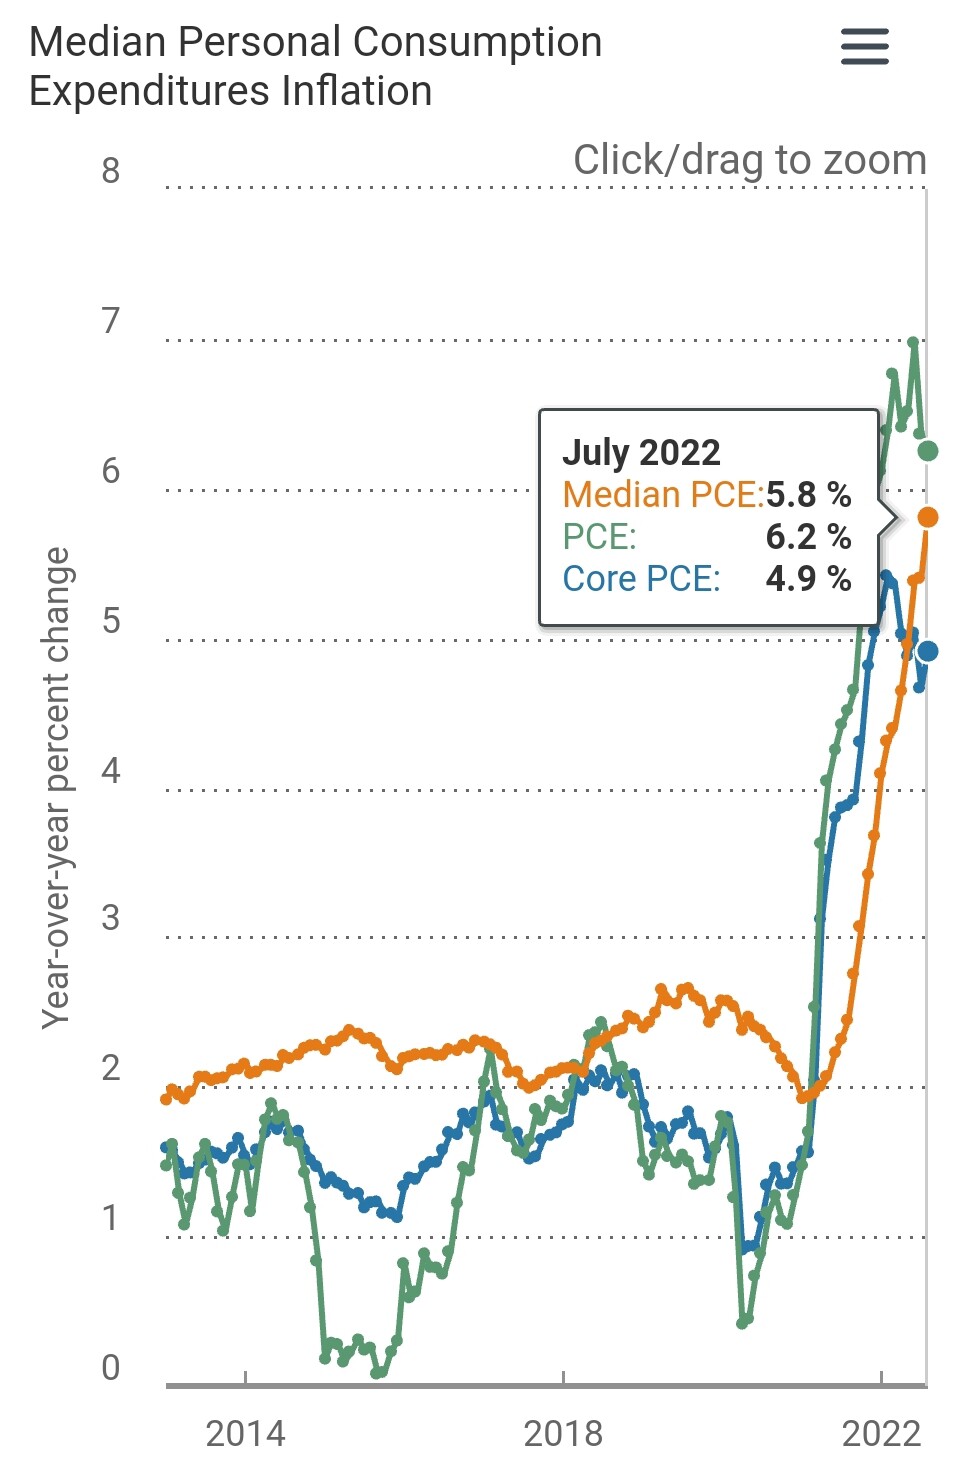
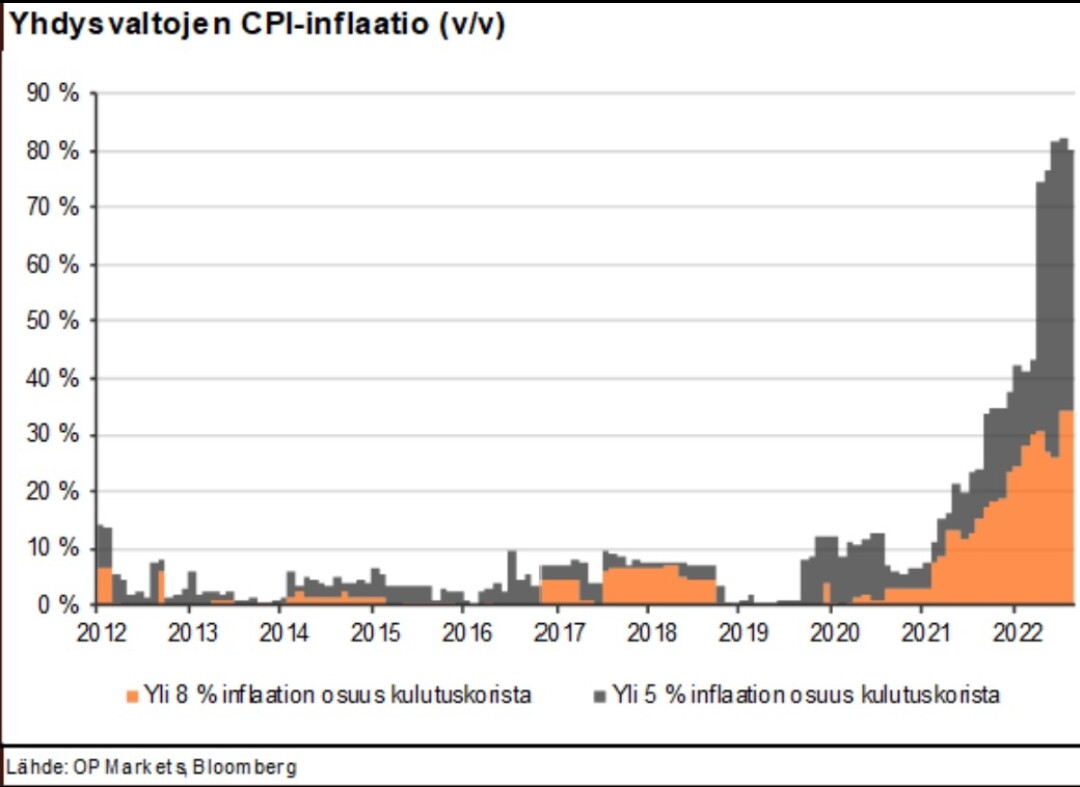
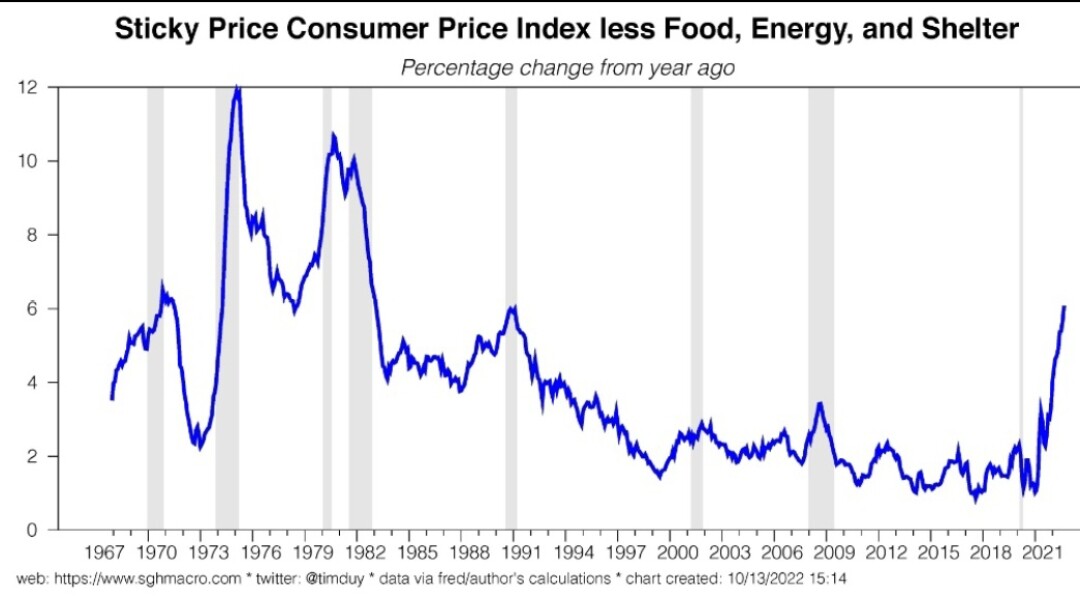
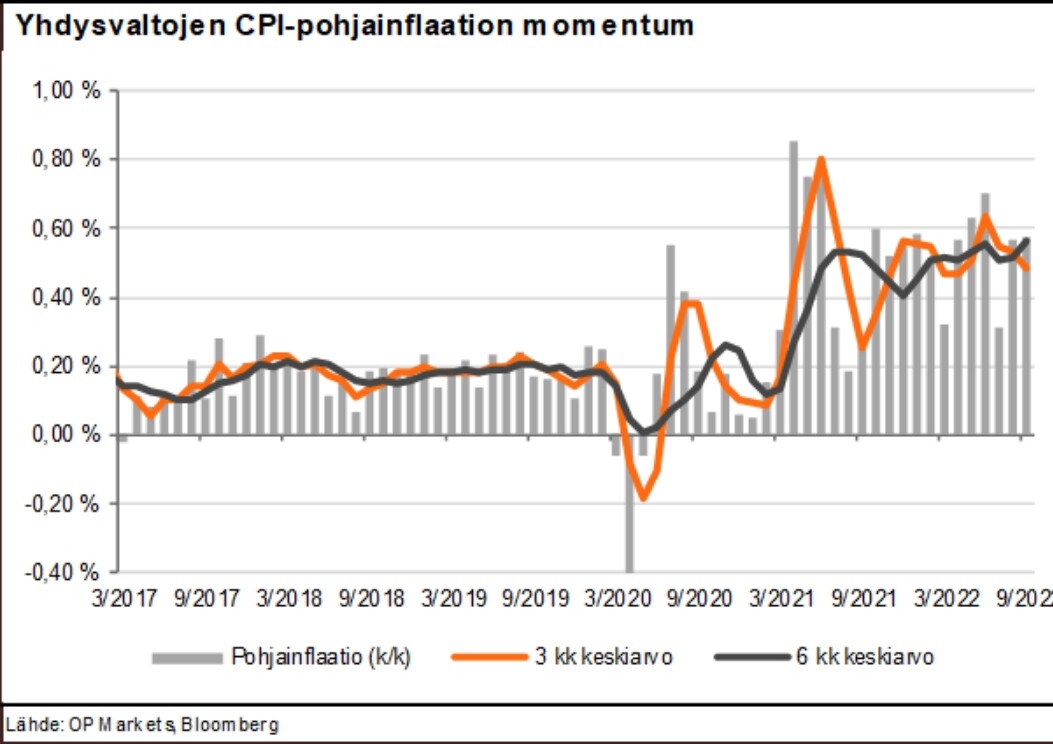
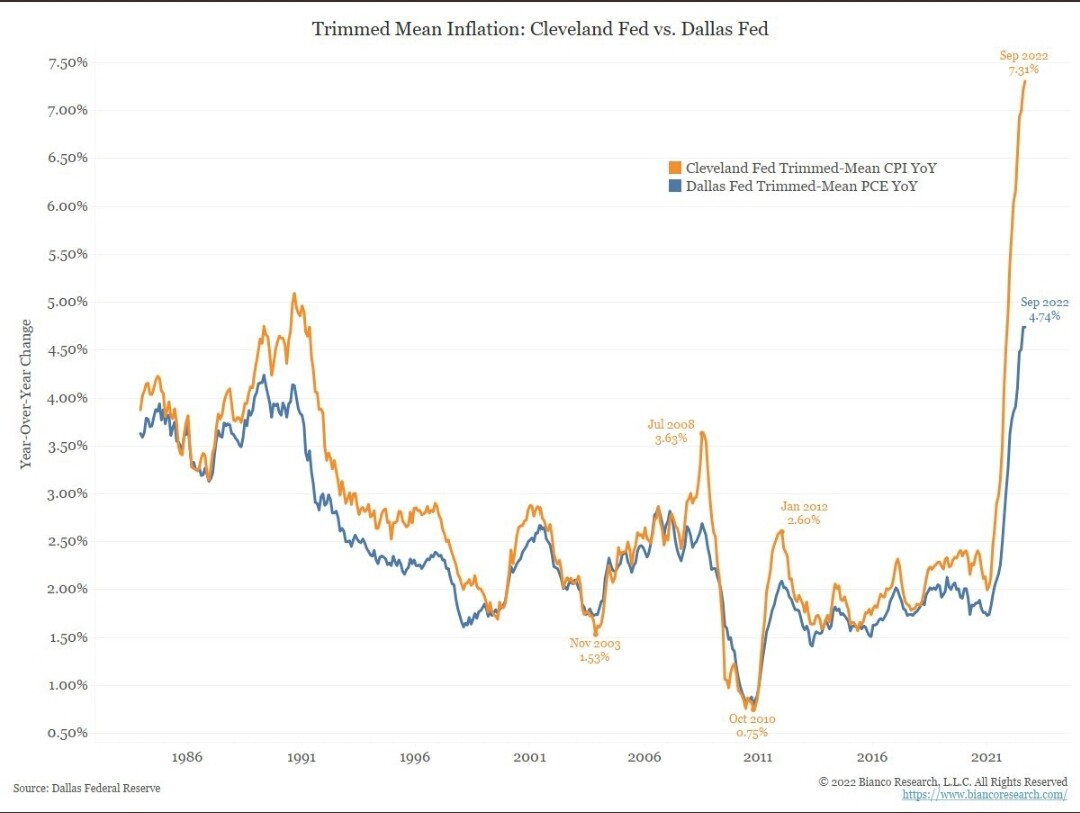
- headline
- core
- underlying
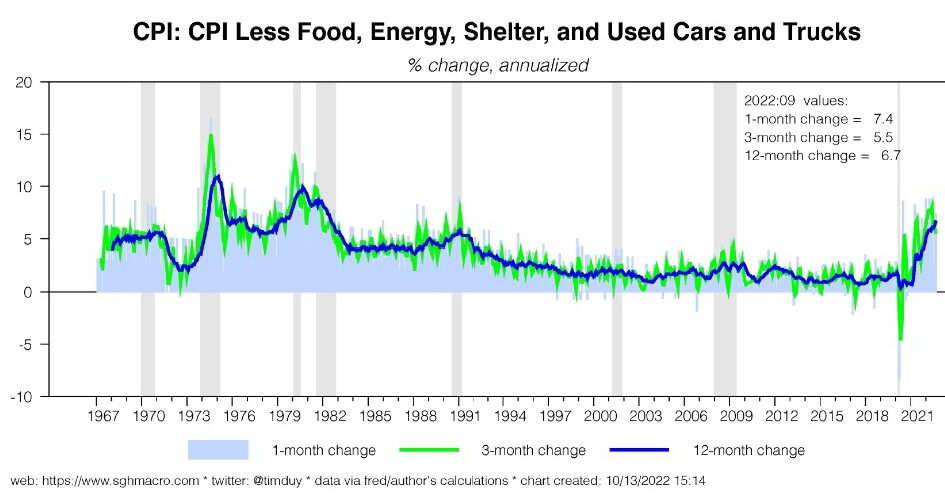
Headline inflation sometimes has a lot of noise. Core inflation can also have noise – e.g., used cars last year.
Underlying inflation is a subjective estimate of what would be revealed if all the noise and transient issues, e.g., those related to suboptimal methodology, were removed. For example, in the US, housing-related inflation shows up in the numbers with a delay.
At some point last year in the US, an optimist could reasonably argue that underlying inflation was 2%. Then the optimist’s estimate was 3%. Then 4%.
What is the optimist’s estimate now? Just under 5%?
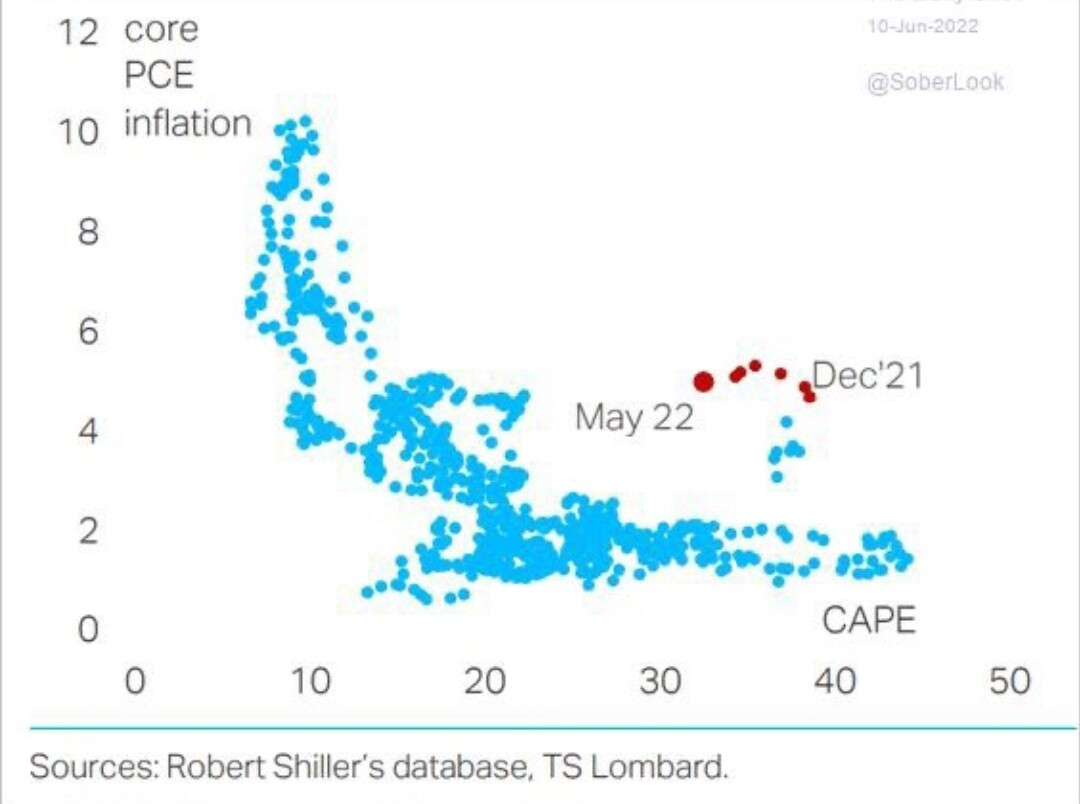
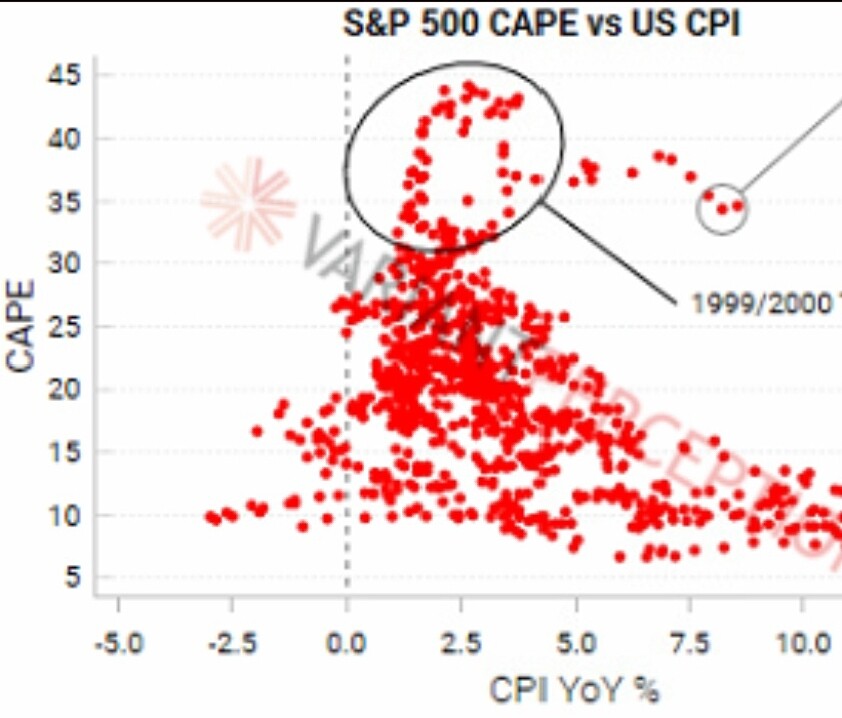
The stock market doesn’t tend to drop like a stone. The S&P 500 has fallen exceptionally sharply this year, but it has also included many bursts of optimism.
The Nikkei was not a buying opportunity in 1990, even after the index had fallen 25% and the P/E went from 60x to 45x.
Each case should be evaluated separately to determine how much each decline helps to normalize valuation levels.
I see no fear at all in the S&P 500, but rather a very calm repricing.
Will fear enter the picture at some point? Time will tell.