TransferWise, a name perhaps familiar to many Finns, which changed its name to Wise earlier this year, is expected to list on the London Stock Exchange in the coming days.
The company was founded in 2011 by two Estonians, originally a fintech focusing solely on cheap money transfers, before fintech was cool (or even a commonly used term). It has grown rapidly and now offers many other services, such as international bank accounts, credit cards, international accounts for businesses, invoicing, etc.
I’ve been their customer for a long time. Today, I received a message where they are offering a bonus program to old customers, giving 5% in bonus shares if you hold shares purchased at the time of the listing for 12 months. This reminded me of Sonera, which did exactly the same thing in -98.
Are there others here considering participating?
Now that I live in Finland, can I buy these London Stock Exchange listings from Nordnet right on the first few days? Based on Wise’s instructions, they must be purchased within a week if one wants to take advantage of the bonus.
In Nordnet, you cannot buy stocks that are solely listed on the London Stock Exchange. Here, Nordea, Mandatum, and OP offer trading in London. Perhaps Danske also does, but I’m not sure about that.
7.7.2021 listed directly on the London Stock Exchange, bypassing an IPO. You can’t buy it from Nordnet because it doesn’t belong to a certain index. (Otherwise, London through a phone order only.)
In the 2020 funding round, valuation was $5 billion. At the beginning of trading, it was $11 billion.
There are 2 different classes of shares. One has more votes.
My own experience with the company is very positive. Money exchanges made in EUR, AUD, USD, SEK. The system works at a commendable level. Customer service is excellent, and compared to banks, the fees are remarkably low. International free debit card. Also for businesses. The view is that they would not have wanted to go public yet, but cryptocurrencies forced them to take things to the next level. This is worth keeping an eye on.
When enough people call Nordnet, we’ll probably get it from there too. Otherwise, it’s possible through Interactive Brokers or Degiro, for example.
“We’re building the best way to move and manage money around the world.”
" Wise is now a public company.
Wise became a public company through a direct listing in London on 7 July 2021. In contrast to a traditional IPO, a direct listing was the fairer, cheaper and more transparent way for us to broaden our ownership.
Our stock ticker is WISE . You will sometimes see this written as LSE:WISE or LON:WISE
I stumbled upon this service a few years ago while on assignment abroad and used it quite a lot. Initially, I was a bit skeptical about transferring money with a phone app that wasn’t backed by any traditional “big bank.” My doubts quickly disappeared, and I must say it has been an incredibly good service.
I’d be interested in joining in, as the company’s product seems excellent (though I haven’t tried others), and I have some faith in South Helsinki startups. As a long-time customer, I also received that bonus program, where if you hold shares for at least 12 months, you get a few more. However, I haven’t yet had time to delve into the company’s financials, and I need to do that this week before making an investment decision. Initially, I’m a bit concerned that the valuation might be quite tight.
On July 7th, I also received a message that I was admitted to the OwnWise program, and that I have to wait for a new message because my 7-day “purchase window” begins, if I want those 5% extra shares. Do they regulate these time windows so that there aren’t big buying and selling spikes at the beginning? I’m a bit puzzled by this approach. In any case, I opened an IB account today and we’ll see if I can pick up a few shares from there. The company is very attractive and I have strong faith in its future. The valuation is also in line with that…
Wise will be the Amazon of money transfers. Its customers are practically the entire world and 8 billion people. Marketing is easy when word spreads. If you look at any travel group, Wise is recommended there.
The only significant competitor is Revolut. Revolut’s other co-founder is Russian, which is certainly a PR blow for the company. Western Union’s revenue has been on a decline for the last 5 years.
In my opinion, it’s hard to see a worst-case scenario. The best-case scenario would be, for example, a massive acquisition where Wise is sold at a large premium based on future prospects.
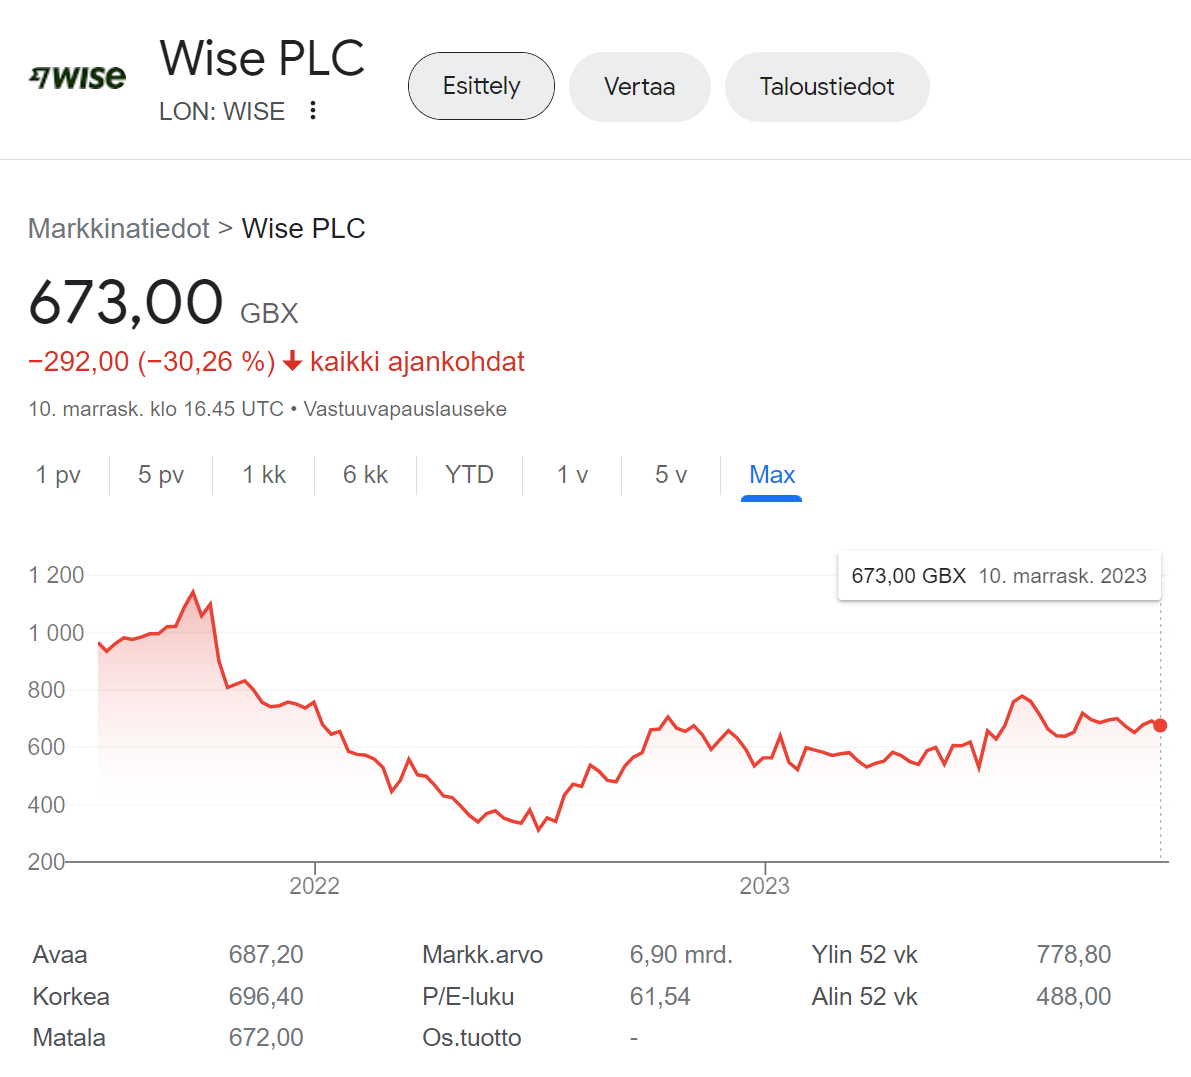
The share price has come down since the IPO. The valuation is high (60 P/E), but I’m sure it’ll work out!
We’ll get more information soon:
One observation is also that travel opened up in the autumn of 2022. Since then, there has been a growing need for currency transfers again.
The average traveler gets their cash from an exchange booth. Wise specifically serves digital nomads who run online businesses.
It’s strange that the share price hasn’t reacted more. If you’re looking for a growth company, here’s one!
It came crashing down from the IPO. Makes you wonder if the company was overvalued back then. When it listed in July 2021, interest rate hikes weren’t even on the table.
Wise is indeed an exceptionally high-quality company! I’ve been a customer since 2015 and a shareholder for a bit over a year now. The products, management, and culture are in good shape.
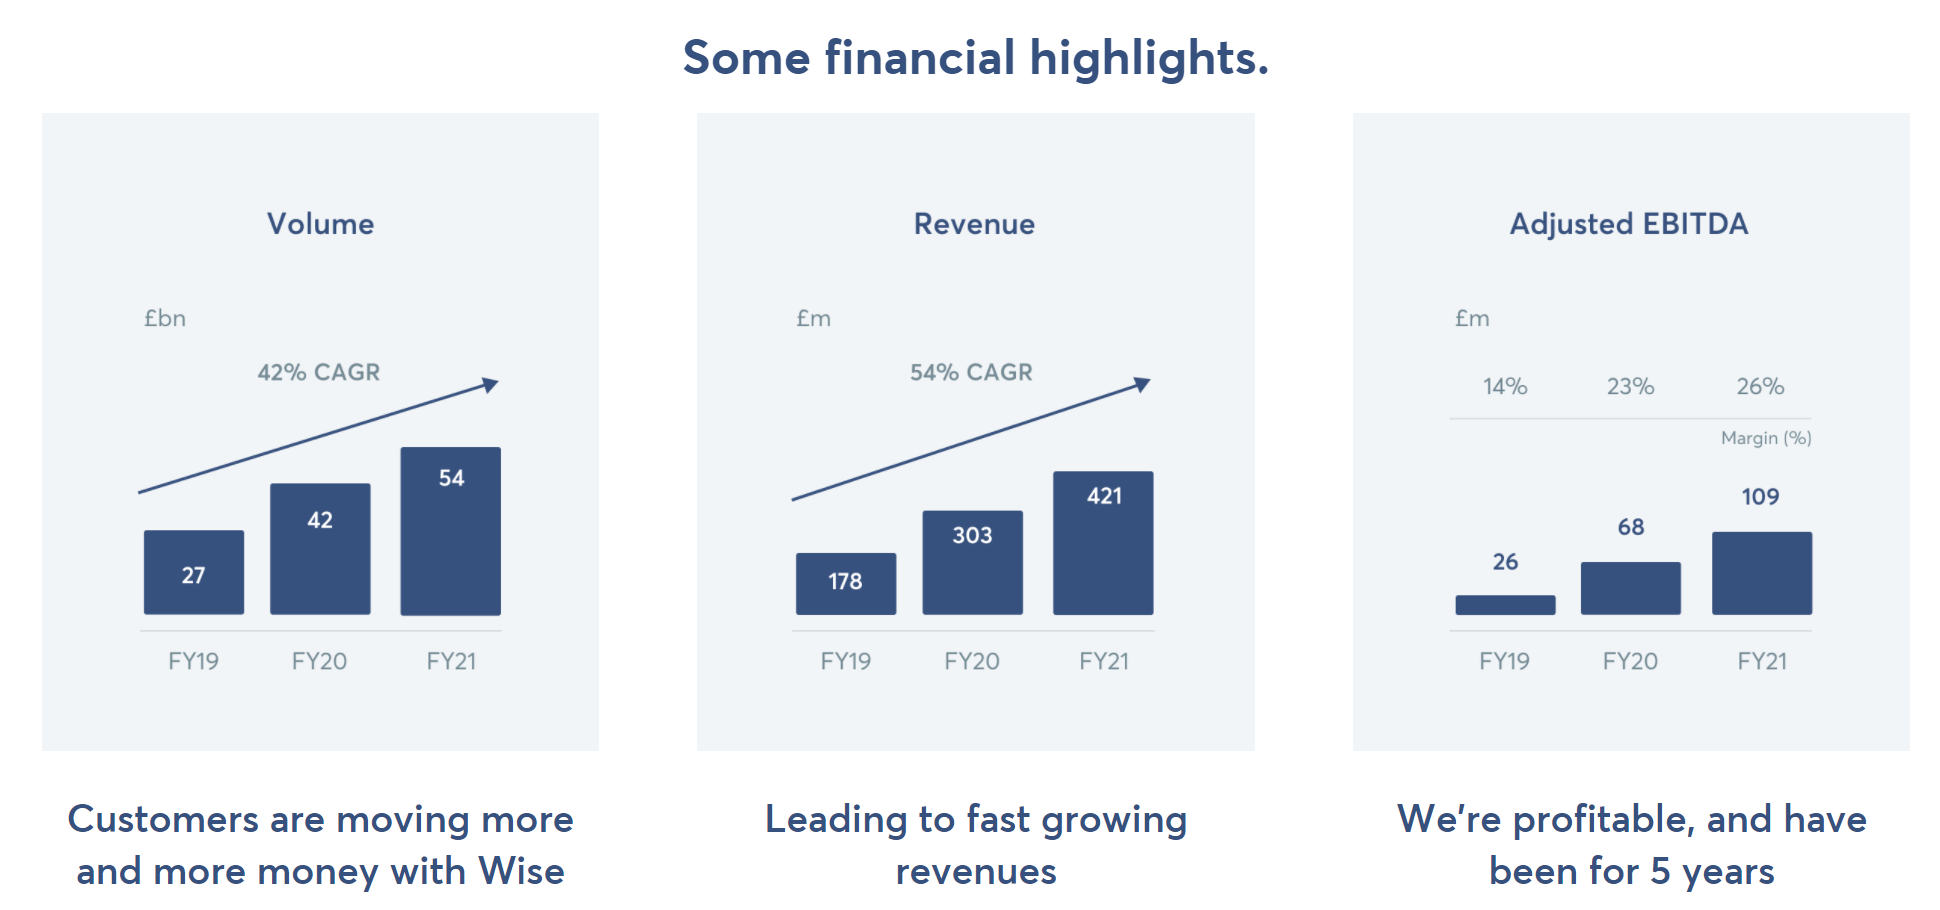
Right now, net interest income is boosting the result, but even with the long-term target (25% Adj. EBITDA margin), the current financial year would leave about £200m in net profit if calculated using current ratios. That’s quite a strong proposition for a £7.4bn company whose revenue grew 25% YoY and has a three-year CAGR of 37%.
I’ve opened an account with Lightyear, a stockbroker founded by former Wise employees, where I continue to accumulate Wise monthly with £1 fees
I should open that Lightyear account. With it, I could do some small-scale trading in Helsinki and also make US/LON purchases. I’ll be switching to Nordnet soon because of the leverage. @Mahis
They are available at Nordea and Mandatum.
Wise’s competitor Revolut is popular, but things are not going well within the company.
They still don’t have a license for the UK banking sector.
“Under a separate license issued by the Bank of Lithuania, Revolut is able to operate as a bank within the EU and currently provides banking services in 28 EU countries. But the UK is by far its largest market—and a UK banking license, seen as a gold standard worldwide, would open doors to new territories, like Australia and the US. It’s a crucial piece of the puzzle, but one that might depend on Revolut’s ability to better project the sense that its house is in order.”
I’ve been going through Wise’s reports. The company invests about 30% of customer deposits and earns a 4% return on these. For the remaining customer deposits, the yield is around 1% or less.
For example, Nordnet invests 64% of deposits, so that’s a small figure and you’d hope to see it grow.
Annual report and investor event from Wise today.
The share price took a sharp dip of over -20% and was -11.50% by the end of the day.
The reason for this was that Wise is lowering its service margin on currency transfers by 2 basis points.
The company calls this an investment. It is an aggressive growth strategy, but not investor-friendly. Wise will likely be able to gain market share from main competitors with this. Furthermore, there are moats in the industry, and new players do not enter easily.
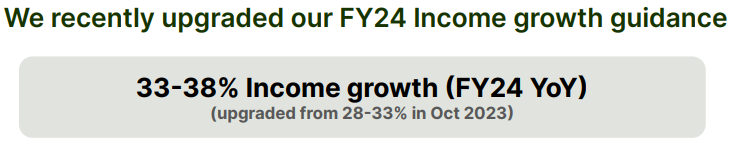
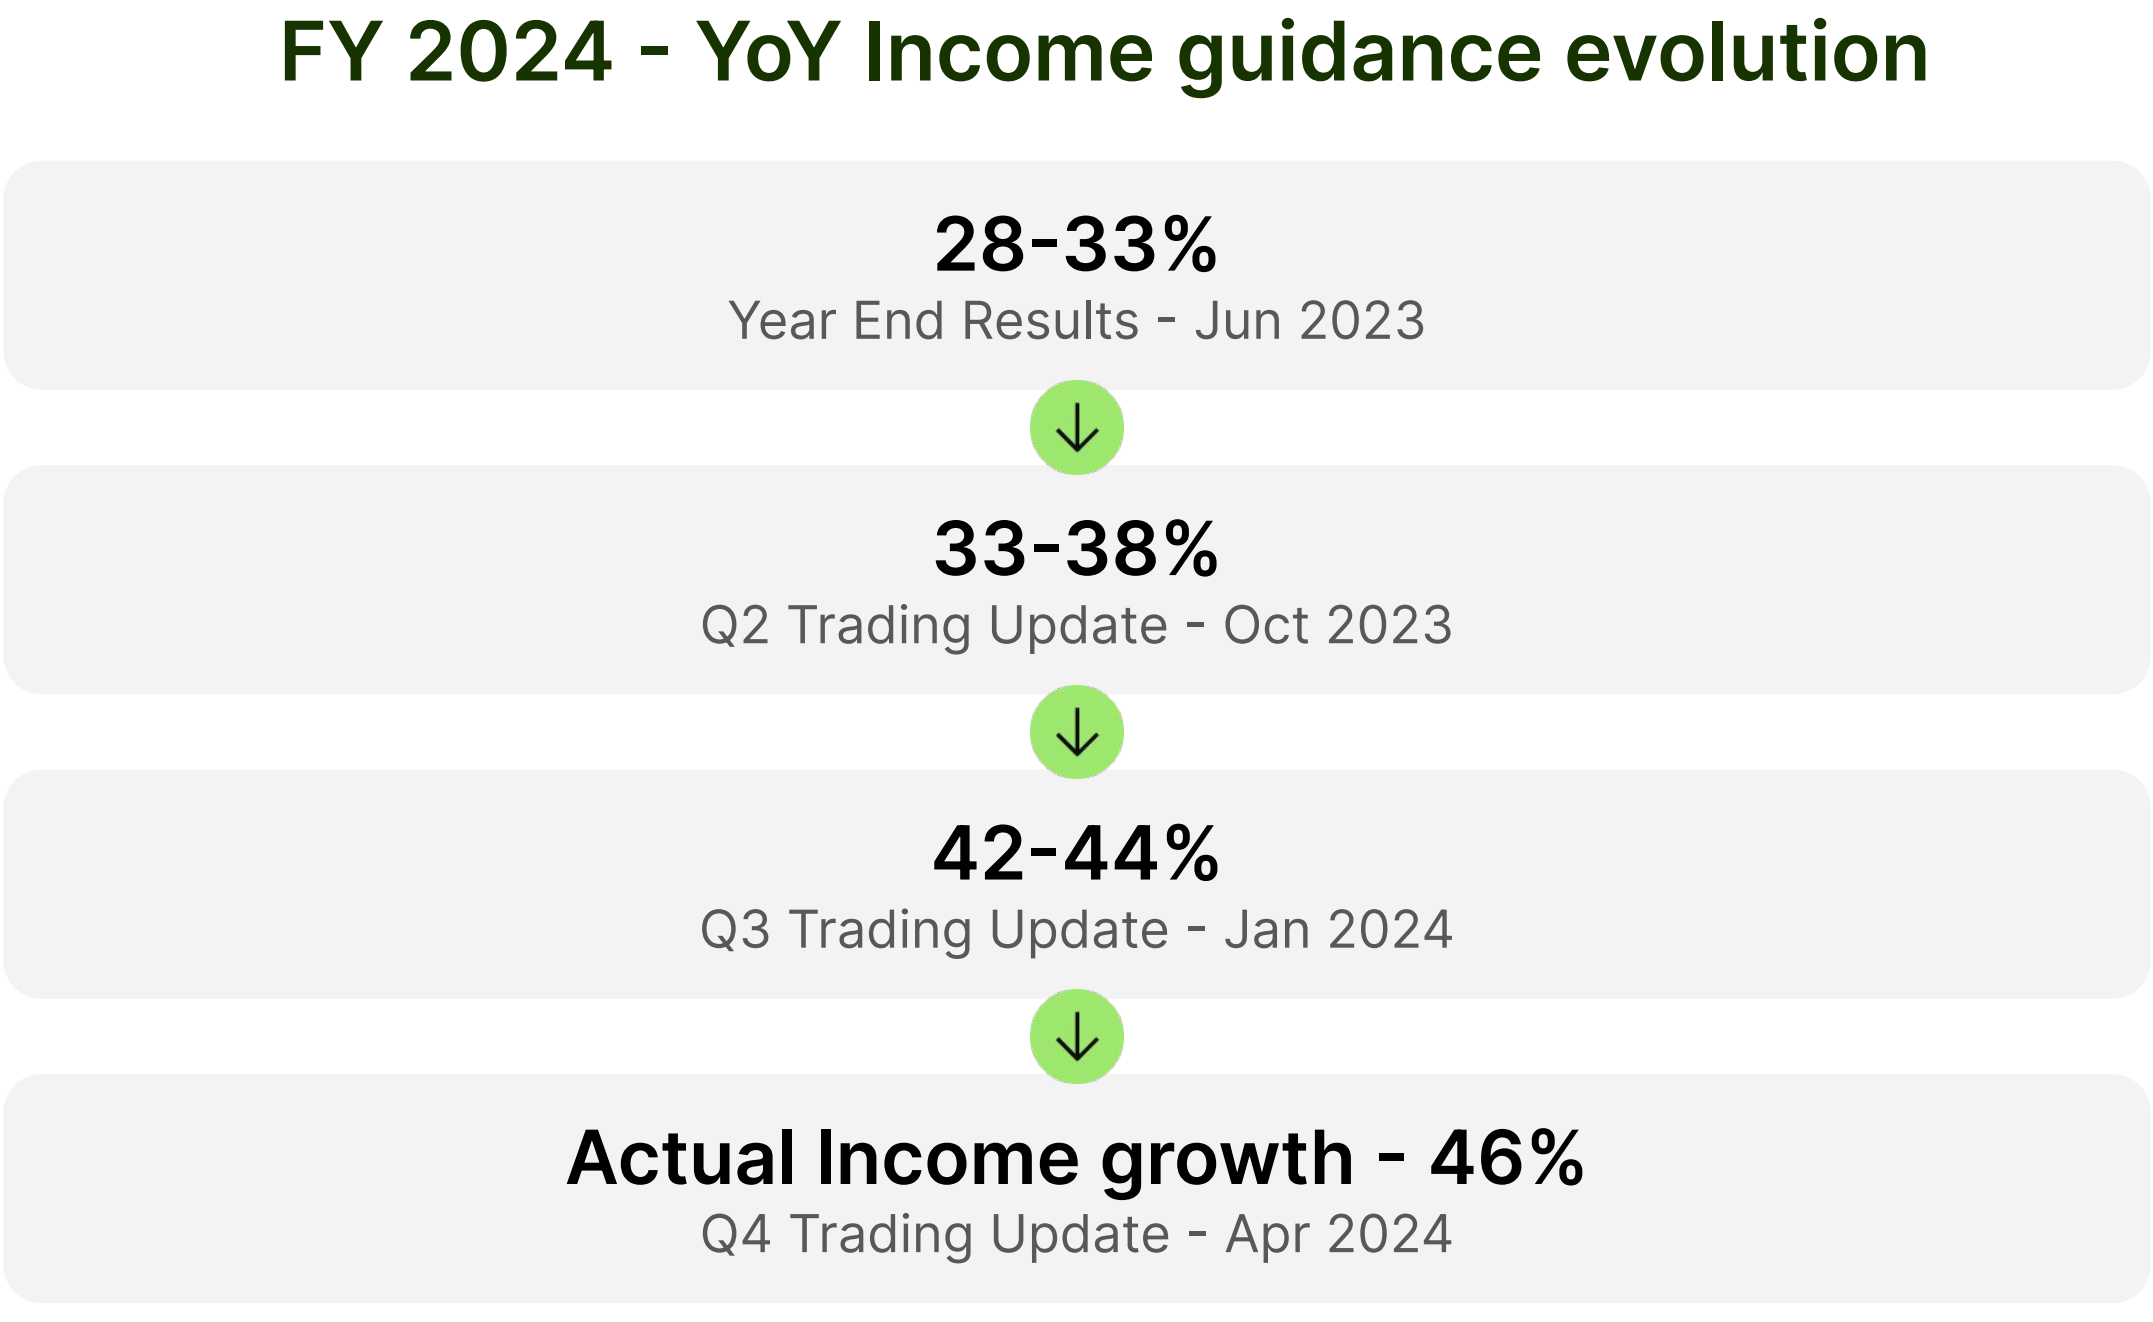
As a reminder, Wise raised its annual outlook twice last year and still exceeded them, so I’m definitely not turning bearish because of this decision.
I personally remain bullish based on this presentation. Now, those who were short were just weeded out.
Are there any fellow Wise investors here?
In the newly released half-year report, they touted a good and “fat” result. Following that, it was stated that the profit margin will indeed decrease from this level. This raises questions for me and surely for institutional investors as well. Wise could have, therefore, continued to accumulate this fat profit. It remains to be seen whether that lower fee percentage will get more money moving and attract larger numbers of customers.
“In the first half of FY25 we generated an underlying profit before tax of £147.1m, a 57% increase over last year with an underlying profit before tax margin that remained elevated at 22%.”
“We expect the investments in pricing in the first half of FY25 to move us closer to achieving our target underlying profit before tax margin range of 13-16% in H2 FY25, from an elevated position of 22% in the first half”
There are surely people who use Wise no matter what and won’t switch providers for the sake of a small saving in fees. In such a situation, the company’s board could exercise its power if the situation does not please shareholders. After all, the task of a listed company is to maximize profits for its shareholders.
Wise has a very peculiar calendar, but the Q3/FY25 update looked excellent.
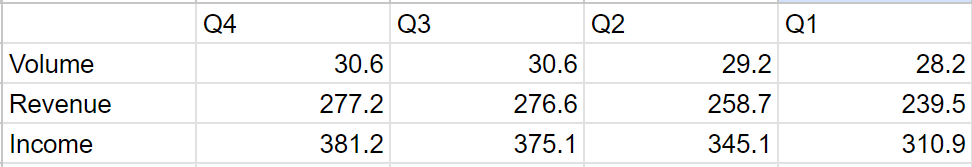
Volumes saw solid growth. Last year had a few slower growth quarters. Interest income is also at a good level. Investors feared it would drop suddenly due to interest rate cuts.
The Morgan Stanley collaboration doesn’t seem to be visible here yet.
 You can’t buy it from Nordnet because it doesn’t belong to a certain index. (Otherwise, London through a phone order only.)