Today was certainly a pleasure to be on board with Talenom. The company is making insanely good results through automation and is heading abroad to build international business. The CEO is also funny and convincing. Should I buy more? It feels bad to raise my average price, having bought the stock at 8.5 euros..
9 Likes
Talenom is one of the few true growth companies on the stock exchange with strong competitive advantages (a digitalizer/disruptor in its own industry). Its internationalization is still in its early stages, so one probably shouldn’t expect miracles right away. Talenom has always been developed with a long-term perspective (which its growth track probably demonstrates), and this international expansion is indeed an interesting option in the coming years. 
9 Likes
The average price here is 5.88 euros, so I don’t think that should influence future purchases. Somehow, basing an investment decision on the average price doesn’t sound like the smartest move in the world. 
3 Likes
If everyone sees something, is that the best time to act on the masses’ view? 
1 Like
Is there any information available on the size of Talenom’s clients? What is the distribution like? Many large clients improve predictability and reduce cyclical sensitivity. Are there also people on this forum who have experience using Talenom? It would be nice to hear what their service is really like.
Edit: Someone asked this on Facebook, but there were no answers there, so I’m posting it here too.
2 Likes
In the ROAST, I challenged them on customer satisfaction because I always hear somewhat negative feedback about Talenom from acquaintances who use it, but then again, who wouldn’t complain about their accounting firm (and who would praise it out loud otherwise..). ROAST Talenom 15.5.2018 - Inderes
Positive profit warning from Talenom https://www.inderes.fi/fi/tiedotteet/positiivinen-tulosvaroitus-talenom-oyj-nostaa-ohjeistustaan-liikevoiton-osalta-vuodelle
10 Likes
The biggest slice of my portfolio.  Tomorrow, a live webcast of Talenom’s Q3 earnings report at 2:00 PM: Talenom liiketoimintakatsaus tammi-syyskuu 2018 22.10.2018 klo 14:00 - Inderes
8 Likes
Excited? 

Earlier, there were questions about negative experiences related to Talenom. Both my spouse and I have had some bad experiences. Among other things, after the birth of our child, there were ambiguities related to salaries. I will not discuss the matter further publicly here.
However, nothing so serious has happened that I wouldn’t believe in the company as an investor, and I also own shares myself.
*edit wording corrected
6 Likes
The biggest slice of my portfolio.
I wish it was mine too, but I hesitated and bought too little when it was at five, and now the valuation is already quite high. I’ll buy more sometime when there’s blood on the streets… The PEG (Price/Earnings to Growth ratio) isn’t quite where my buy button would start itching.
Talenom is a strange growth company in the sense that I’ve almost never heard good feedback about it from customers, yet everyone just sticks with it 
Many consumer companies would already be waving a red flag if they received so many, even anecdotal, negative comments.
2 Likes
I briefly considered investing in Talenom’s IPO. The idea was that as their customer, I would get some of the payments back through the stock. But because my experiences with Talenom’s automated “services” were so chaotic, I haven’t dared to jump on board. Enough times when customers’ patience runs out with those “not-so-functional” automatic features, they eventually vote with their feet, and then the share price takes a hit, and there’s no dividend.
Talenom has outsourced, for example, invoice scanning services to a company owned by Posti (Finnish Post), and this scanning service is quite subpar. It’s the Talenom customer’s responsibility to ensure that the automation does things correctly. And when the automation doesn’t put the numbers in the right place, the customer has to correct them manually. Hello! Wasn’t the automation supposed to prevent human errors and make the customer’s job easier? Now Talenom has managed to turn this 180 degrees; the human watches the machine!
Talenom’s online services, for example, in creating invoices, are straight out of the 90s. Fortunately, I don’t have to do them, because our company has a well-functioning ERP, and payment traffic is much easier with it. I only feel sorry for those customers who have to waste their time on Talenom’s automated services. The user experience is indeed catastrophic. Something as simple as retrieving the bank code from an IBAN account number doesn’t work in Talenom’s system; you have to go online to find the BIC code. Even Passeli professional, developed in the 1990s (fortunately, we got rid of it years ago), could extract it from the account number; Talenom still hasn’t managed to do it, even though it has been complained about for years. So much for that great automation when the customer has to figure it out themselves (e.g., refunds to online store customers; those customers never provide the bank code, only the account number).
The reason I am still a Talenom customer is that there is still a traditional human doing the accounting, and the cooperation works well. Fortunately, they haven’t ruined this yet. I dread and then I’ll have to do that big job again and find/tender for a new accounting firm (changing accounting firms is very laborious, which is why I haven’t done it yet).
Instead, Talenom has all sorts of managers. There’s an account manager, a service manager, etc. In five years, it’s still not clear to me as a customer what the role of these managers is. However, they do incur costs. In addition, the turnover among managers is high, which makes me wonder if their work is even meaningful?
6 Likes
Automated Accounting Line Is Buzzing

3 Likes
However, Talenom is still a surprisingly indebted company, with net debt at 107%. This means they use a lot of financial leverage, which naturally increases ROI. They can probably manage with this during low-interest rate periods, but when interest rates rise, it will eat into their profits.
I believe the high valuation of goodwill on Talenom’s balance sheet is one risk. When interest rates rise and the economy starts to slow down, Talenom’s customers will also start to struggle. There will be payment difficulties and even bankruptcies. This will certainly affect Talenom’s earnings and also the earnings of accounting firms paid “overpriced” (above book value) for, leading to significant write-downs for Talenom.
Goodwill accounts for half of Talenom’s long-term assets and 40% of all assets. In addition, “Other intangible assets” are valued quite highly; these are likely software and licenses. But fortunately, the equity ratio has risen significantly and is now close to a good level.
In my opinion, the upcoming recession is a risk for Talenom. Copied from the interim report:
“We are moving towards fully automated accounting, while accountants are able to provide higher value-added services. During the review period, we have for the first time seen good evidence that it is possible for accountants to also do billable, high-skilled accounting expert work for clients.”
When the economy starts to slow down, client companies will scrutinize their cost structures even more carefully. Accounting is mandatory and follows the monthly agreement made with Talenom. The price is fixed. But for these separately billed services (80-90 euros/hour), entrepreneurs will surely consider whether to do them or not, as they are not mandatory.
Talenom’s growth is based on acquiring new customers. Customers are brought in at a low price. At least we got quotes from 10 accounting firms, and Talenom was the most affordable overall. Automation probably lowers costs, but on the cost side, it is not scalable downwards. Once automation is developed, essentially the same costs run whether the customer flow is growing or declining. What happens if the number of customers decreases and costs remain the same?
4 Likes
I believe that indebtedness and goodwill were also commented on in the ROAST (or rather, we laughed more than we roasted, which also indicates something about the company’s quality)
Talenom also seems to be relatively recession-proof. Companies cannot just stop accounting like that.
3 Likes
True, Talenom is largely a defensive company regarding statutory accounting. So are many of its competitors. It’s worth keeping that in mind. But there is also a constant attrition in the client company field (a company closes, goes bankrupt, or is acquired). For Talenom, this is 5% per year, which must be replaced by new acquisitions. If the market slows down and new acquisitions fail, revenue will decrease. Of course, not as much as with a cyclical operator.
However, Talenom also has other services, such as sales ledger, HR and switchboard services, as well as advisory and legal (tax + law) services. These are not as defensive, and they have fixed salary costs, especially as they are still partly in the experimental stage.
I watched that Roast. Talenom’s CEO Jussi Paaso cited a study conducted by Taloustutkimus regarding customer satisfaction, which showed satisfaction to be at a good level. At this point, the reliability of the information should be critically evaluated. That is, who responded to that study? When Taloustutkimus calls and asks if you want to answer questions and it only takes 15 minutes, how many busy entrepreneurs answer “yes, I do!”? I myself have never (age 53) answered these. Or when Taloustutkimus (or what so ever) sends an email with the message “study,” how many busy entrepreneurs click that link and voluntarily go to answer? I consider these types of samples to be similar to what Iltalehti and Ilta Sanomat do on their websites. Or what someone does on Facebook. The result of the study is so distorted. The same problem also arises when the company’s own software sends an automatic survey that the customer should answer. This same problem affects almost all companies.
The best and most reliable feedback on satisfaction comes at a personal level (customer meetings). Talenom has this under control, meaning they meet customers personally at least once a year. As long as the information then spreads from the field staff upwards, and things are developed. Also from the franchising entrepreneur to Talenom.
Talenom’s stock market history has been excellent, and it will probably continue, and the company is in good shape. But the stock price currently has strong future expectations at this valuation level, and it feels like the risks have been calculated to zero. However, there are risks, for example, regarding technology, and these risks can affect future dividend flows or the share price.
4 Likes
I spoke with Juha in a video about indebtedness and the impact of the recession on Talenom. Talenomin pitää investoida tarkasti vuolaat kassavirtansa.. - Inderes
Insiders have sold a net of one million this year  Pohjoismaiden sisäpiirin kaupat | Reaaliaikaiset johdon kaupat - Inderes
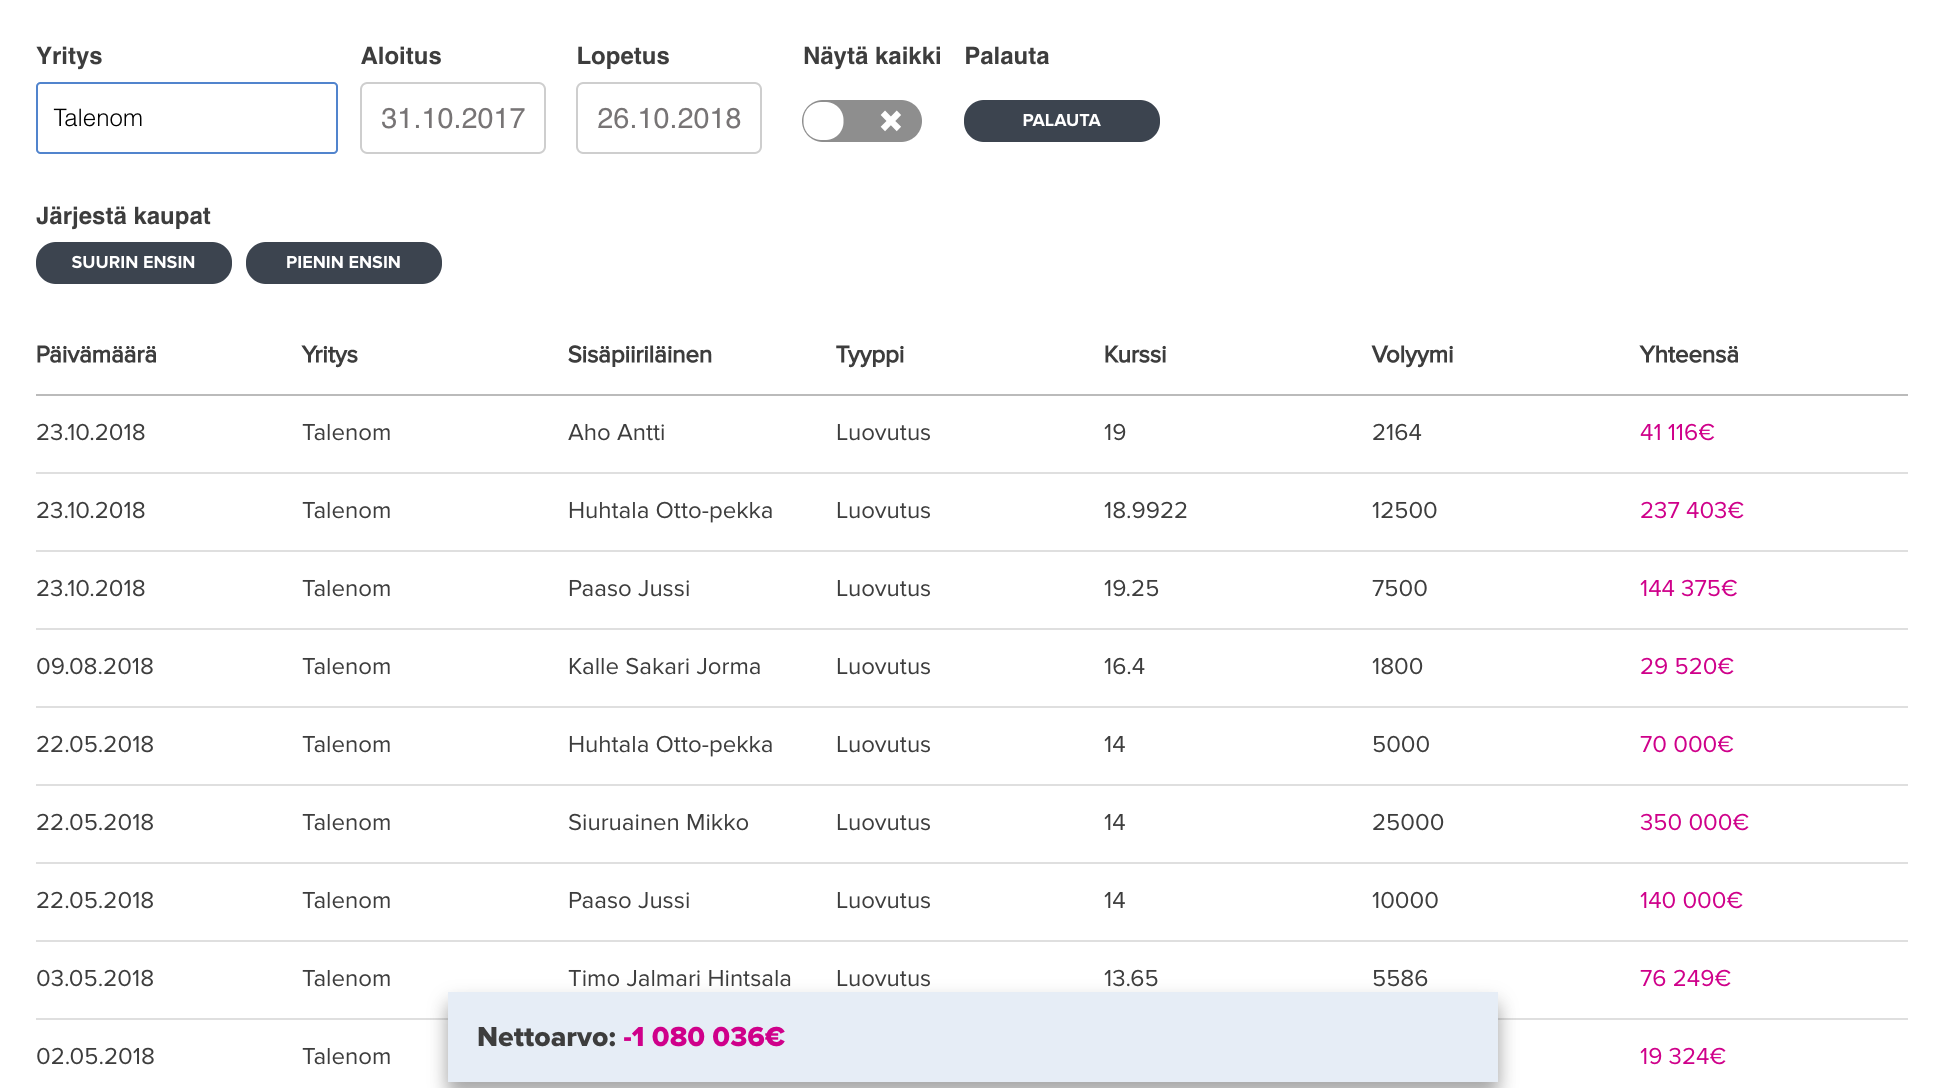
Apparently a lot of bathroom renovations, although the main owners, i.e., the Tahkolas, have not sold.
6 Likes
It has indeed come down really hard after the Q3 rise within this week, losing 12% of the stock value from the post-earnings peak… Of course, the intention is to hold these, so these short-term fluctuations don’t mean much. Still… 
Well, I think it’s just normal fluctuation; the indices have also come down by about 10-13%. 
Talenom has still risen 40% since the beginning of the year.
2 Likes