The agreement signed by steel company SSAB’s subsidiary Tibnor in December 2025 with Ovako for the acquisition of Ovako Metals Oy, the Finnish distribution unit, has received approval from competition authorities, SSAB announces.
Ovako Metals stocks, processes, and distributes steel and metals for the engineering, process, and construction industries, primarily in Finland. The company has approximately 40 employees, and its revenue was 40 million euros in 2024.
Following the acquisition, Tibnor will take over Ovako Metals’ distribution operations in Finland, including the product range, logistics and warehousing services, processing services, and local sales organizations.
I’ll be surprised if the share price drops. Regardless of how it goes today, it’s solid performance, which was of course expected (price and forecasts).
In the big picture, SSAB has shown convincing performance for years already. The next step up in the share price will likely come in a few years if the SEK 23bn EBITDA target/guidance starts to look realistic. For this year, EBITDA is expected to be around SEK 13bn. I personally believe in the target, and I’m sure the market will start to believe it as well at some point.
Here is an article from SalkunRakentaja about SSAB, which takes a few minutes to read.
The US steel market has tightened rapidly. Tariffs from the Donald Trump administration have pushed import volumes down, and distributors’ inventories are running low. Delivery times are lengthening, and local rollers have gained leeway in their pricing.
Steel prices have recovered from last autumn’s dip, and the scarcity of supply is maintaining upward pressure.
Subheadings:
Earnings report revealed where the advantage arises
Over 1.5 months passed, and it was concluded that it has simultaneously been dusty, dry, and flu season.
=> the construction site gates can be opened again
Detailed analysis suggests that the symptoms were primarily caused by exposure to fine dust particles, with effects exacerbated by low air humidity and the presence of seasonal respiratory viruses.
The symptoms arose from the combined effect of several factors, where weather conditions such as cold and wind also promoted the spread of dust and increased respiratory sensitivity. Dust concentrations have been at levels typical for this type of workplace, not elevated or toxic.
Q2 report is out: pretty much as expected, solid fundamentals, good performance.
The EPS is now at 3.69, but the momentum won’t continue at this pace (Q3 and Q4 maintenance). My guess is that we’ll end up somewhere around 7. From that, a flat 3 SEK dividend next spring.
It seems to be chugging along on track, and I always keep coming back to the 2030 EBITDA guidance: 23 billion SEK. That’s roughly double what it will be this year.
At that level, the EPS could be around 13 SEK, but it’s harder to guess acceptable multiples. That’s my rough expectation. There are, of course, risks in both directions.
JP Morgan raised its target price for Outokumpu today; now, Bank of America has done something similar for SSAB. At 2:41 PM, Finwire reported (based on an AI translation of the Swedish news that I slightly refined):
BofA raises forecast for European steel prices - raises target price for SSAB
Bank of America is raising its forecast for the price development of hot-rolled coil (HRC) in Europe and now expects an average of 775 euros per ton in 2027, up from the previous 730 euros. The price is expected to rise to approximately 750 euros per ton by the end of 2026. This is based on BofA’s analysis.
The bank estimates that approximately 730 euros per ton forms a new price floor for European steel, while 800–850 euros is considered a ceiling where imports become more competitive again. Higher price forecasts lead to an increase in profit forecasts for several European steel companies.
The forecast for SSAB’s adjusted EBITDA for 2027 is raised by 4 percent to 18.2 billion Swedish kronor, which is 6 percent higher than the consensus estimate. The forecast for 2028 is raised by 6 percent to 18.1 billion Swedish kronor. BofA raises the target price to 120 (107) kronor [120 SEK = approx. 10.94 EUR], but maintains a neutral rating. The bank sees support from the rise in European steel prices and the recovery of the U.S. plate industry, but believes that the valuation is relatively full and points to risks related to SSAB’s restructuring investments and ongoing cash flow pressure.
SSAB’s share price has taken quite a beating this year and over the last 12 months. It’s starting to feel like a good entry point for a small position.
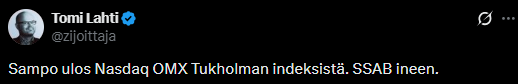
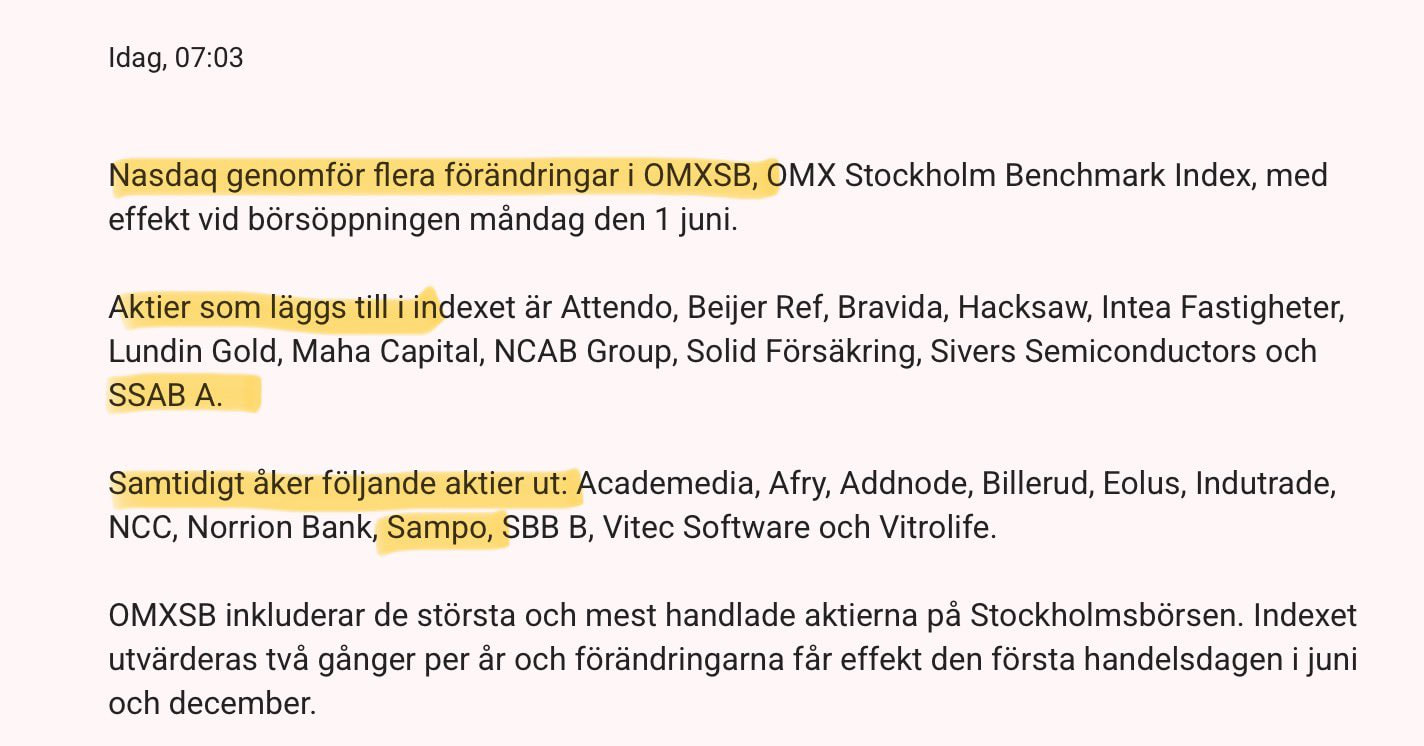
I don’t know if it indicates buying pressure for the more liquid B-series shares, but it has been peculiar that the B-series has been more expensive for several days now.