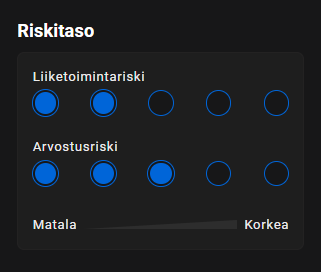
Isn’t Sanoma pretty cheap and low-risk?
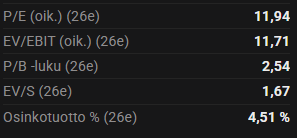
The Learning business revolves around printed and digital learning materials, among other things, and this side is doing well. Furthermore, it is believed that the outlook is good for both growth and earnings in the near future.
The company has a strong position and indebtedness is moderate. In addition, the company report mentioned: “The growth in the relative share of digital revenue strengthens the profitability potential”
The print side probably isn’t very sexy and forward-looking, but that’s been known for a long time. Risks could include the company starting to make foolish and giant investments, or if a dominant international AI giant competitor appears out of nowhere, but these are a bit far-fetched horror scenarios, though remotely possible perhaps.
Few and small risks…
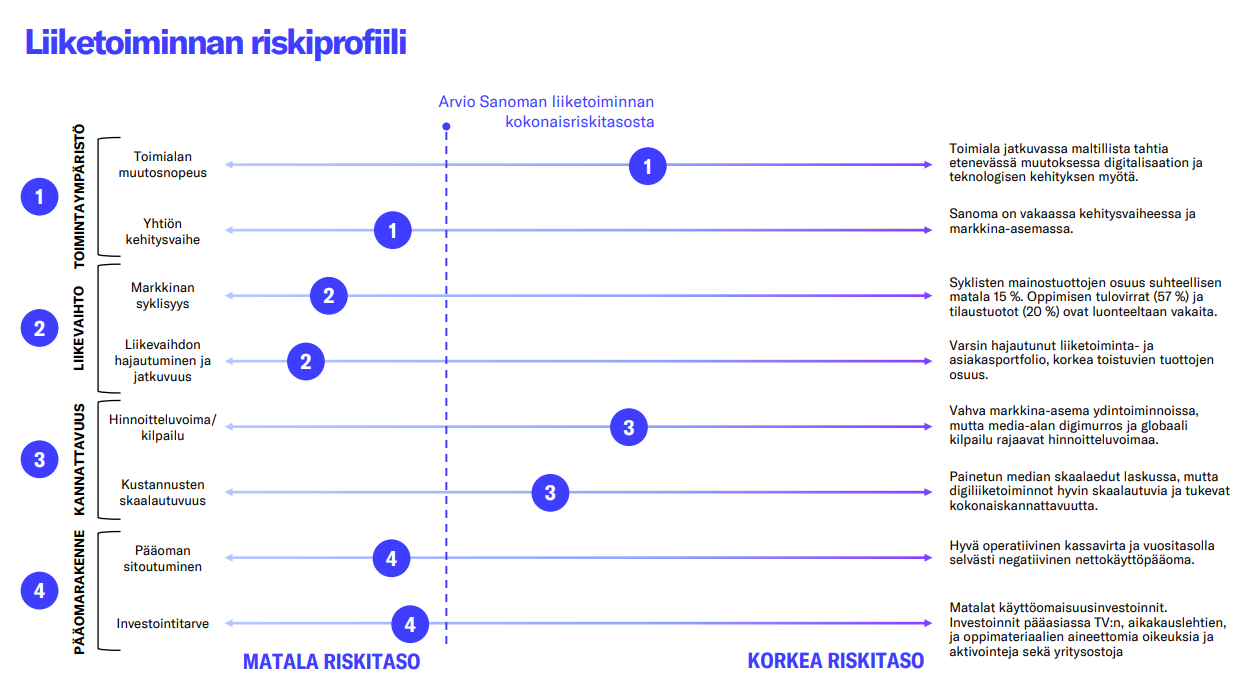
… Learning is growing profitably again and as user tonyfrank aptly pointed out:
Strategically interesting are the three Learning acquisitions in 2026 and the concrete AI investment, where the AI Teacher Assistant had 88% of teachers rating its materials as at least equal to their own. Thus, the thesis does not change — a potential share price decline due to debt and cash flow headlines would mask the on-schedule progress, and the real resolution will be seen in Q3.
Couldn’t Sanoma be a good cornerstone for a portfolio?  Sanoma is such a boring name and the industry sounds boring, so perhaps that’s why Sanoma has at least tried to get attention from investors in various ways. Do I need to invite a Sanoma representative to the Alokas haastattelee (Alokas Interviews) thread…
 Sanoma’s Rob Kolkman was even interviewed by my comrade @m_jylha in his podcast in February.
Why isn’t Sanoma generating any discussion?