A dedicated thread is still missing, so let’s start one. Did you know that Sampo is a financial group engaged in life and non-life insurance as well as investment activities?
Is anyone else in or considering getting in?
The general market situation is turning sideways or into a recession, so how do others see the company’s risk profile at the current valuation?
The risk for Sampo (what’s the correct inflection? :D) is mainly with Nordea. The insurance business is quite stable and well-trimmed. Of course, the downside is that it’s harder to grow the insurance business’s profits.
This stock is unlikely to crash, but on the other hand, I don’t see significant potential for a rise unless major corporate restructurings happen. Compared to that, the stock is priced quite neutrally. I might almost keep an eye on this if I could get it cheaper than it is now during a bigger market downturn.
I think it makes more sense to own Sampo than Nordea directly now. Nordea is probably undervalued, but Sampo might also make a direct deal at price X with, for example, Gardell. I don’t know how a small investor could be left out in this scenario, but that’s my gut feeling.
Sampo is apparently well prepared for a possible recession and benefits from rising interest rates.
A good third of Sampo’s price is Nordea. If an arrangement comes about, it will likely involve all of Nordea, not just the portion owned by Sampo. I don’t believe Sampo can leverage its own share in a way that wouldn’t similarly benefit all Nordea shareholders. So, if one believes in a significant arrangement with Nordea, the best returns would likely come from a direct investment in Nordea.
If Sampo as a whole seems more attractive, then it’s a more sensible investment. One shouldn’t put money into this stock purely for Nordea’s potential.
Yes, Sampo can make a deal bilaterally. For example, if buyer X wants a large stake in Nordea, the options are either to buy from a major shareholder or from the market. If one starts accumulating shares from the open market, the price can spiral out of control. If an owner has grown tired of Nordea’s slow progress or cannot be bothered with arrangements, X can buy a whole lot of Nordea at once, at an agreed-upon price (which is presumably lower than what would be obtained from the open market).
The selling party, in turn, benefits because if they dump shares on the open market, the price can plummet.
So, if Sampo sells with a 15% premium, then Nordea’s public share price might not react in the same way.
I personally view this matter from the perspective of diversification. I want to own Nordea, but I find owning it through Sampo more attractive for several reasons.
Everything is possible. However, I don’t really see any party wanting to buy only Sampo’s share as such. Sampo probably doesn’t want to sell for a small premium either. If Sampo no longer sees potential in Nordea and is proactive in selling, it probably won’t get a premium. The only possible scenario I can imagine is some kind of corporate arrangement concerning all of Nordea, and all shareholders benefit from it.
That could very well be. I don’t really see Sampo as an activist investor who would do anything very radical. Sampo streamlines and optimizes more – it’s a “taskmaster.” Björn Wahlroos’s (Nalle) style, e.g., in Nordea and UPM, and in the insurance sector. Strict cost control. That hasn’t produced entirely desired results in Nordea; the IT reform might indeed have been somewhat unsuccessful.
This, of course, is speculative, and you might be right. But if Stadigh says that patience is running out regarding Nordea… Then what does that mean, and what could Sampo’s exit strategy be?
It could mean, for example, a change in management, a split of Nordea, or some other arrangement. Stadigh’s statement doesn’t allow us to conclude that the goal is an exit. Sampo merely wants to utilize Nordea’s potential as efficiently as possible.
You’re right. Besides, it would be a huge deal if Sampo sold its share in Nordea. A pretty big pile of money for which a (better) target would have to be found.
How much of Sampo’s share price was Nordea, again?
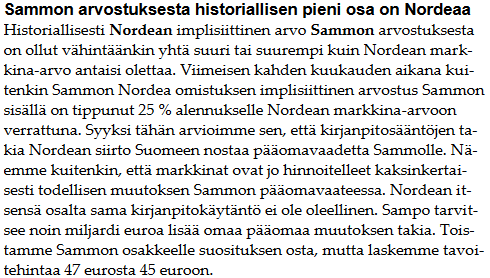
Nordea’s market value is a bit over 31 billion and Sampo’s share of that is a bit over 21%. Sampo’s market value is a bit over 21 billion. A quick calculation gives the answer of approximately 31%.
Yeah, so it confirms my notion that I prefer to own Nordea through Sampo. I trust that Stadigh and Nalle know how to play the Nordea game better than I do, whatever happens.
How on earth was that 25 percent discount decided? Is an assumption being made here that the market is pricing Sampo’s other businesses at a certain price?
I don’t claim to be a language police, but assuming Sampo gets its name from the Kalevala’s wealth-making machine, then it would be inflected as Sammon, not Sampon (cf. the scene called “The Sampo’s Robbery” in the Kalevala).
I still have a larger slice of Nordea than Sampo in my portfolio for now, but I intend to add Sampo with a few purchase transactions at some point, so that Sampo would be the larger slice…possibly even the largest single position in my portfolio at some point.
I just stumbled upon this. Which one wins the arm wrestling match, Nordea or Sampo. If one person buys Nordea and another buys Sampo, both can of course be right, not just one. However, they are both different companies. A Nordea buyer might, for example, have a more confident understanding of the banking sector in general, while a Sampo (Yep, Sampo) buyer might appreciate defensive dividends and corporate management, etc.