There are already forum threads on electronics contract manufacturers such as the Finnish Incap and the Norwegian Kitron ASA, so let’s open a dedicated thread for the Swedish company NOTEn as well.
Basic Information About the Company:
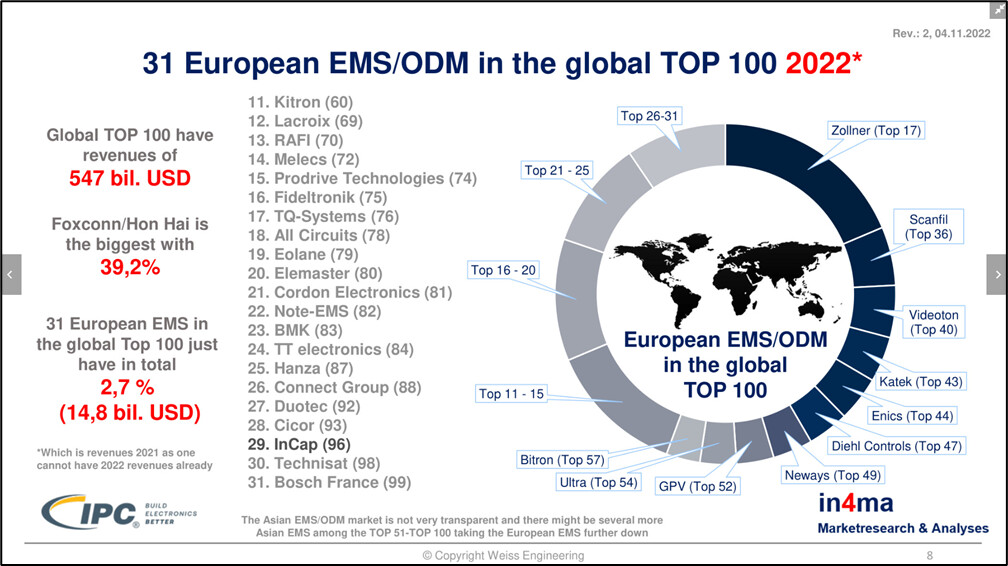
Like Incap, NOTE is an electronics contract manufacturer—specifically, one that fits into Europe’s top twenty in terms of size. It manufactures its customers’ products and parts of them. Therefore, it is an operator to which manufacturers of, for example, EV chargers or surveying instruments outsource their production, leaving tasks primarily related to sales, marketing, etc., to NOTE’s customer. Increasingly, R&D, logistics, maintenance, servicing, and more are also being outsourced to NOTE.
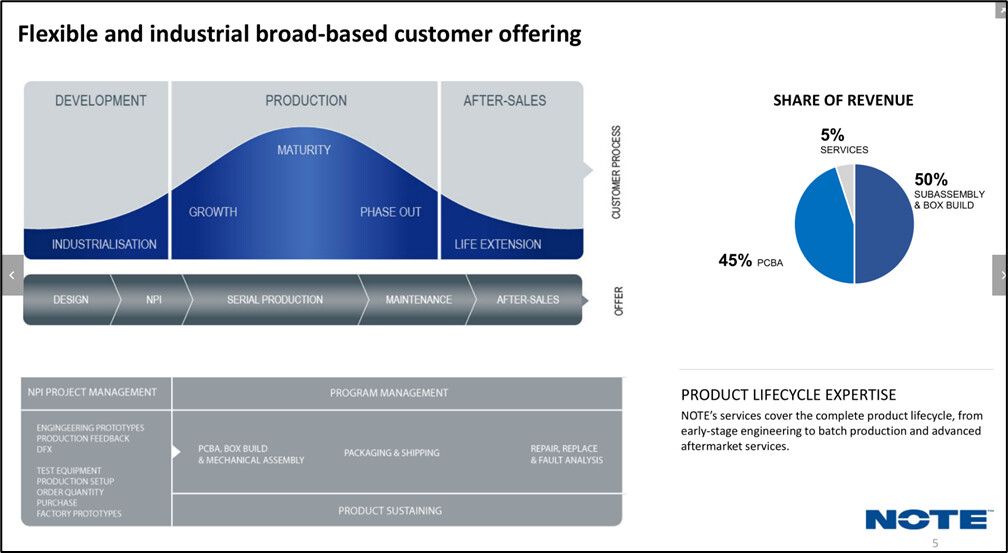
About half of the net sales come from PCB assembly, and half from box-build, which roughly means manufacturing complete products ready for end-user needs.
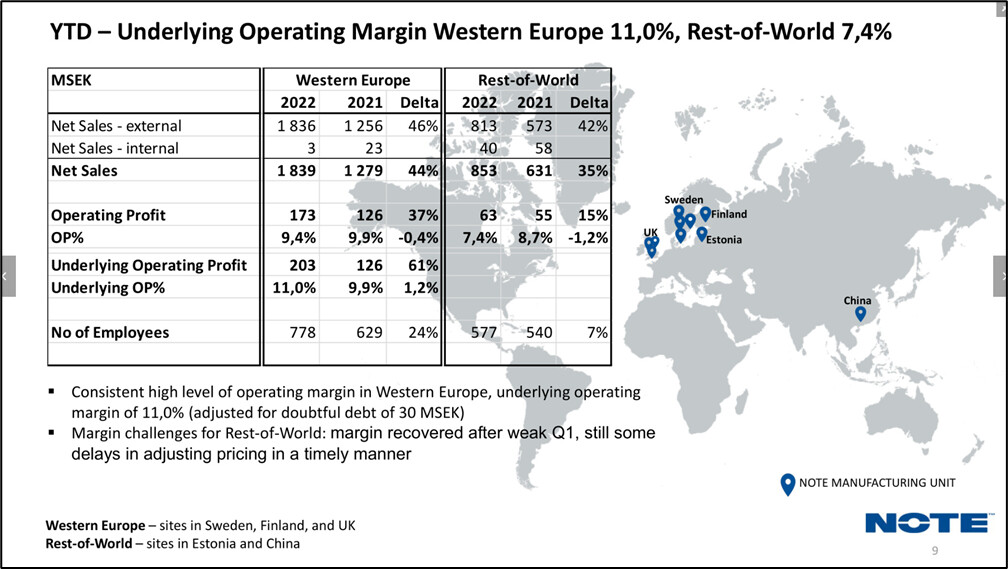
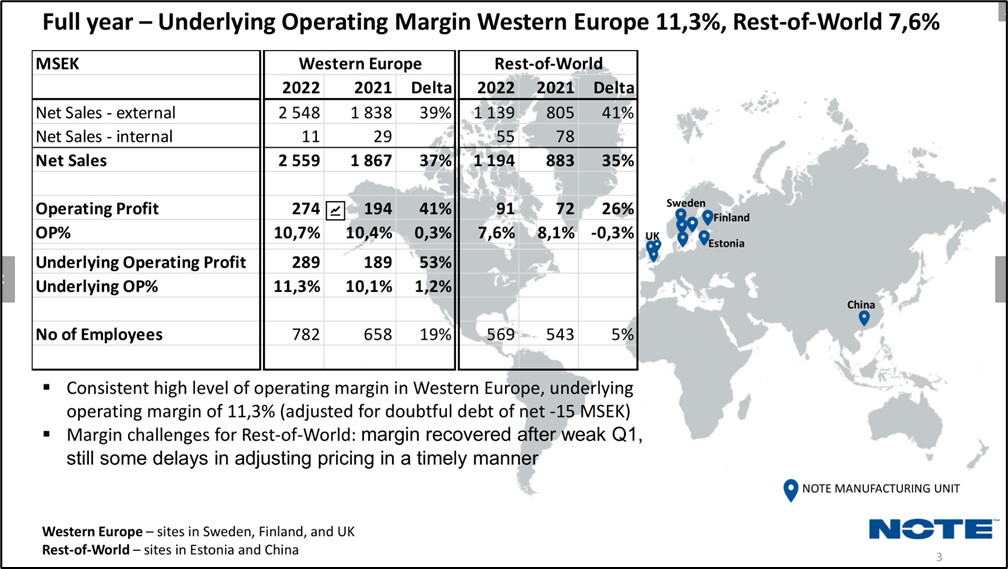
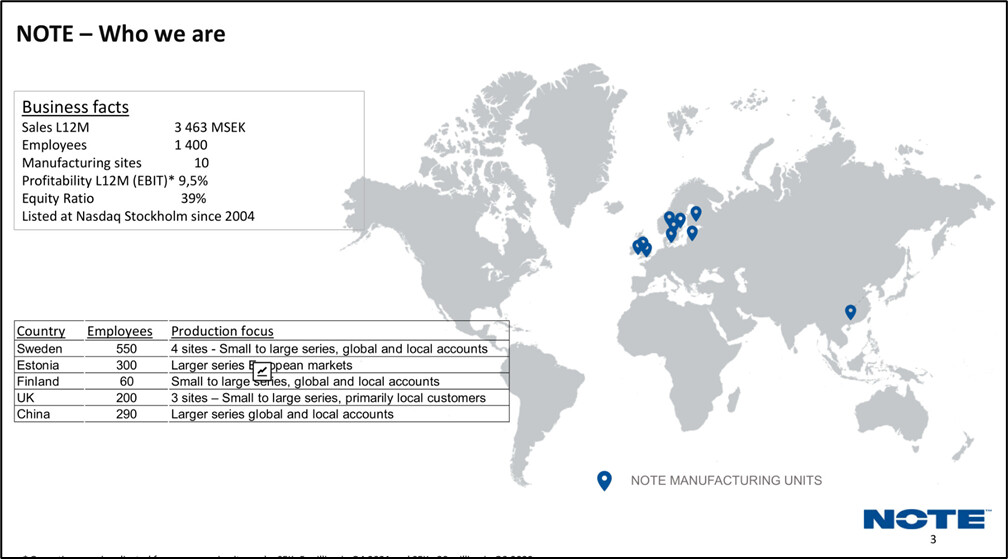
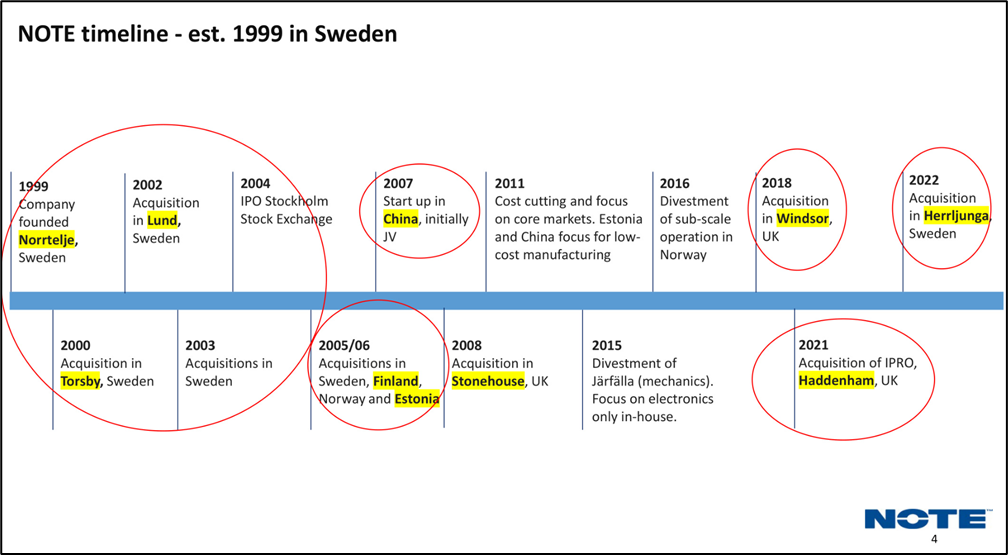
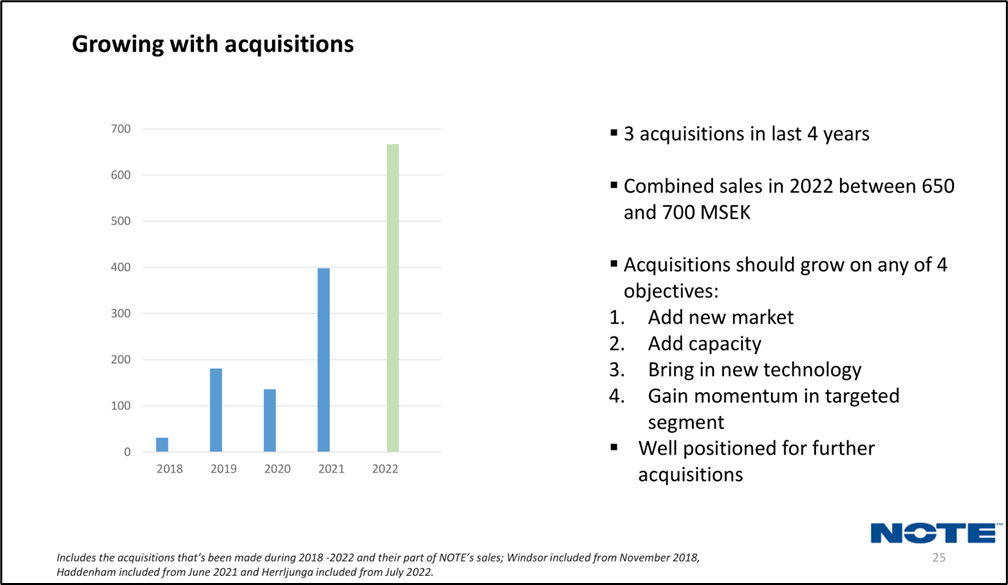
NOTE has four production facilities in Sweden, one in Hyvinkää, one in China, one in Estonia, and three in the UK. Historically, acquisitions have played a quite significant role, as can be seen from one of the images below.
Customers and Products
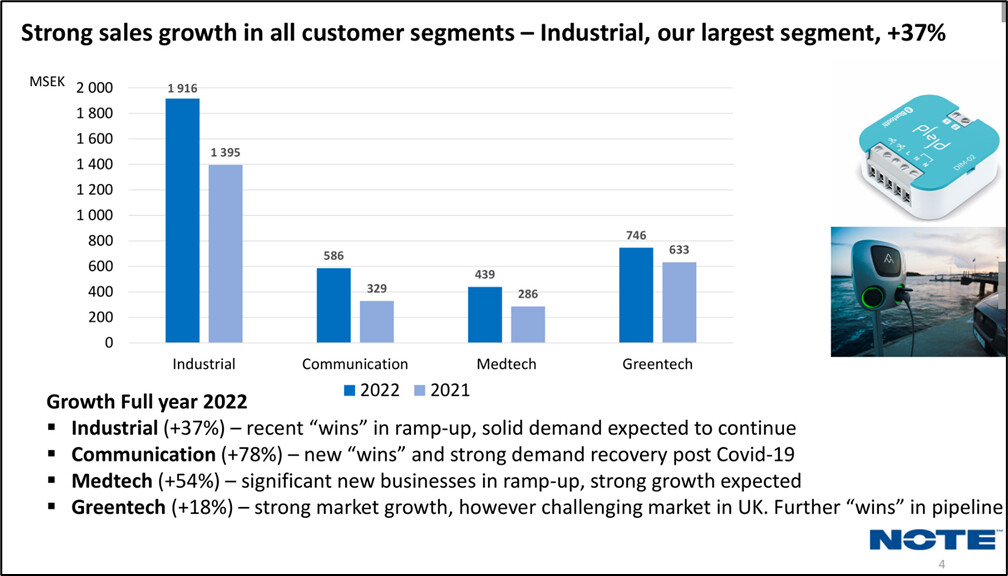
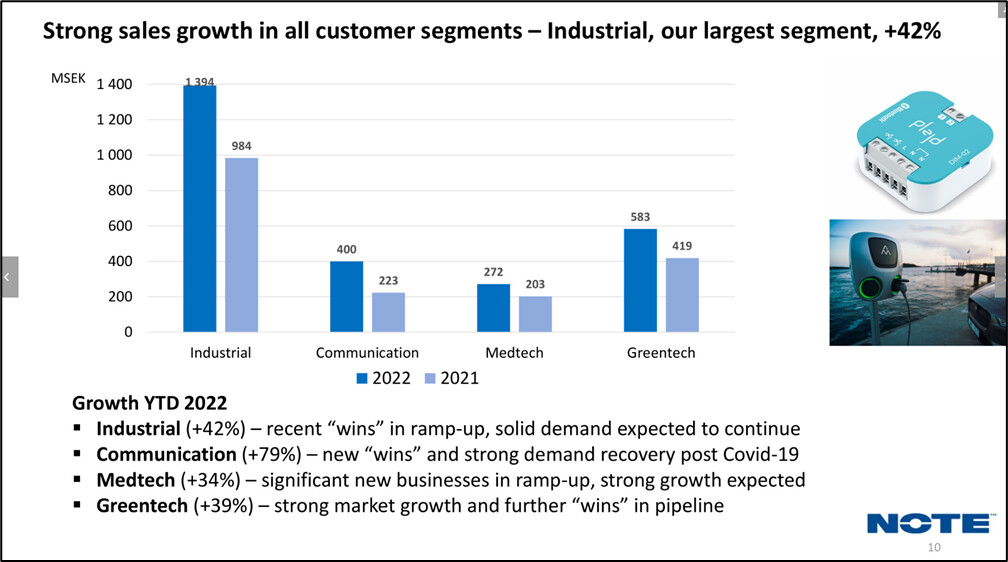
NOTE’s product/customer portfolio is divided into four parts: Industrial, Medtech, Greentech, and Communication. Industrial is clearly the largest segment, and according to NOTE’s management, this segment could be divided into countless sub-segments because the overall picture is so vast. All segments are reportedly performing well, and there is no need to prioritize one segment over another for better profitability, for instance. NOTE’s CEO mentioned at the December 2022 Capital Markets Day that, for example, in the medtech segment they have a great pipeline which he believes will materialize into figures in the near future. On the other hand, he also said that greentech, for example, will also grow rapidly, and they have been somewhat disappointed with this segment’s growth figures in 2022.
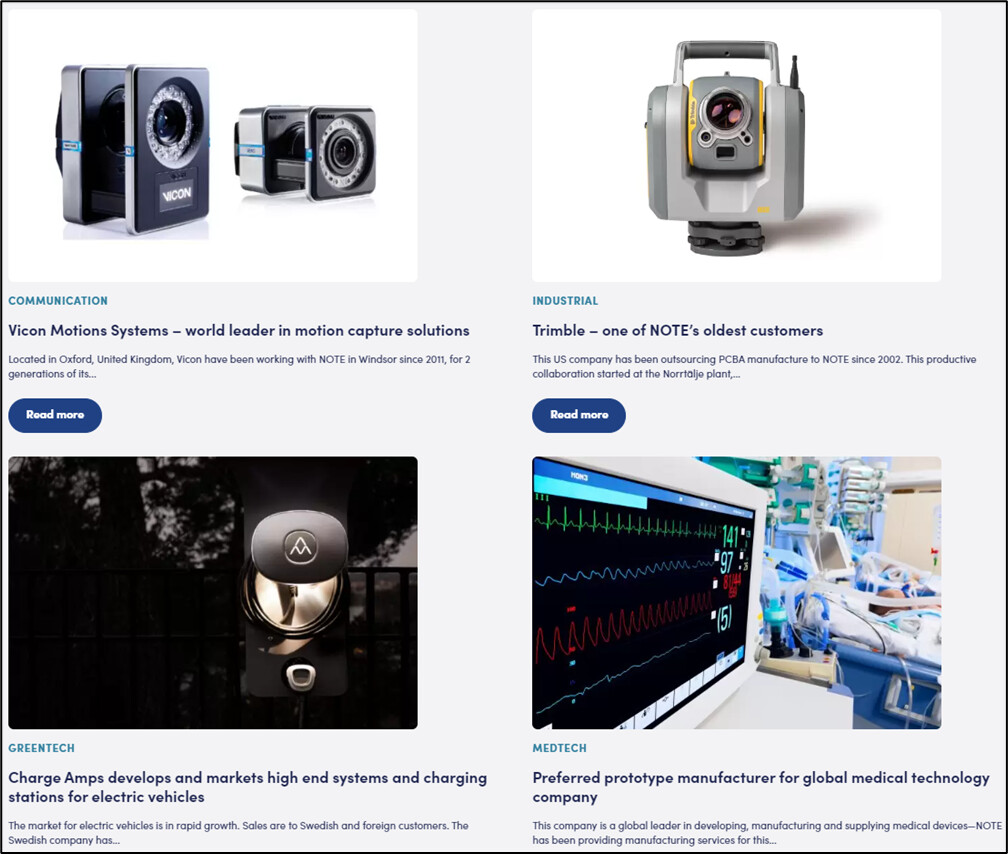
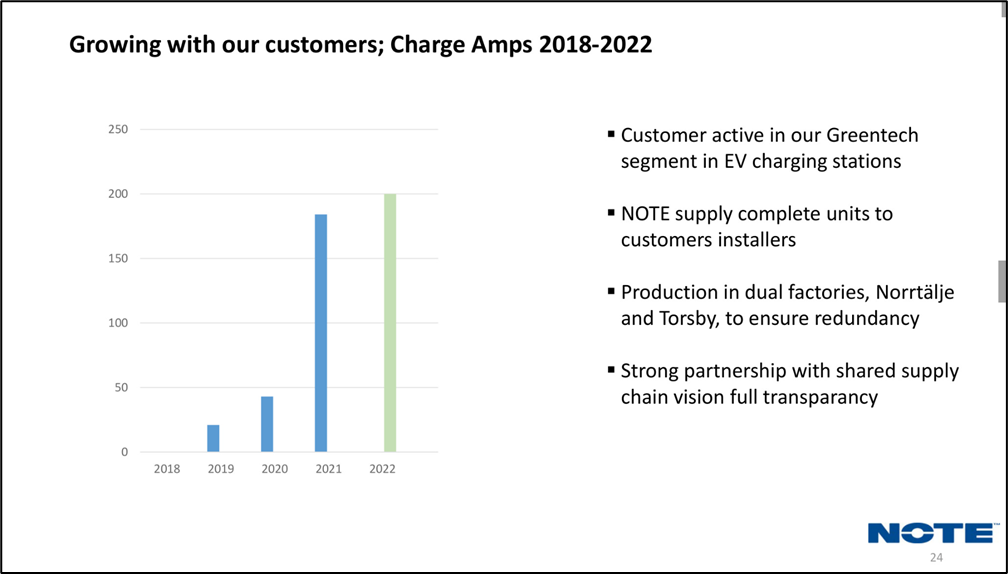
Typically for an EMS provider, NOTE says very little about its customers and rarely mentions them by name. However, some references can be found on their website, such as ChargeAmps, which manufactures EV chargers, and Trimble, which manufactures surveying technology. It is worth noting, however, the following excerpt from the 2021 annual report:
Generally speaking, NOTE has a diversified customer base where no single customer (group) represents more than 7% (6%) of total group sales.
For comparison, it can be mentioned that Incap’s largest customer, Victron Energy, accounted for over 60 percent of its total net sales, making it quite justified to say that present-day Incap lives and dies with Victron Energy. NOTE does not have this kind of customer dependency on a single customer.
NOTE—like presumably all companies nowadays—wants to be a close strategic partner to its customers. And it is probably true that the importance, influence, and share of the value chain of EMS providers are greater than before due to outsourcing trends. However, it is good to remember that these companies live under chronic profitability pressure, squeezed at the bottom by raw material and component sourcing and at the top by customer negotiating power. Large and established customers are often global players against whom an EMS provider may have very limited room to argue.
Business Development
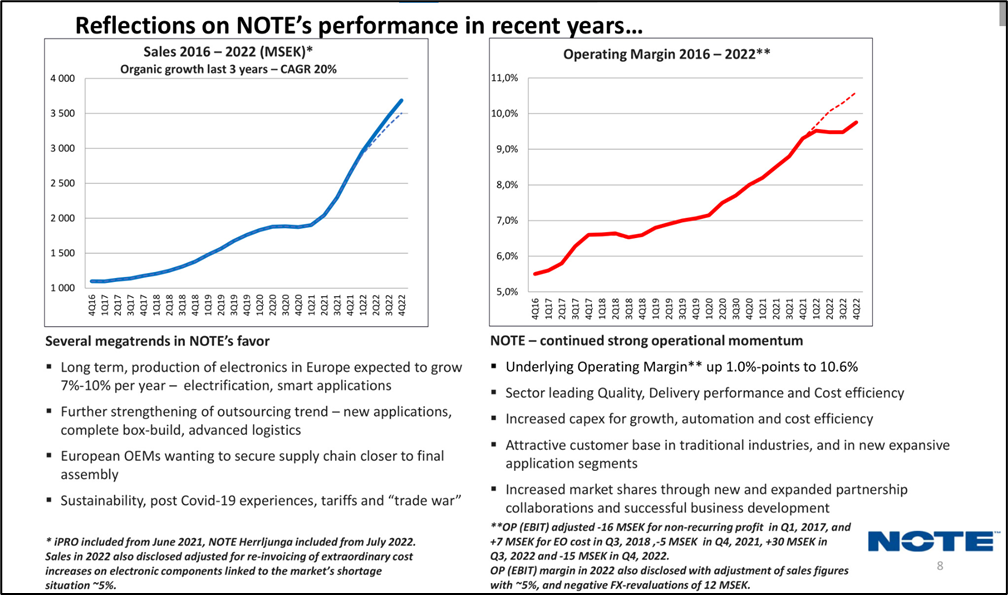
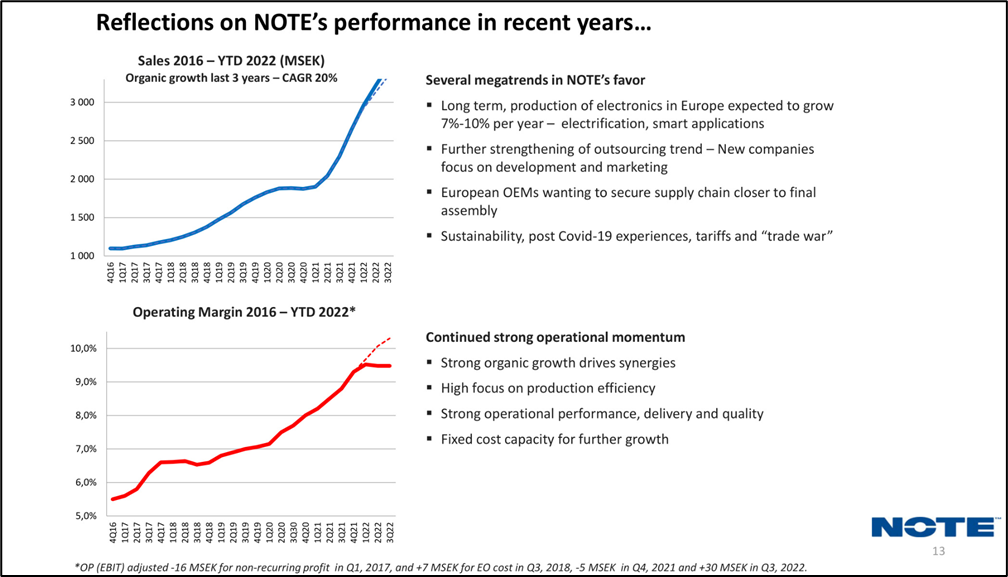
NOTE’s share price has skyrocketed over the past ten years. Over the last five years, the stock return has probably been 50% per year, and annualized over ten years, presumably around forty percent.
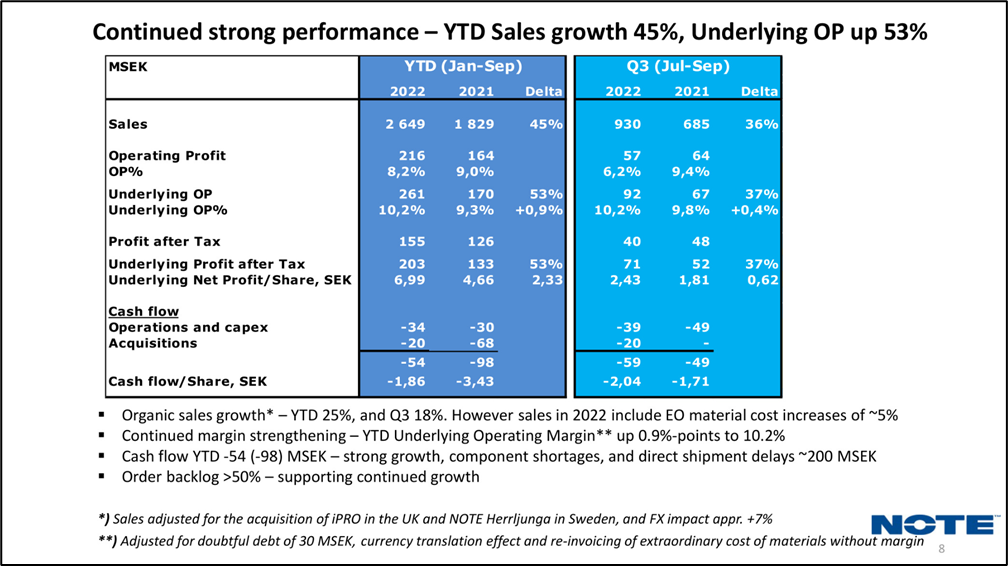
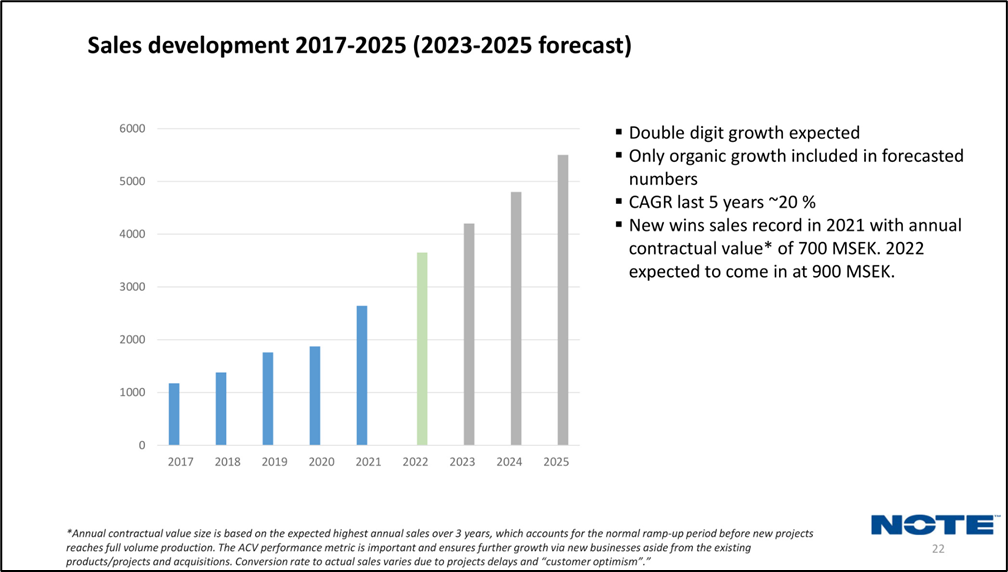
The reason for this is, of course, largely the excellent development of the business. About ten years ago, net sales hovered around one billion SEK, whereas now it is roughly fourfold. The company was also unprofitable in some years during the early 2010s, whereas now it generates an EBIT margin of around 8-10 percent (cf. Incap’s 13-15%). I am not entirely sure if the NOTE of that era was even quite the same business-wise as today’s NOTE, but the development has been staggering nonetheless.
The company’s CEO, Johannes Lind-Widestam, has been at the helm for four years and stated that when he started, he didn’t believe a company like NOTE could grow organically by over 20 percent. Now, however, he sees that this is a completely normal growth rate for a good EMS provider, and there is nothing extraordinary about it.
So here are some figures on the business and its development:
- Over 20% organic net sales growth for the past 5 years
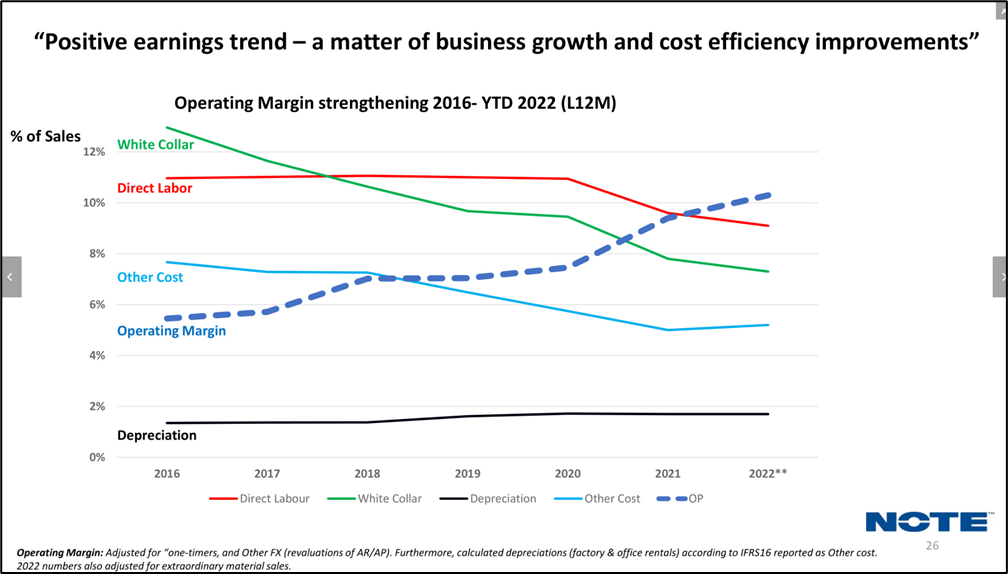
- EBIT-% raised from six to close to ten in five years
- ROIC of 10-20 percent depending on the year
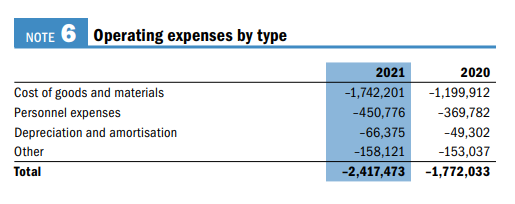
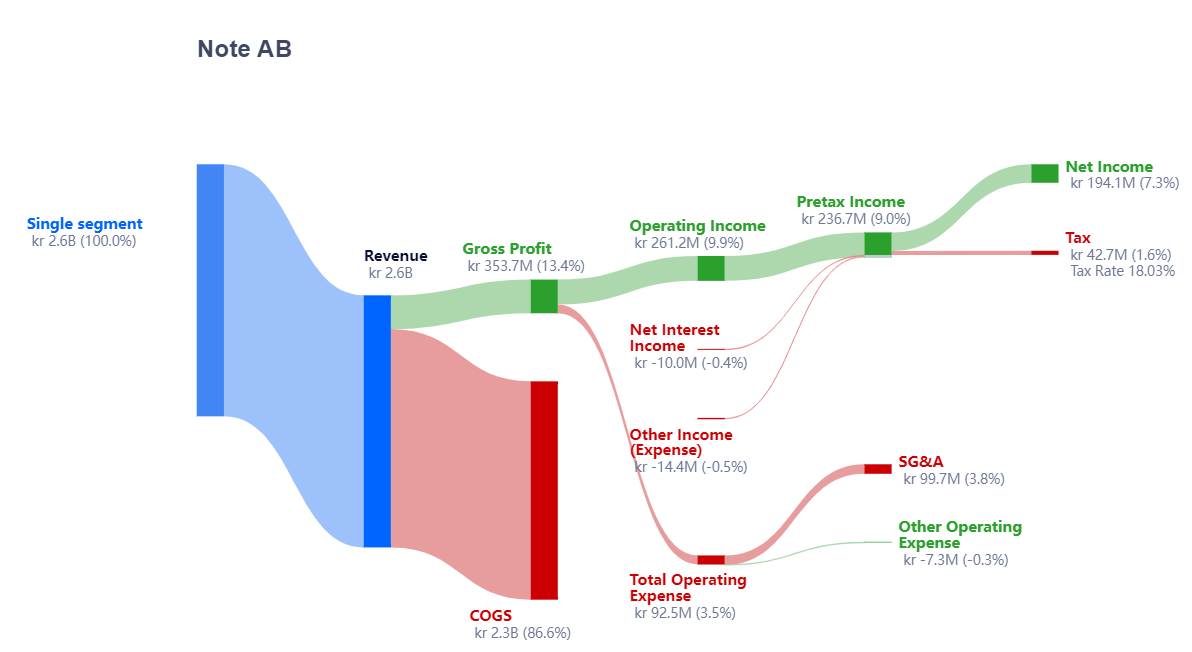
Interestingly, however, the gross profit margin is only around 13-14 percent, whereas at Incap it is somewhere above thirty percent. According to the CEO, the target is even “Incap-level” profitability, but with this gross margin, that is impossible. Therefore, there is still work to be done regarding profitability development, and even the official target of a 10 percent EBIT margin is already excellent for an EMS company. In this game, Incap is right at the cutting edge regarding profitability, and a bit beyond that.Addition 27 Jan 2023:
Correction to NOTE’s gross margin percentages. Due to NOTE’s reporting method, the gross margin already includes personnel costs. Removing these means that the gross margin for 2021 was actually 30.5% instead of the previously mentioned 13%. Consequently, NOTE’s gross margin is effectively already very close to Incap’s gross margin, and the most critical profitability comments in this opening post do not reflect reality. See the detailed information in the subsequent messages by Joonas and Mauri.
Acquisitions
The M&A market in the EMS sector is hotter than hot. Incap, NOTE, Kitron, and all the others are competing for the exact same targets. The market is consolidating strongly (Incap’s CMD had a good market overview).
The funny thing—though probably not for the buyers—is that everyone right now wants to buy EMS players that:
- operate with growing and profitable modern technologies
- have a flat hierarchy and are able to operate very independently and agilely
- do not operate in cyclical sunset industries (e.g., traditional automotive)
- are located in North America, Germany, or in some cases Eastern Europe
- are not some poor-profitability turnaround stories
- are not squeezed by old and bad customers
- are neither too small nor too large
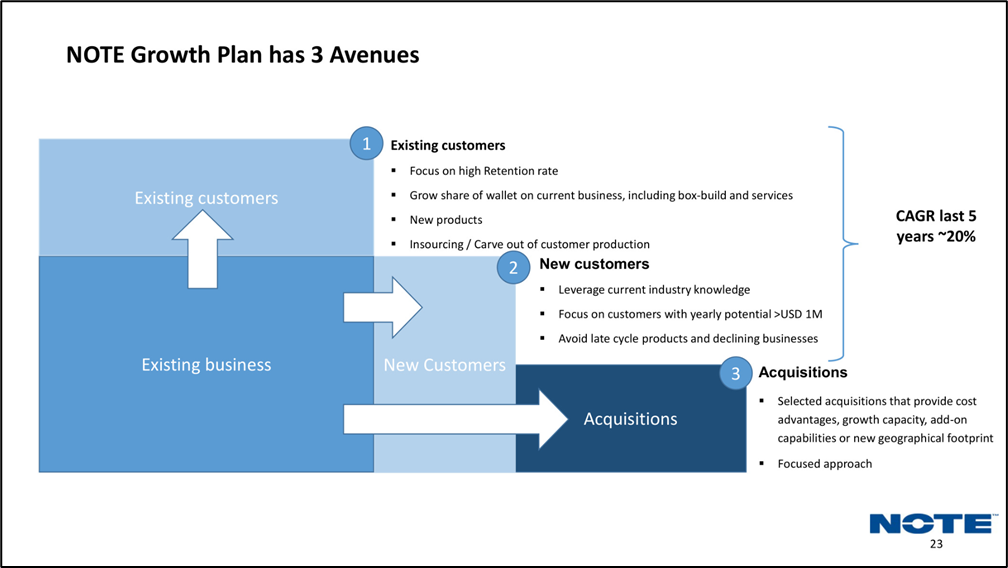
NOTE’s own principles for acquisitions can be found in the image below.
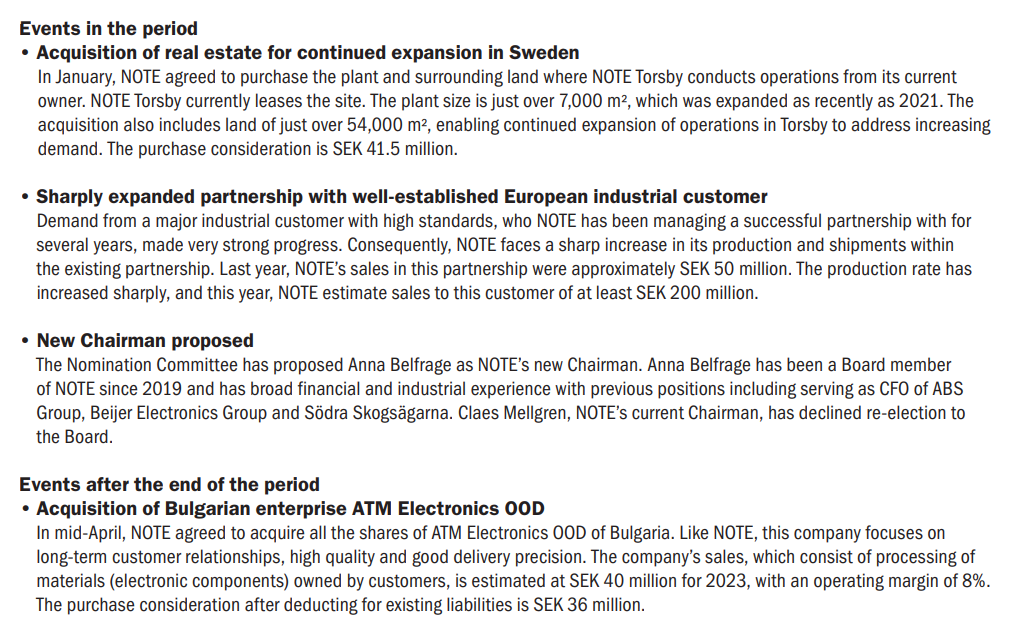
Perhaps it’s no wonder that Incap has been looking for acquisition targets for years, and NOTE has made maybe one acquisition per year. Apparently, it plans to continue at that same pace.
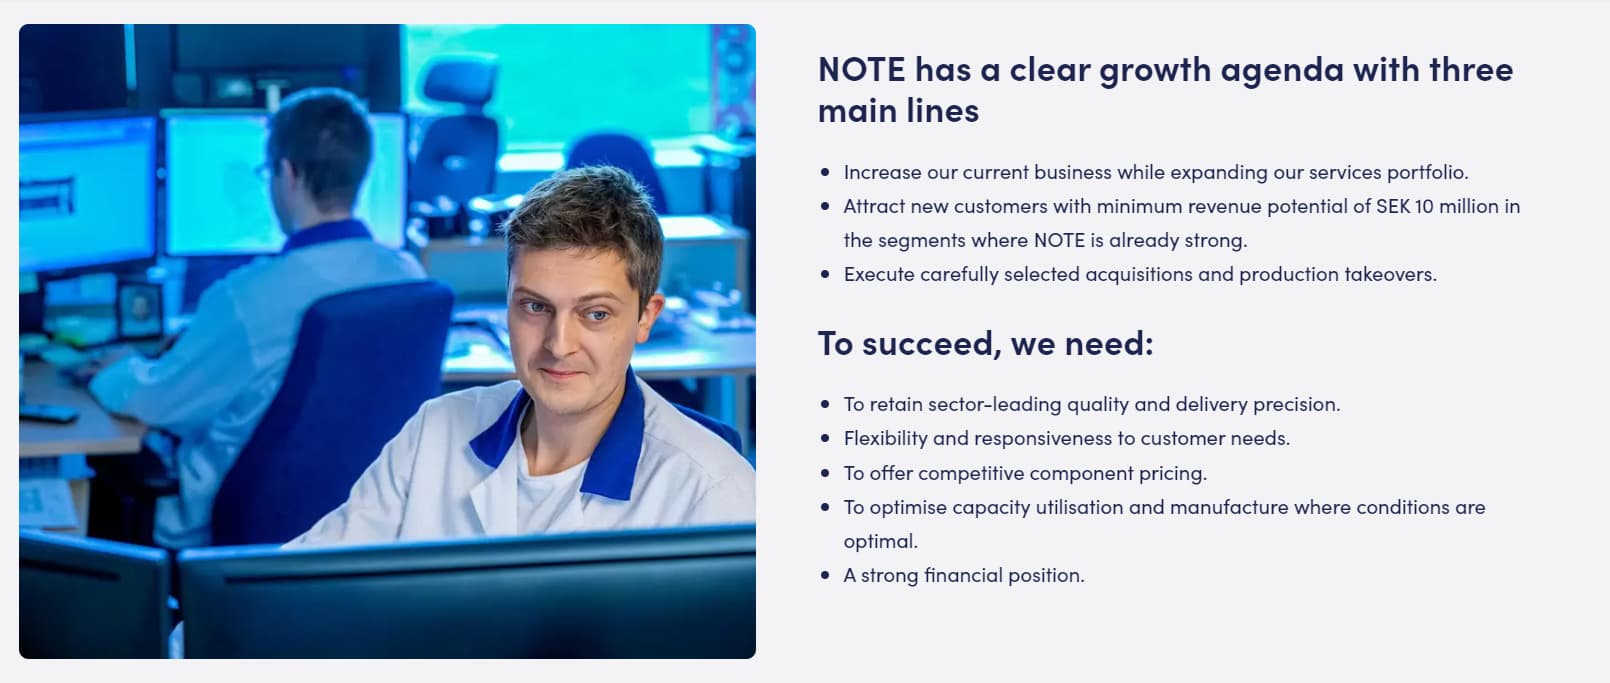
This image from NOTE’s CMD illustrates well how growth is sought first from current customers (usually large customers grow big), then from new customers, and only finally through acquisitions.
Outlook and Valuation
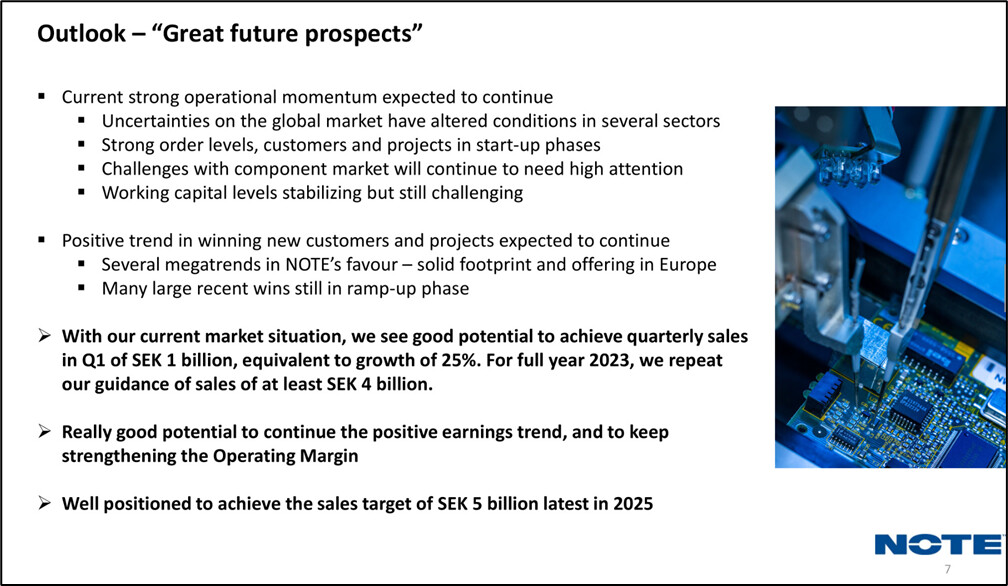
NOTE’s future looks bright (excerpted from the Q3/2022 report):
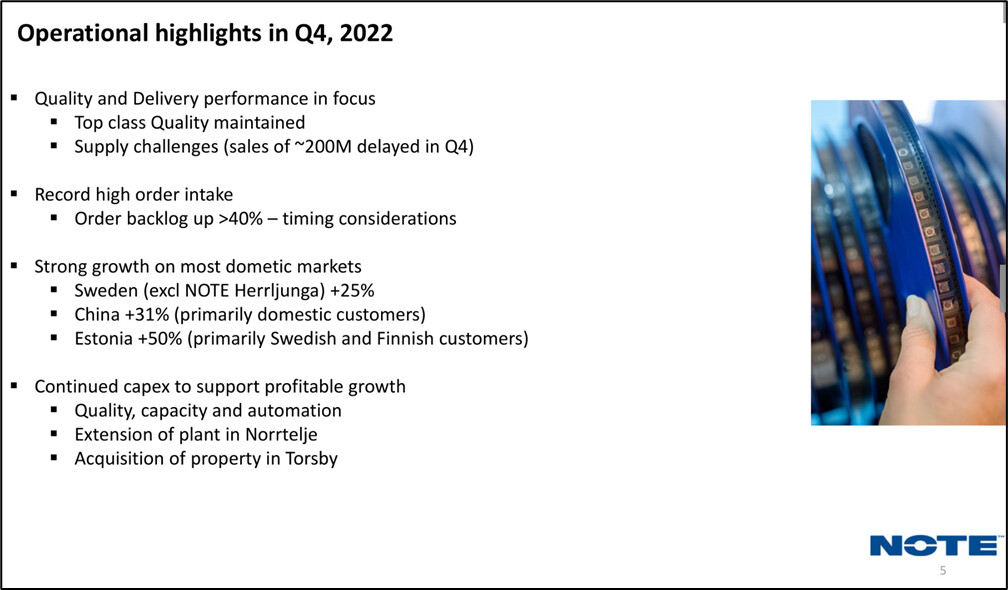
Successful new sales to new and current business customers, and continued healthy demand in all customer segments, were contributors to record-high order intake.
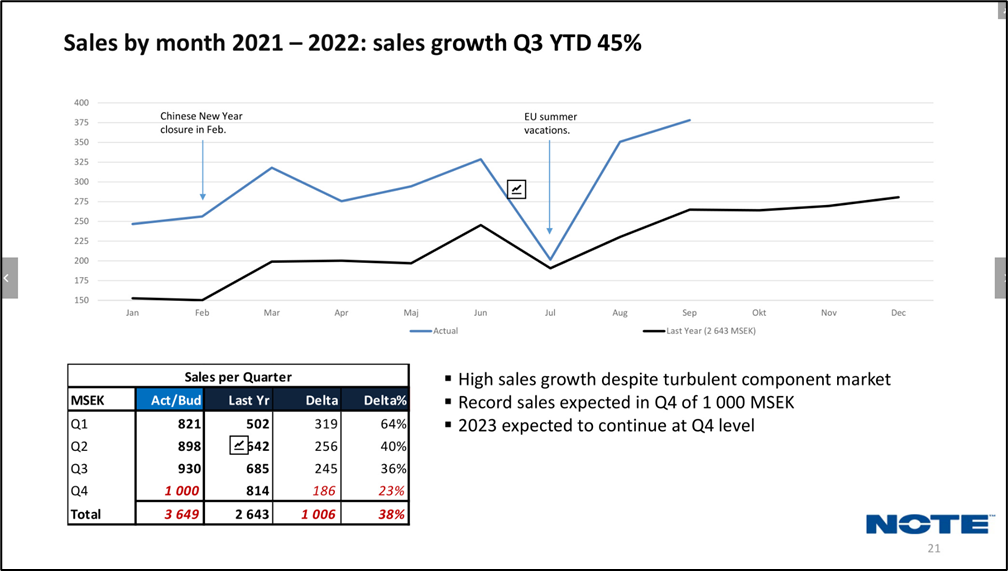
Uncertainties on the global market have quickly altered conditions in several sectors. We’re still seeing good opportunities to continue our positive progress. We have very strong order levels, with a range of exciting customers and projects in start-up phases. With our current market situation, we see good potential to achieve quarterly sales of SEK 1 billion for the first time ever, equivalent to growth of some 25%. For the full year 2022, this translates to sales of SEK 3.65 billion. We’re well positioned to achieve our long-term targets for growth, profitability and sustainability.
The M&A pipeline is said to be good.
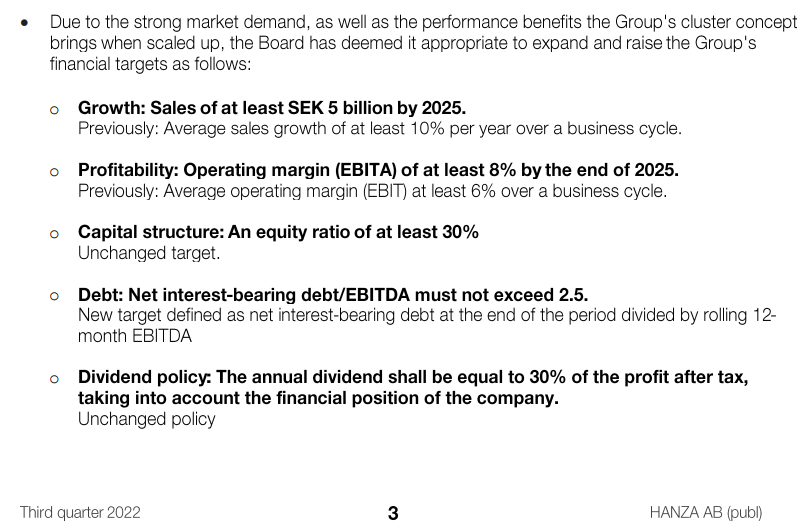
NOTE’s financial targets for 2025 are as follows:
- SEK 5 billion in revenue (2021: SEK 2.643 billion and in 2022 for three quarters SEK 2.649 billion)
- 10% EBIT margin
- at least 30% equity ratio
Regarding these targets, the CEO mentioned that there is supposedly some air in the revenue target and it can be reached through organic growth alone, even if there were some headwinds from the market. Quite a relaxed statement to make.
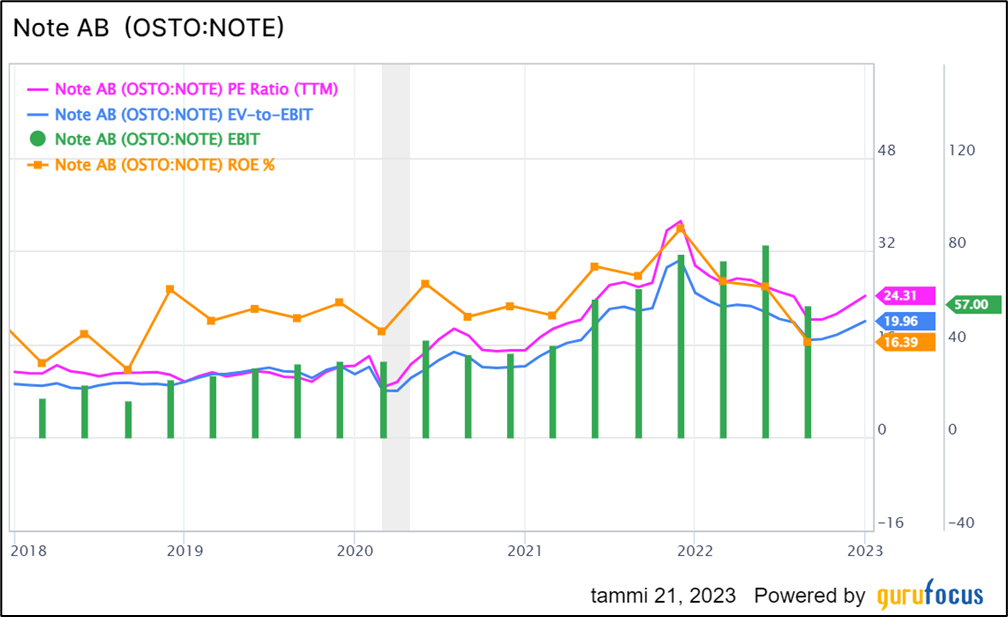
Valuations (figures taken directly from GuruFocus, so I won’t stake my life on them) for EMS players in general have been slightly elevated in recent years, but given the strong trend, this is entirely justified. In absolute terms, the multiples are not impossible if the promised growth continues.
From memory, the forward P/E for 2025 would be somewhere around 12 if those financial targets are met. For Incap, the figures are quite similar, and if I recall correctly, for Kitron as well. Personally, I would say that if Incap’s customer base were more diversified, it would deserve higher multiples than NOTE. It has delivered such massive organic growth and stellar profitability compared to other EMS players.
The 2022 financial statements and Q4/2022 earnings will be published right away next Monday, January 30, 2023, so we are in for an exciting time, even though we got a fairly comprehensive information package on the current situation at the CMD a month ago.
I don’t own any, and I haven’t done a detailed valuation yet. But here is a humanist analysis to kick off the discussion.
https://twitter.com/Salkku_Mauri/status/1616754258845773831?s=20