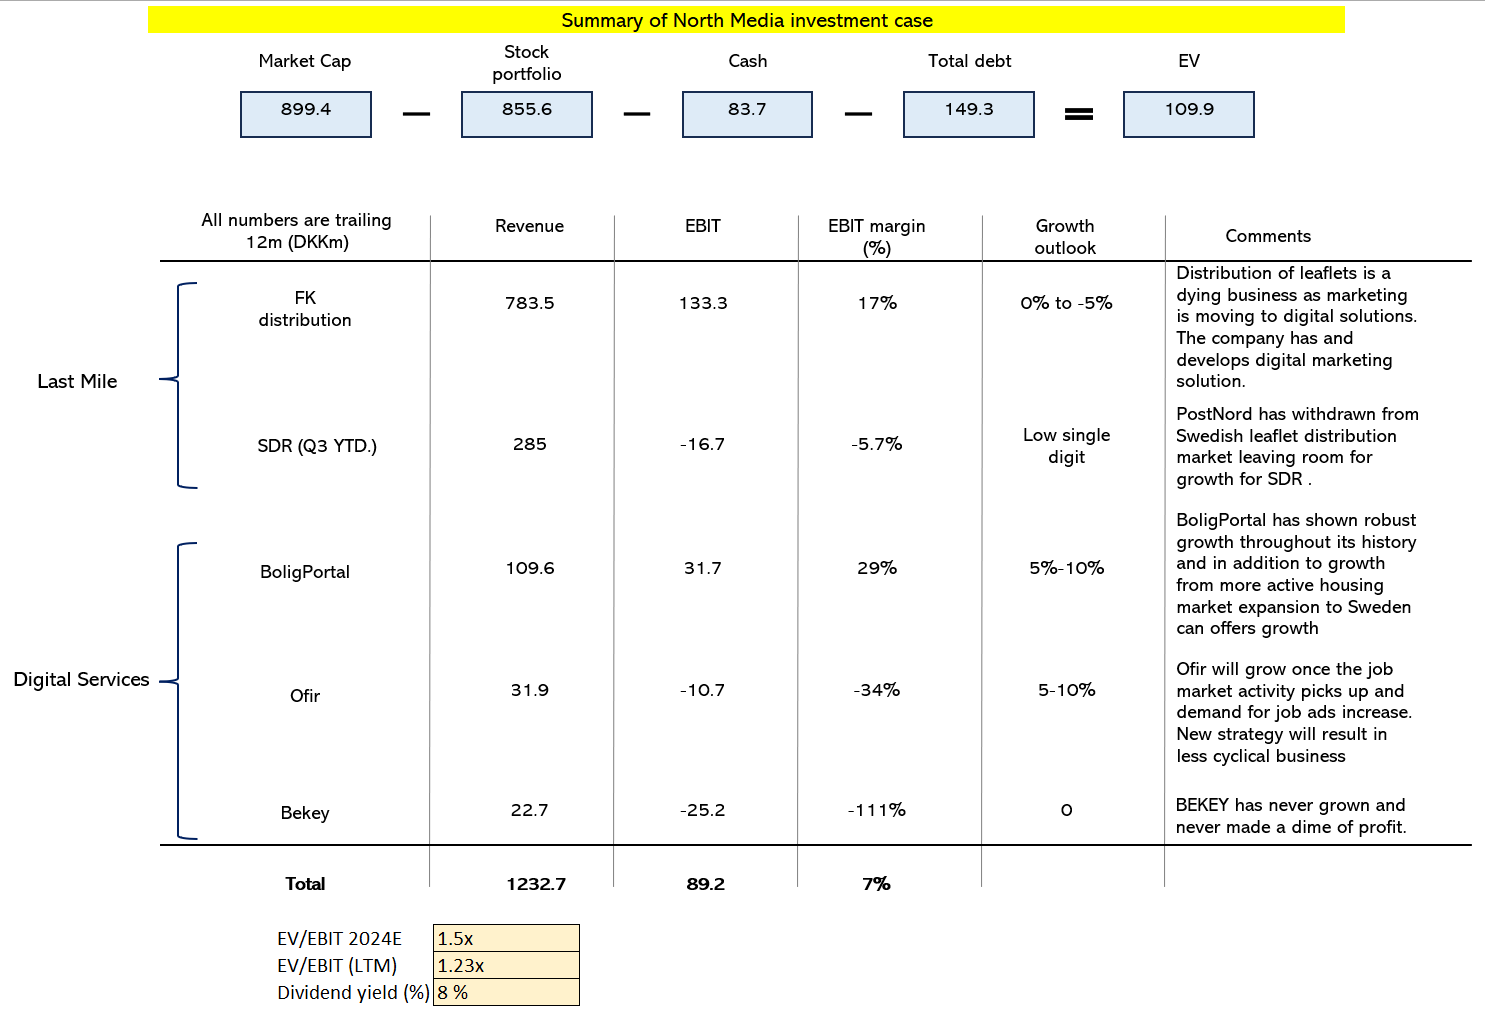
North Media A/S is a relatively interesting value stock from Denmark. I have been following the company since 2020 and finally added it to my portfolio this December at a price of 58.3. I didn’t buy it right now out of any extraordinary wisdom, but rather because I didn’t really have the cash available for this fellow in my portfolio before. 
In this post, I will try to roughly outline what the company does and how its various business segments have performed in recent years. I will also review the overall performance of the group over the past few years and finally weigh this against the company’s price tag. I recommend reading the annual reports and quarterly reports for 2020 and 2021. They clearly lay out forecasts and guidance, strategic goals, and updates for each business. The purpose of this introduction is solely to bring the company to light, not to offer any deep analysis of it.
What does the company do?
The company has two business segments: Last Mile & Digital Services, with the latter further divided into three different business units.
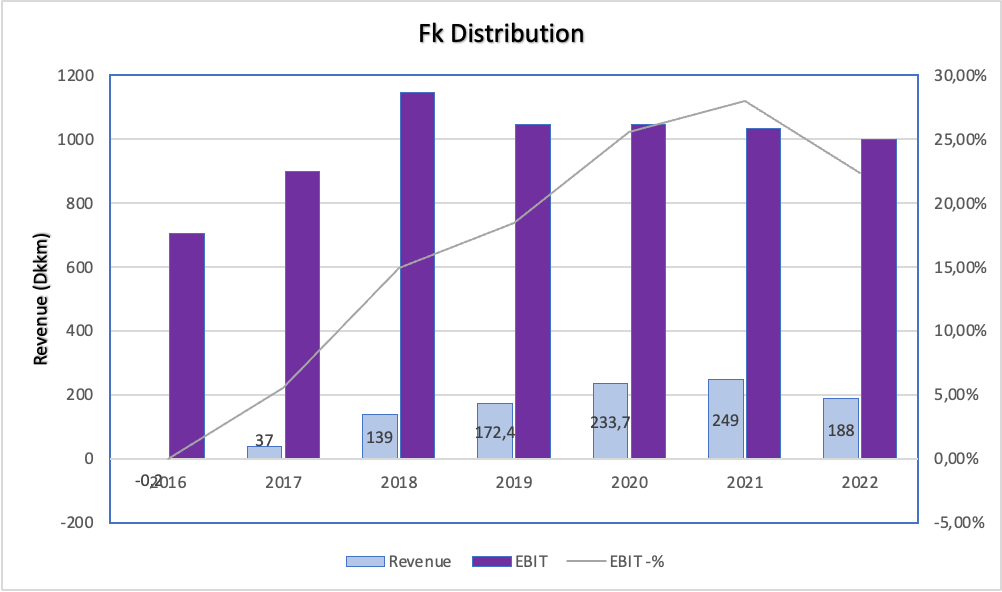
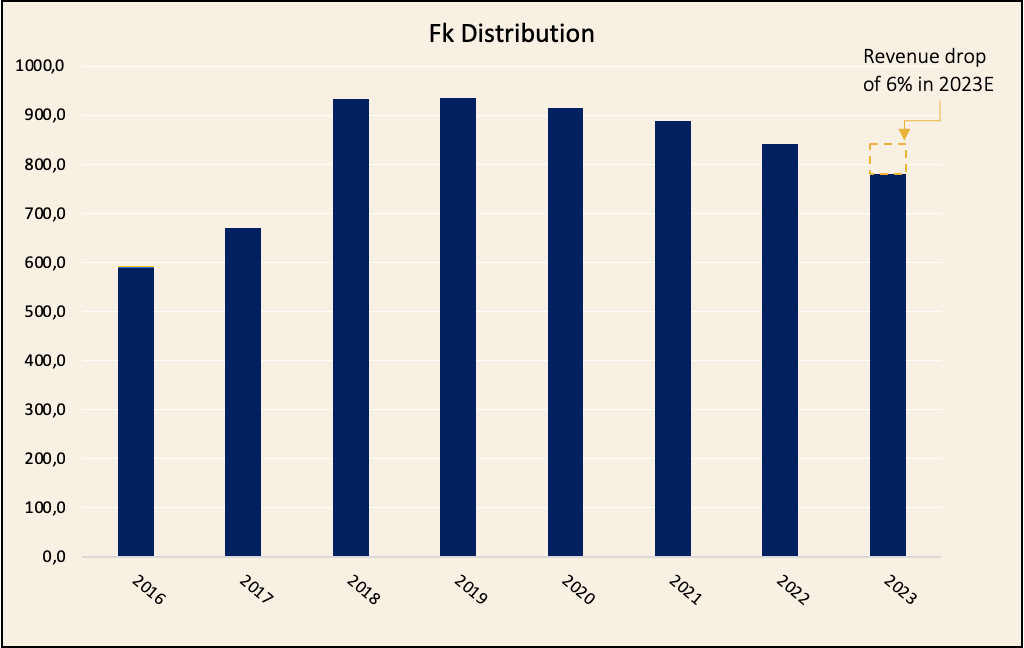
Last Mile - Fk Distribution
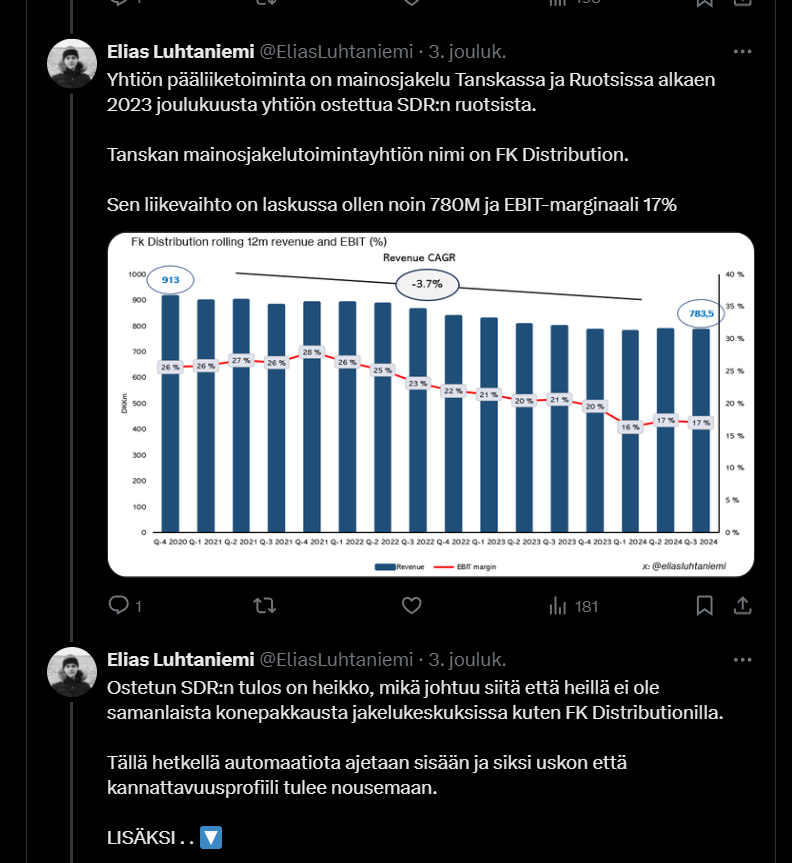
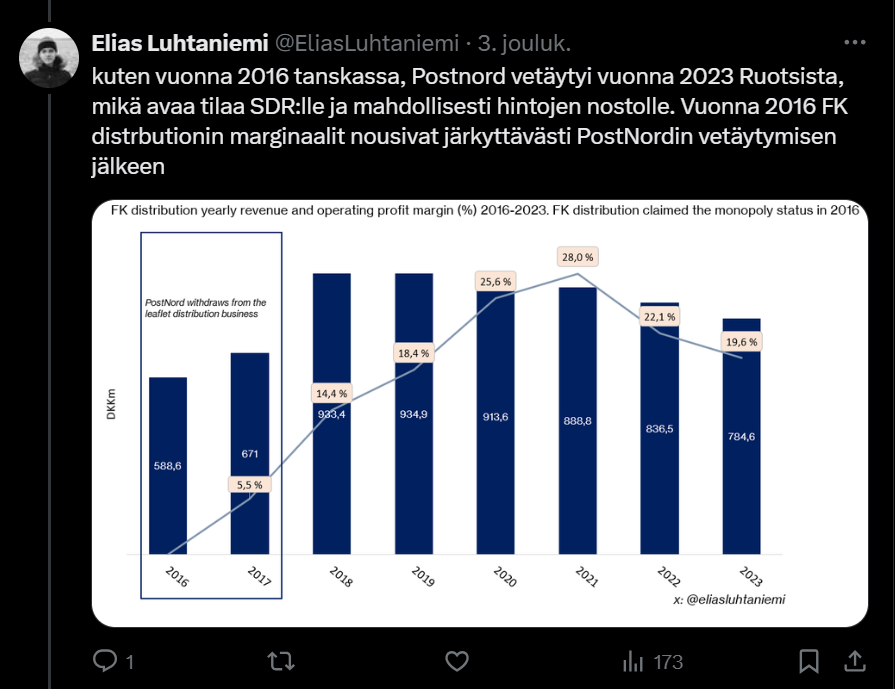
Last Mile accounts for about 85% of the company’s revenue and consists solely of the Fk Distribution business unit. In practice, this involves delivering advertisements and local newspapers to households across Denmark. Additionally, the company operates a digital platform, minetilbud.dk, where people can, among other things, choose which ads they wish to receive at home. Last Mile also offers packaging services to Danish customers and Deutsche Post. This cooperation with Deutsche Post is intended to be continuously expanded. The company is the largest player in its home country, and its position here has strengthened significantly since 2017, when PostNord withdrew from the market as its main competitor.
Figures:
- Local newspapers are delivered weekly to 2.3 million households
- 525,000 people use the NoTak+ feature to customize which ads they receive
- 1.4 million people receive all papers and advertisements
MinetilBud:
- 1,000,000 users
- 500,000 active users, meaning 30 minutes on the site per month
- 104,000,000 digital flyers read in 2021
- Minetilbud’s revenue dropped from 2020 to 2021, likely from 35M DKK to 25M DKK
From 2017 onwards, it started printing money as PostNord withdrew from the market, allowing the company to gain customers and raise prices.
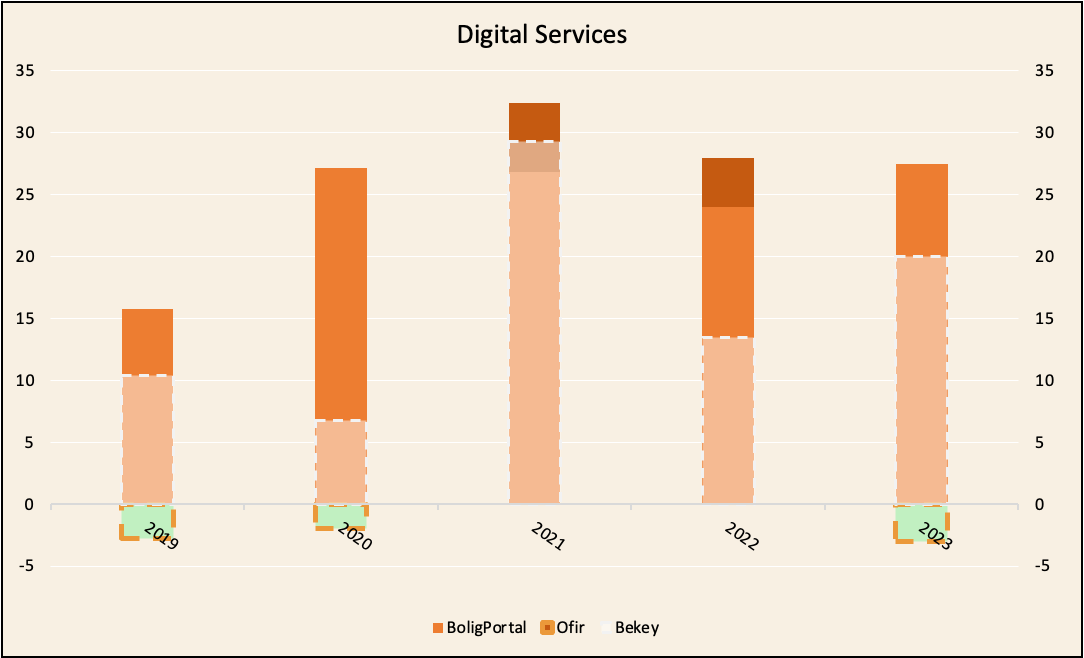
Digital Services
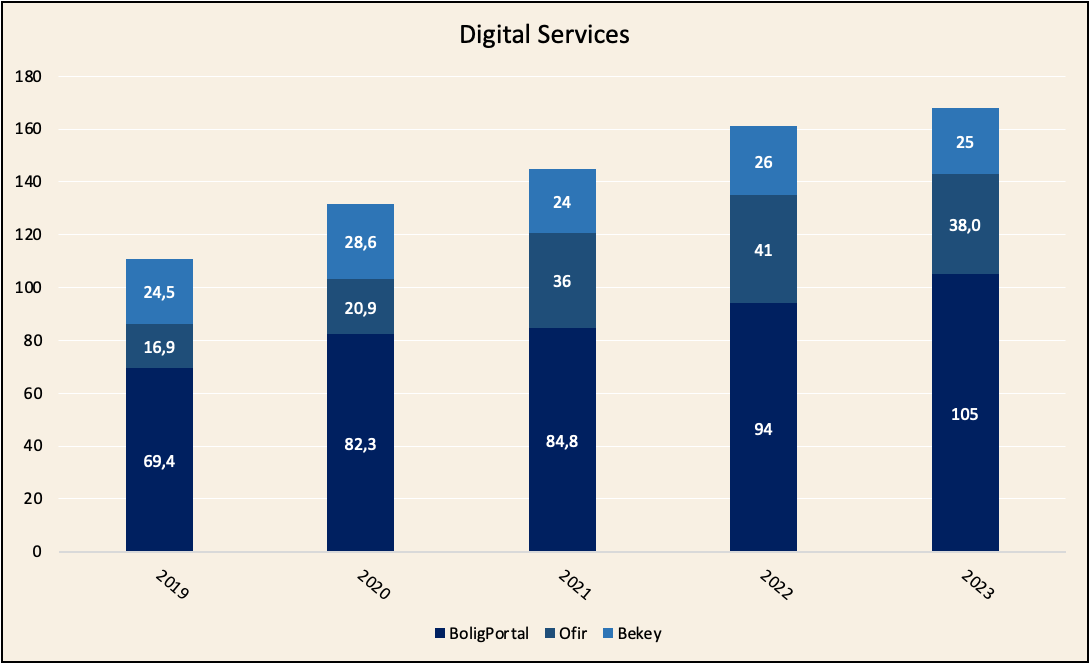
This second business unit consists of three different businesses: BoligPortal, Ofir, and Bekey. In practice, these represent the company’s future, because relying solely on ad distribution carries the risk of the entire business being banned, given that printing paper and then delivering it straight to household trash cans is neither very ESG-friendly nor modern
BoligPortal
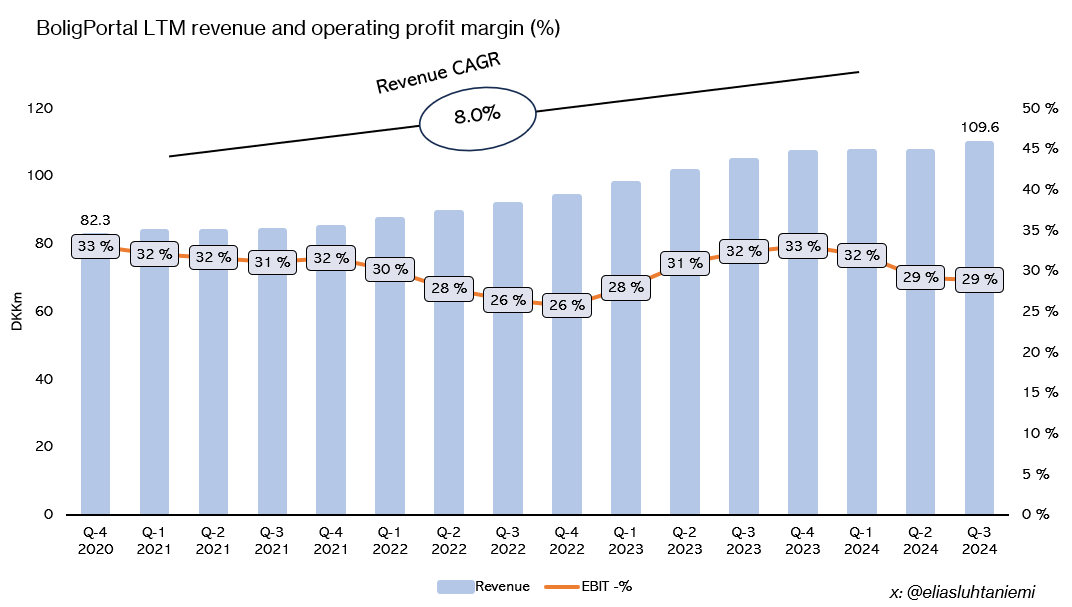
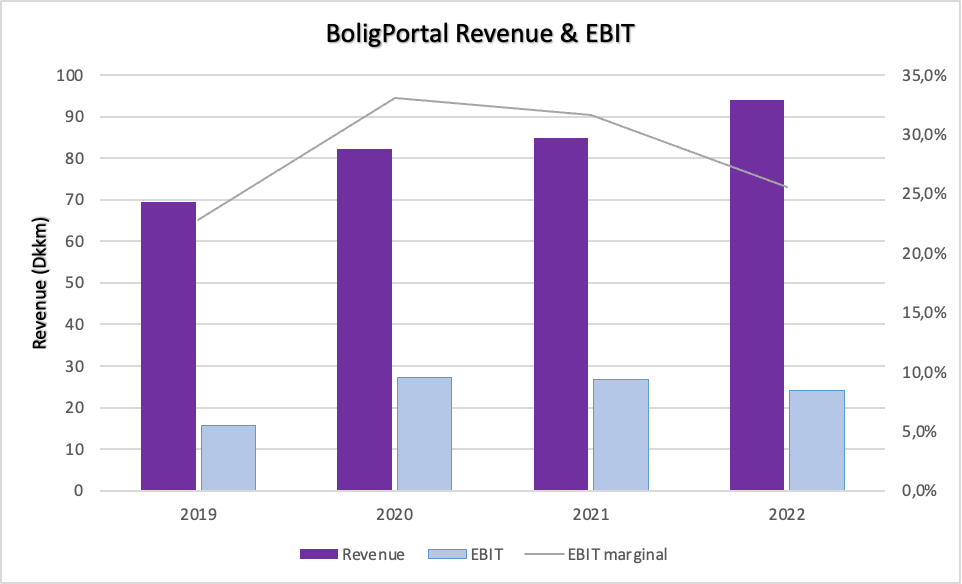
BoligPortal is the largest business in the “Digital Services” segment and it is Denmark’s largest rental housing portal. This is where landlords find tenants, comparable to Oikotie.fi in Finland. BoligPortal has also launched in Sweden on the same platform under the name BostadsPortal.se. In February 2022, BoligPortal acquired a company called Boligmanager: https://www.northmedia.dk/en/meddelse/?storyID=15317330
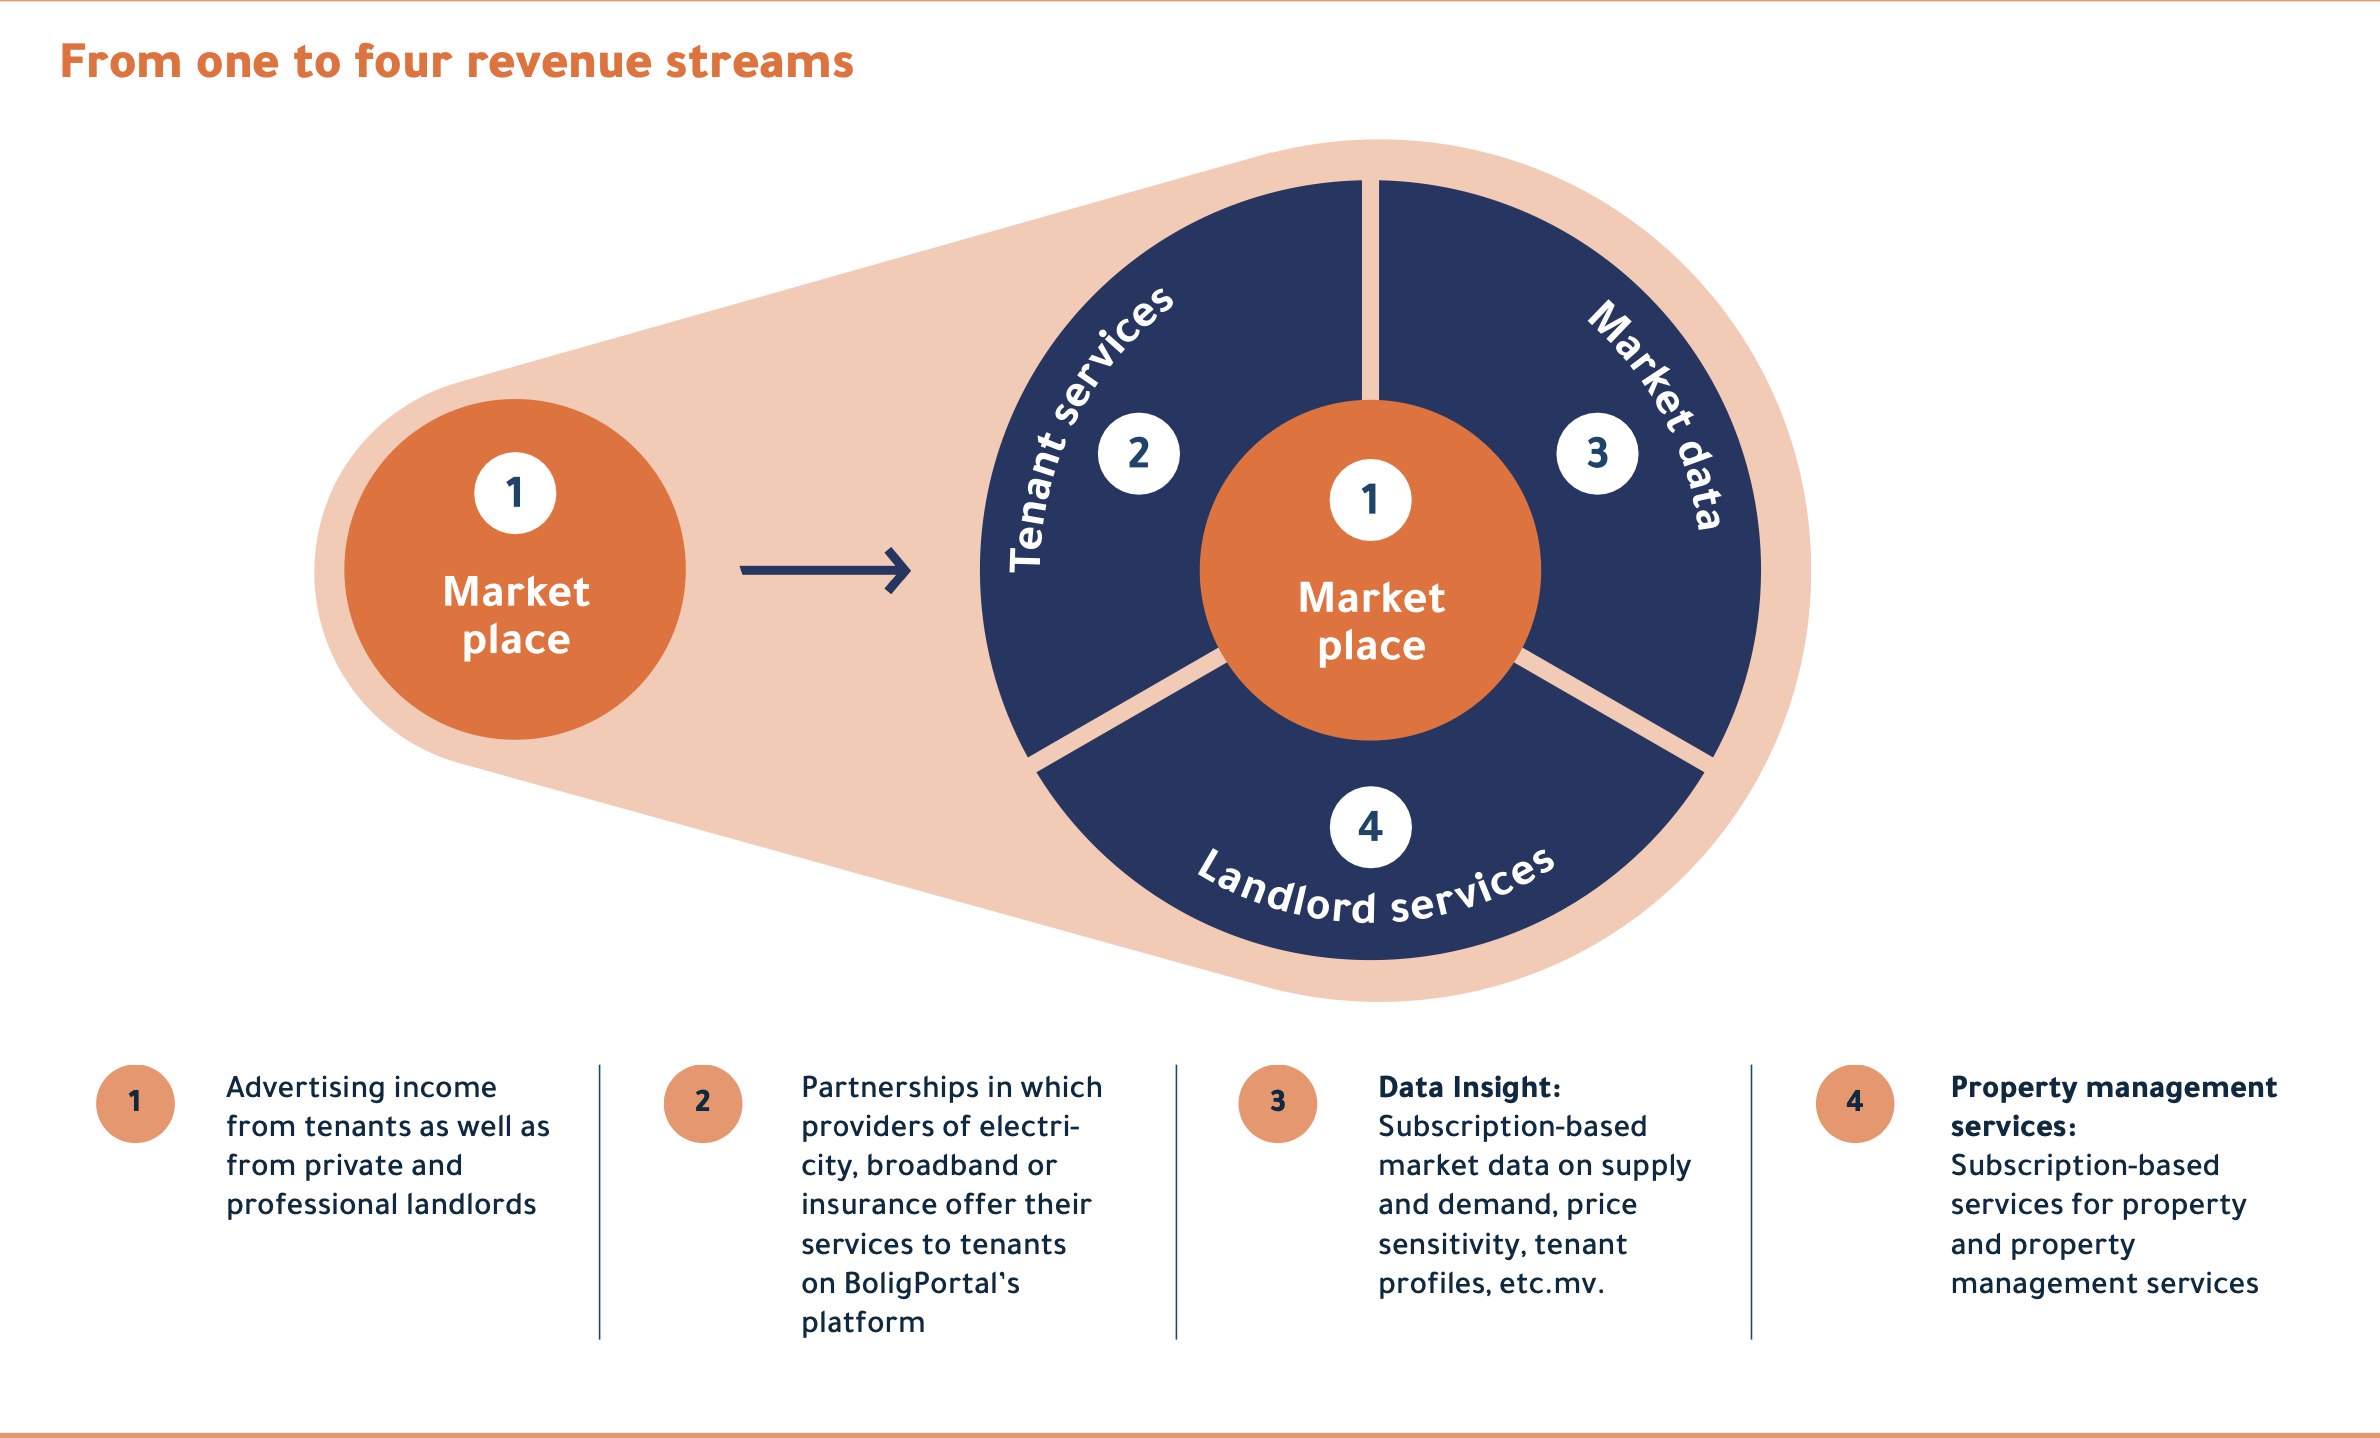
The company aims to expand its revenue streams (subscription-based) through at least the following ways:
- Selling data on supply and demand in specific areas and streets to real estate companies, banks, investors, and contractors.
- Offering small and medium-sized landlords solutions for managing property portfolios or real estate, which include advertising and market data sharing.
- Aiming to sell third-party electricity contracts, subscriptions, and home insurance to tenants via the platform, earning a commission for NM.
BoligManager, acquired in February, is software that allows landlords to manage everything related to renting out apartments. Read more here:
https://www.northmedia.dk/en/meddelse/?storyID=15317330
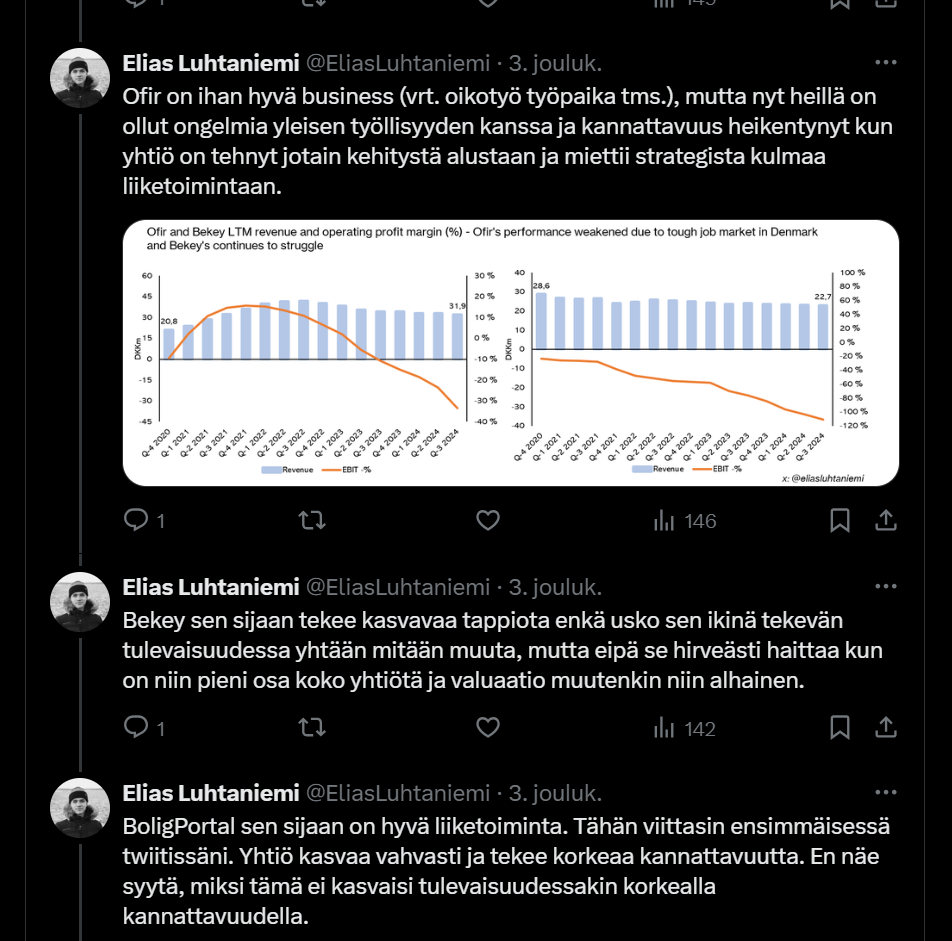
BoligPortal has been a quite decent business for NM.
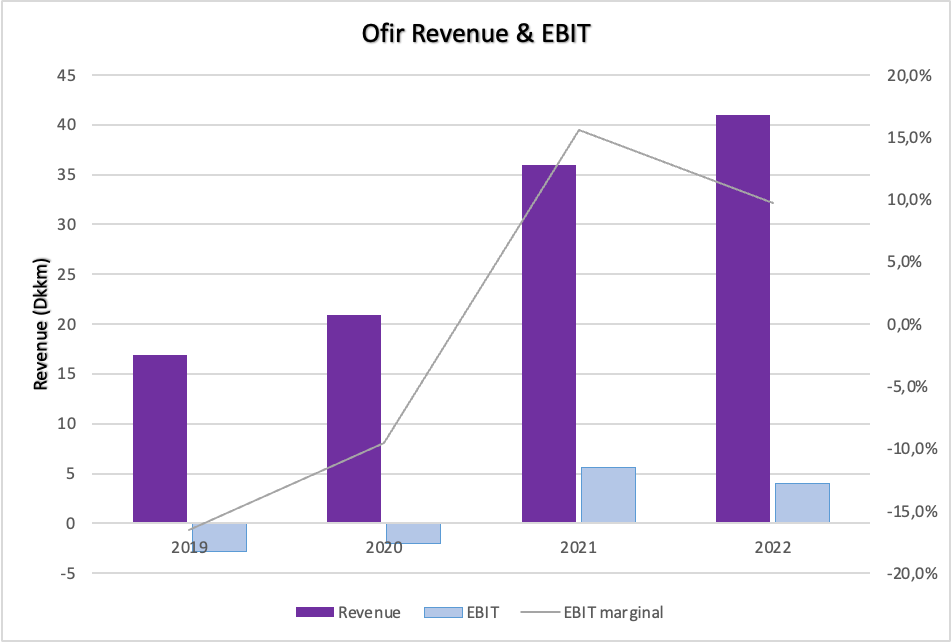
Ofir
Ofir is the second-largest business on the “Digital Services” side. The business’s moneymaker is connecting job seekers and employers. This is Denmark’s second-largest job portal. Ofir was the first to start advertising job openings online and on social media (Facebook, LinkedIn & Instagram).
Figures:
- 400,000 visitors per month
- 32,600 job ads in 2020
- Cooperation with 900 private and public sector employers in 2020
History:
Bekey
Last and least, Bekey is the smallest in terms of revenue, but the largest in operating loss . Bekey provides a digital solution for opening doors—a platform where, for example, apartment building residents are granted access using this platform. The solution eliminates physical keys, allows blocking a specific person’s access to the building without changing locks, and provides an audit trail of all movement within the properties.In 2021, 114 million doors (14.4 million according to the annual report) were opened using Bekey’s solution. In addition to residents, the solution is used by, among others, home care services in Danish and Norwegian municipalities (every third municipality in Denmark uses it), grocery and meal box delivery companies, real estate agents, property managers, etc.
This sounds like a good solution, but the business has faced challenges, at least when looking at the figures:
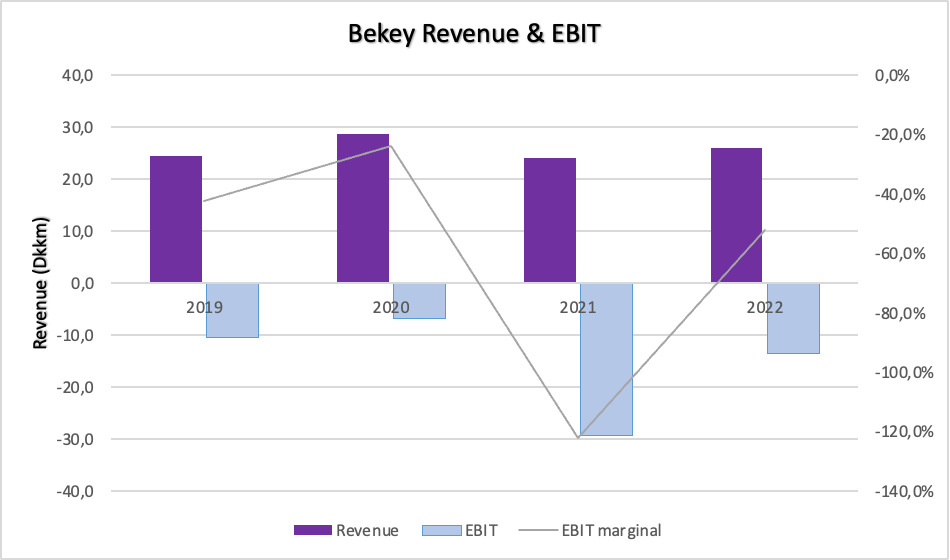
In 2021, a 20m DKK writedown was made, which further strained the earnings.
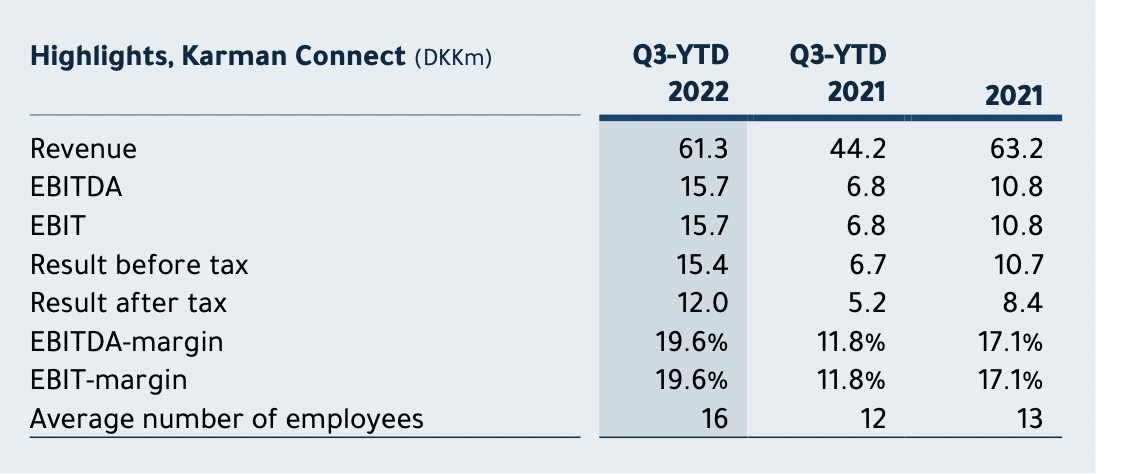
In addition to these, the company owns 50% of a company called Karman Connect. You can read more about this in the Q3 report, for example. Here are the figures from the Q3 report:
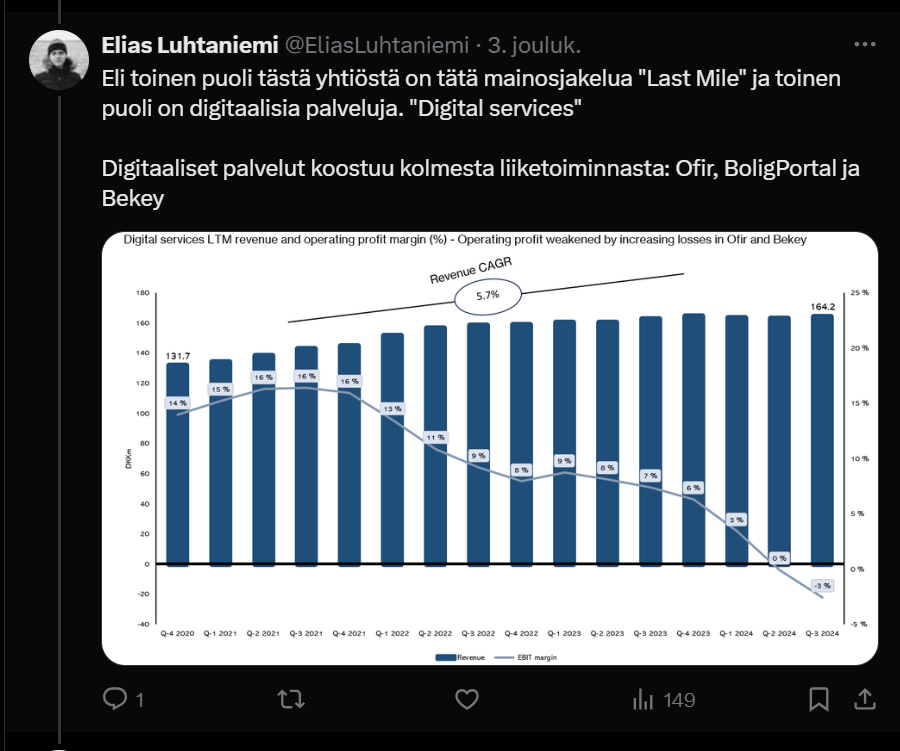
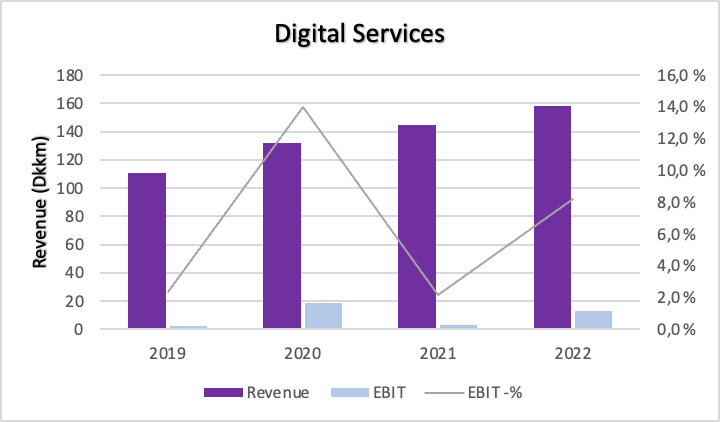
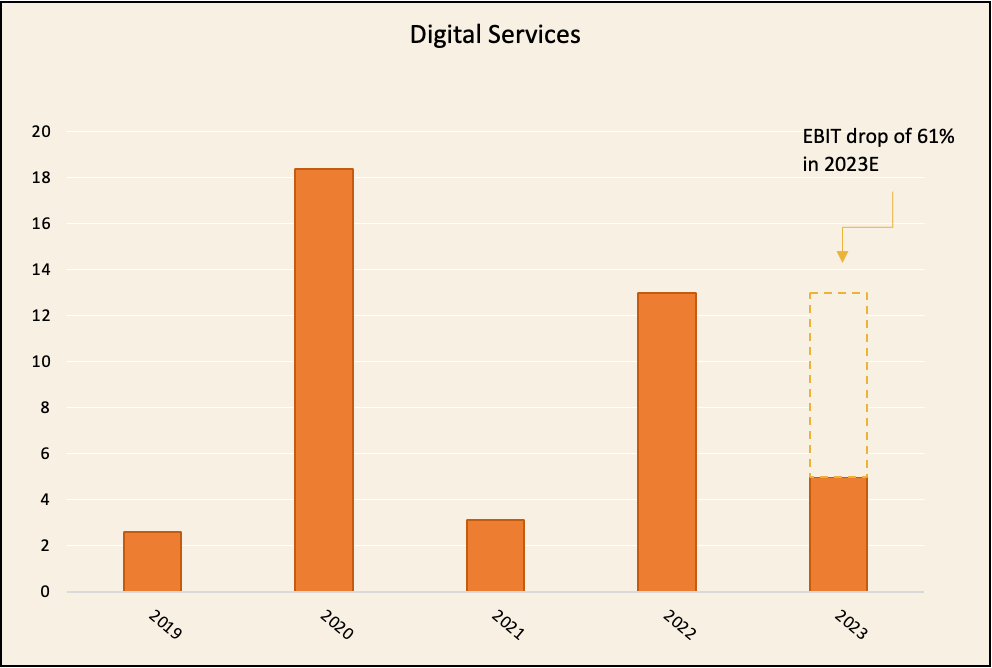
Digital Services as a whole:
Here is all the information compactly from the company itself:
https://www.northmedia.dk/en/forretningsomraader/
That was a very rough overview of what the company does. History for the “Digital Services” division only goes back to 2019, because it wasn’t until 2020 that the current model was implemented, where the business is divided into these two areas.
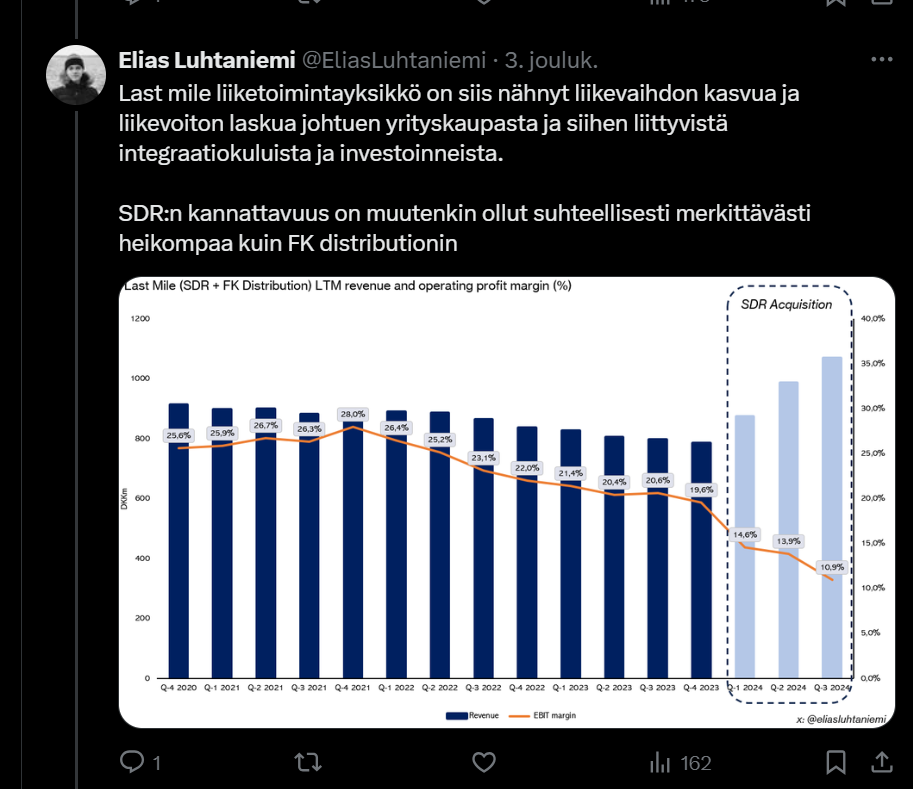
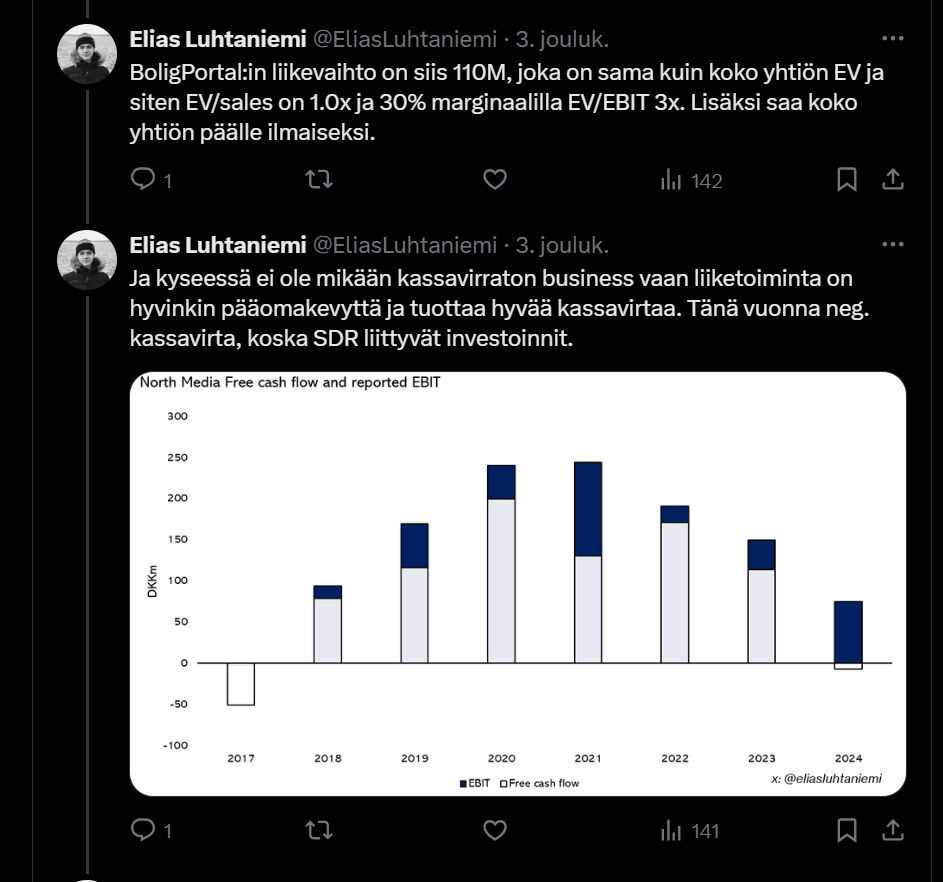
Here is the development of the entire group: This year, EBIT is expected to be around 200 and cash flow for Q3 YTD was approximately 114.
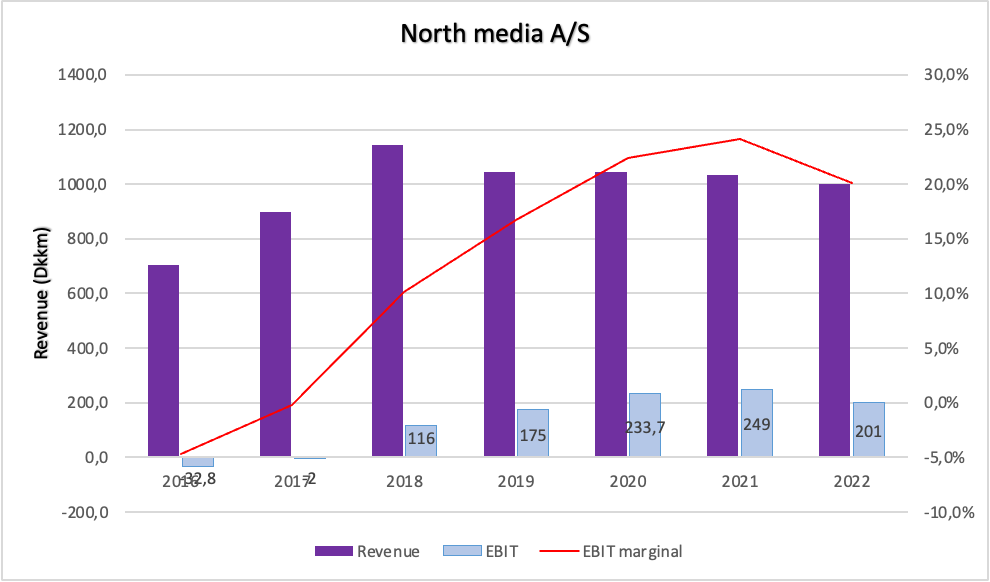
So, the company is practically just the Last Mile segment, which mainly delivers advertisements and newspapers. This carries the risk that regulation could be introduced regarding the printing and consequently the distribution of paper advertisements, which could cause the entire business to drop to almost zero.
On the Digital Services side, there seems to be a good vibe, and innovation, data, and technology are emphasized multiple times. However, we must remember that today it accounts for only about 15% of the company’s total revenue.
The company has grown its earnings significantly over the last 5 years, which raises the question of how much capital had to be tied up in the process. Here is the development from recent years: calculated (NOPAT/IC) (excl. goodwill 39Mdkk)
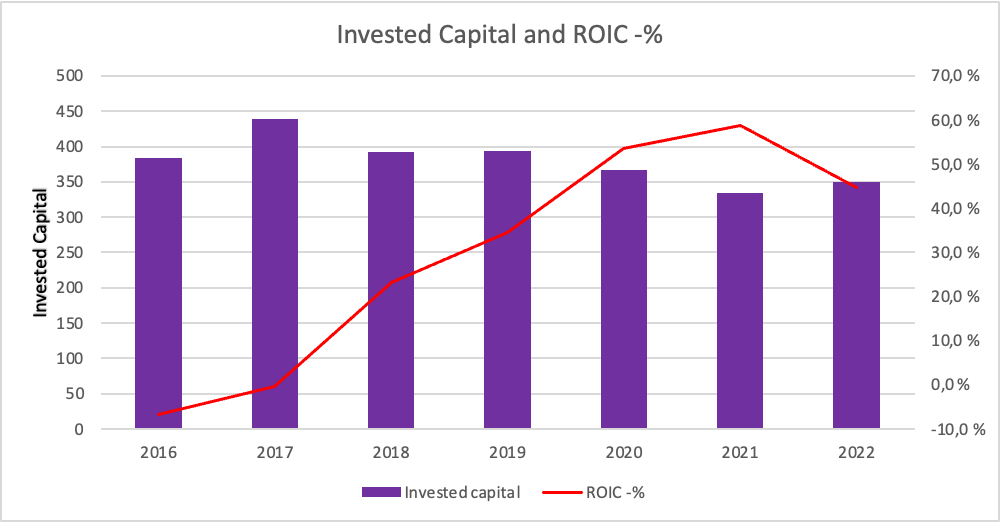
I have gathered some figures based on Q3 and 2022 forecasts. NM updates its forecasts every quarter, so the 2022E figures are quite likely close to the actual value:
And then comes the question we Finns ask on a holiday in the Canaries: “How much?”
| 30.9.2022 | Company | North Media A/S (XCSE:NORTHM) | ||||||
|---|---|---|---|---|---|---|---|---|
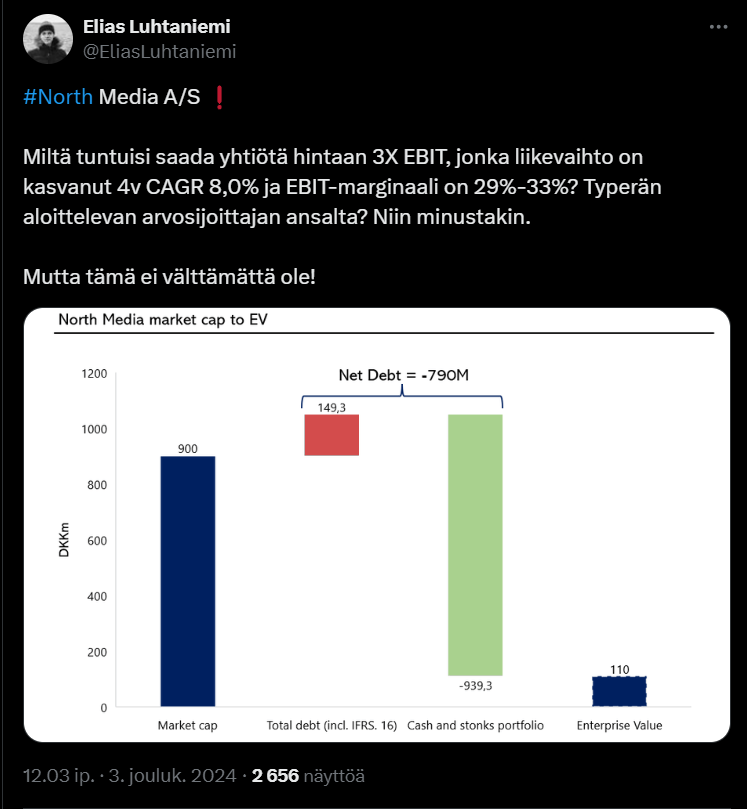
| Mcap (mDkk) @ 56,5dkk | 1.050 kr | |||||||
| Total Debt | 115 | |||||||
| Liquid assets (Cash & stonks) | 676,5 | |||||||
| EV | 489 kr | |||||||
| Book Value | 920,8 | |||||||
| EV/EBIT (2022E) | 2,5 | |||||||
| EV/FCF (2022E) | 3,3 | |||||||
| P/FCF (2022E) | 7,0 | |||||||
| P/B | 1,14 | |||||||
| P/cash | 1,6 | |||||||
| Dividend/share | 5.0Dkk | \ | ||||||
| Dividend yield | 8,8% | \ |
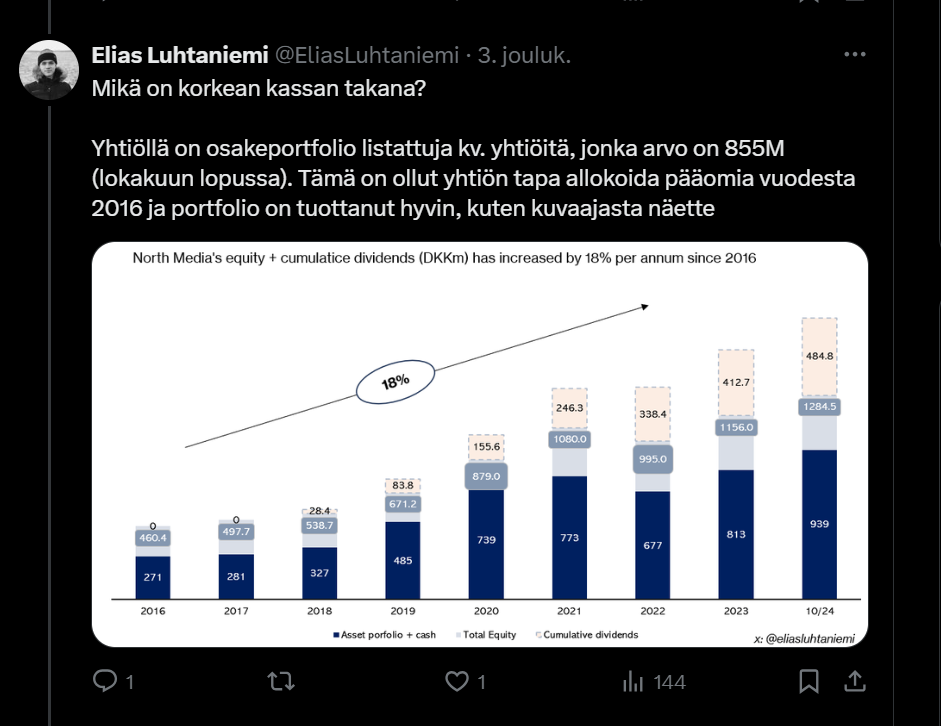
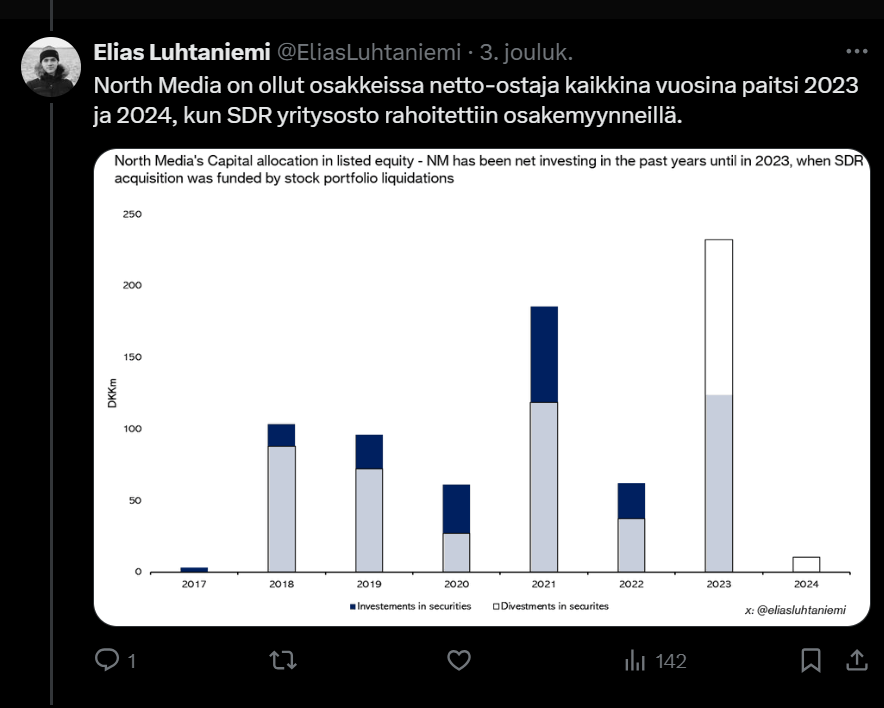
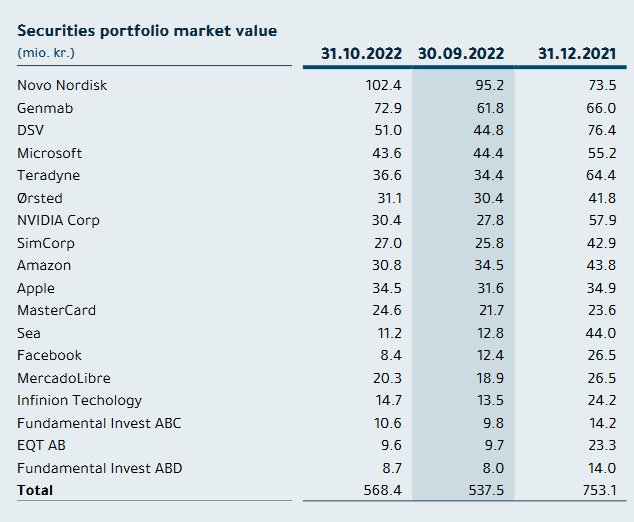
This seems relatively cheap, considering that the company is still producing excellent earnings and that the Book Value largely consists of liquid assets. The company has a habit of keeping an investment portfolio on its balance sheet, into which a portion of the profits is invested. Here is the development of that in relation to market value.
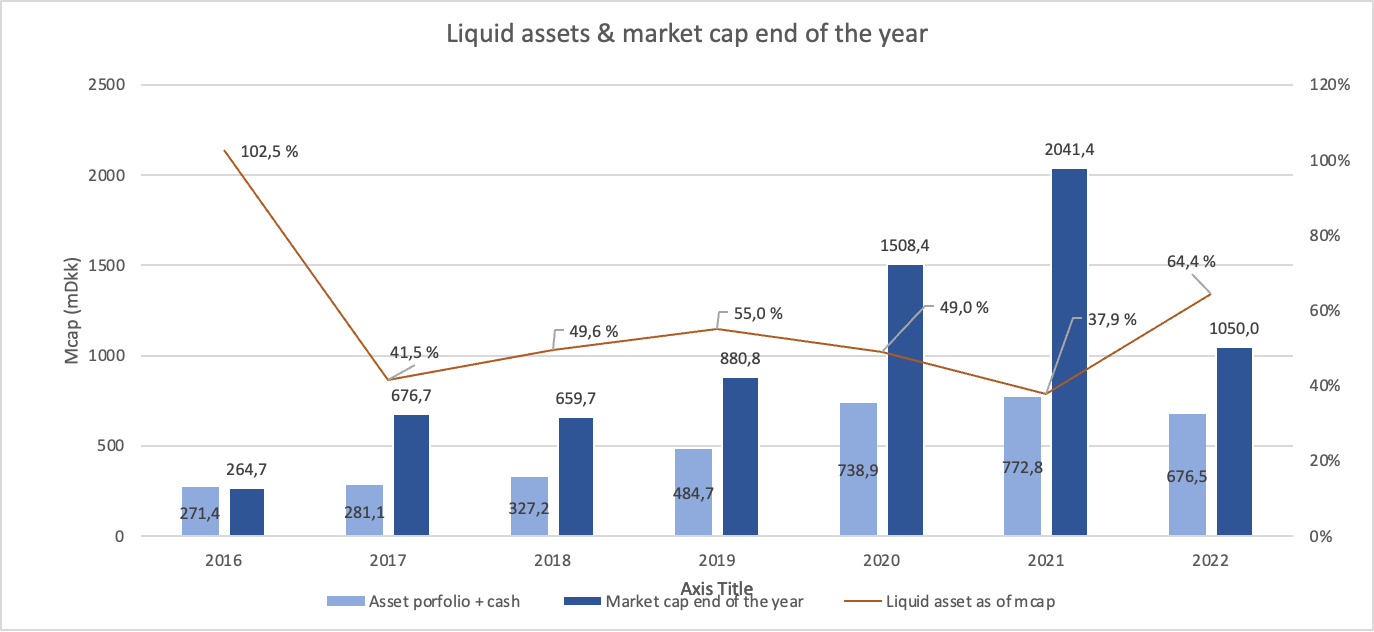
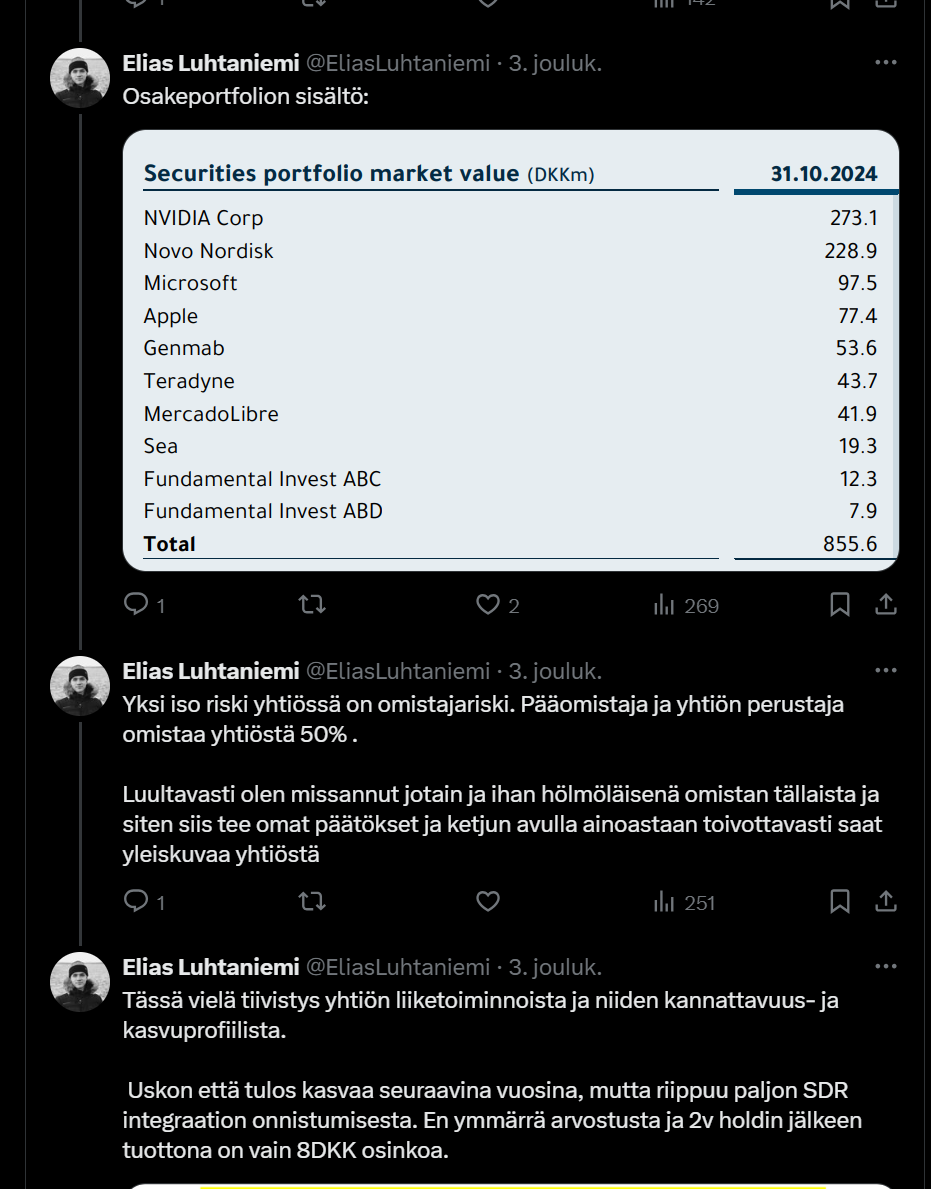
So far it has yielded well, but the future is unknown and the returns could be significantly worse. Contents of the portfolio:
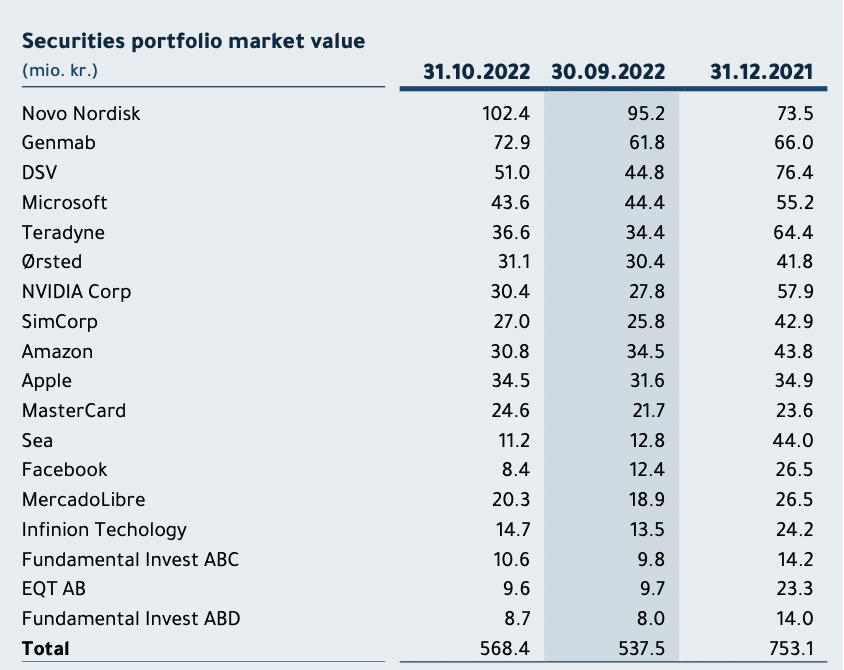
So here is a company that costs about 56.5 currency units, of which a net amount of about 30 units is cash and stonks. You are thus paying about 26.5 units for future cash flows, which in 2022 will generate about 8 units of free cash flow.
Why is the company valued so low?
Reasons could include, for example:
- The public believes that regulation for paper distribution is coming soon, e.g., next year, making the current valuation completely fine.
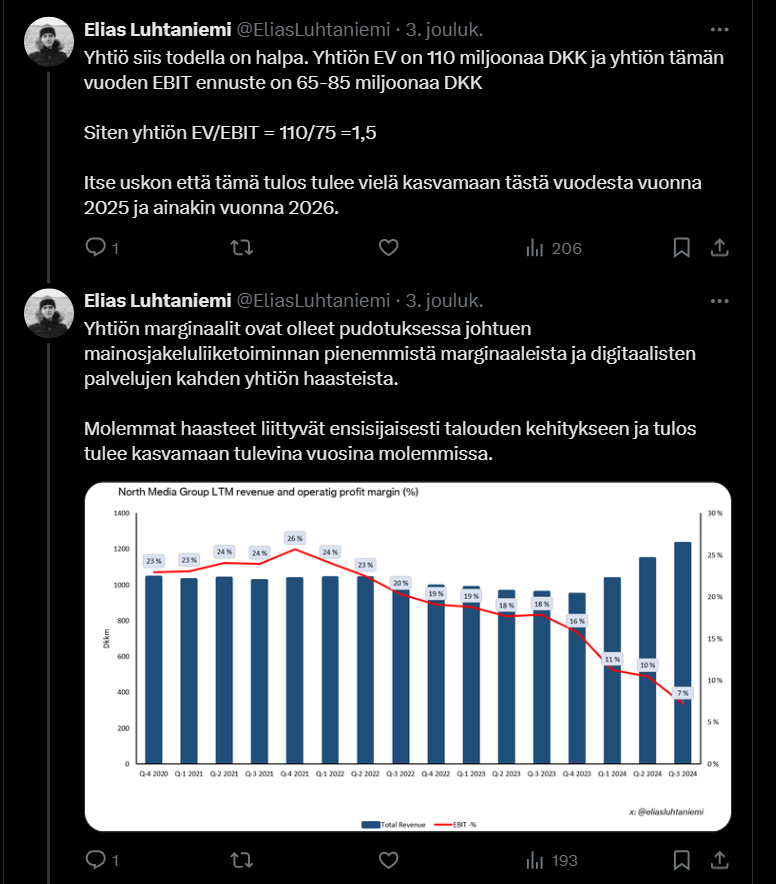
- Margins have been under pressure recently, so there is fear that they won’t be able to achieve that 20% going forward.
- One of the company’s ways of allocating capital by investing in listed companies is not appealing this year.
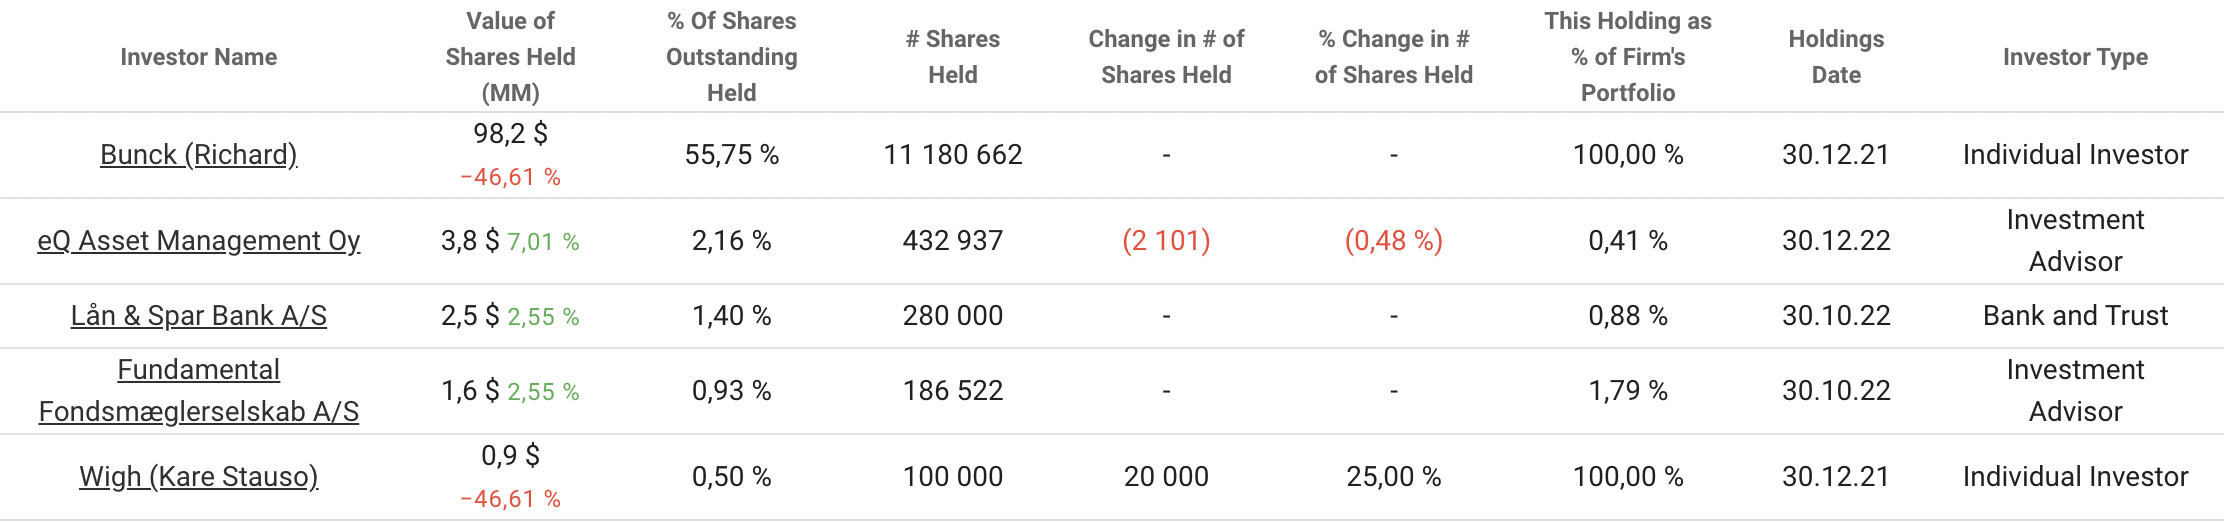
- The main shareholder owns 60% of the company.
- The post-covid stock surge and the subsequent decline have further accelerated the drop.
- Technical analysis (TA) enthusiasts will be spooked by the following chart:
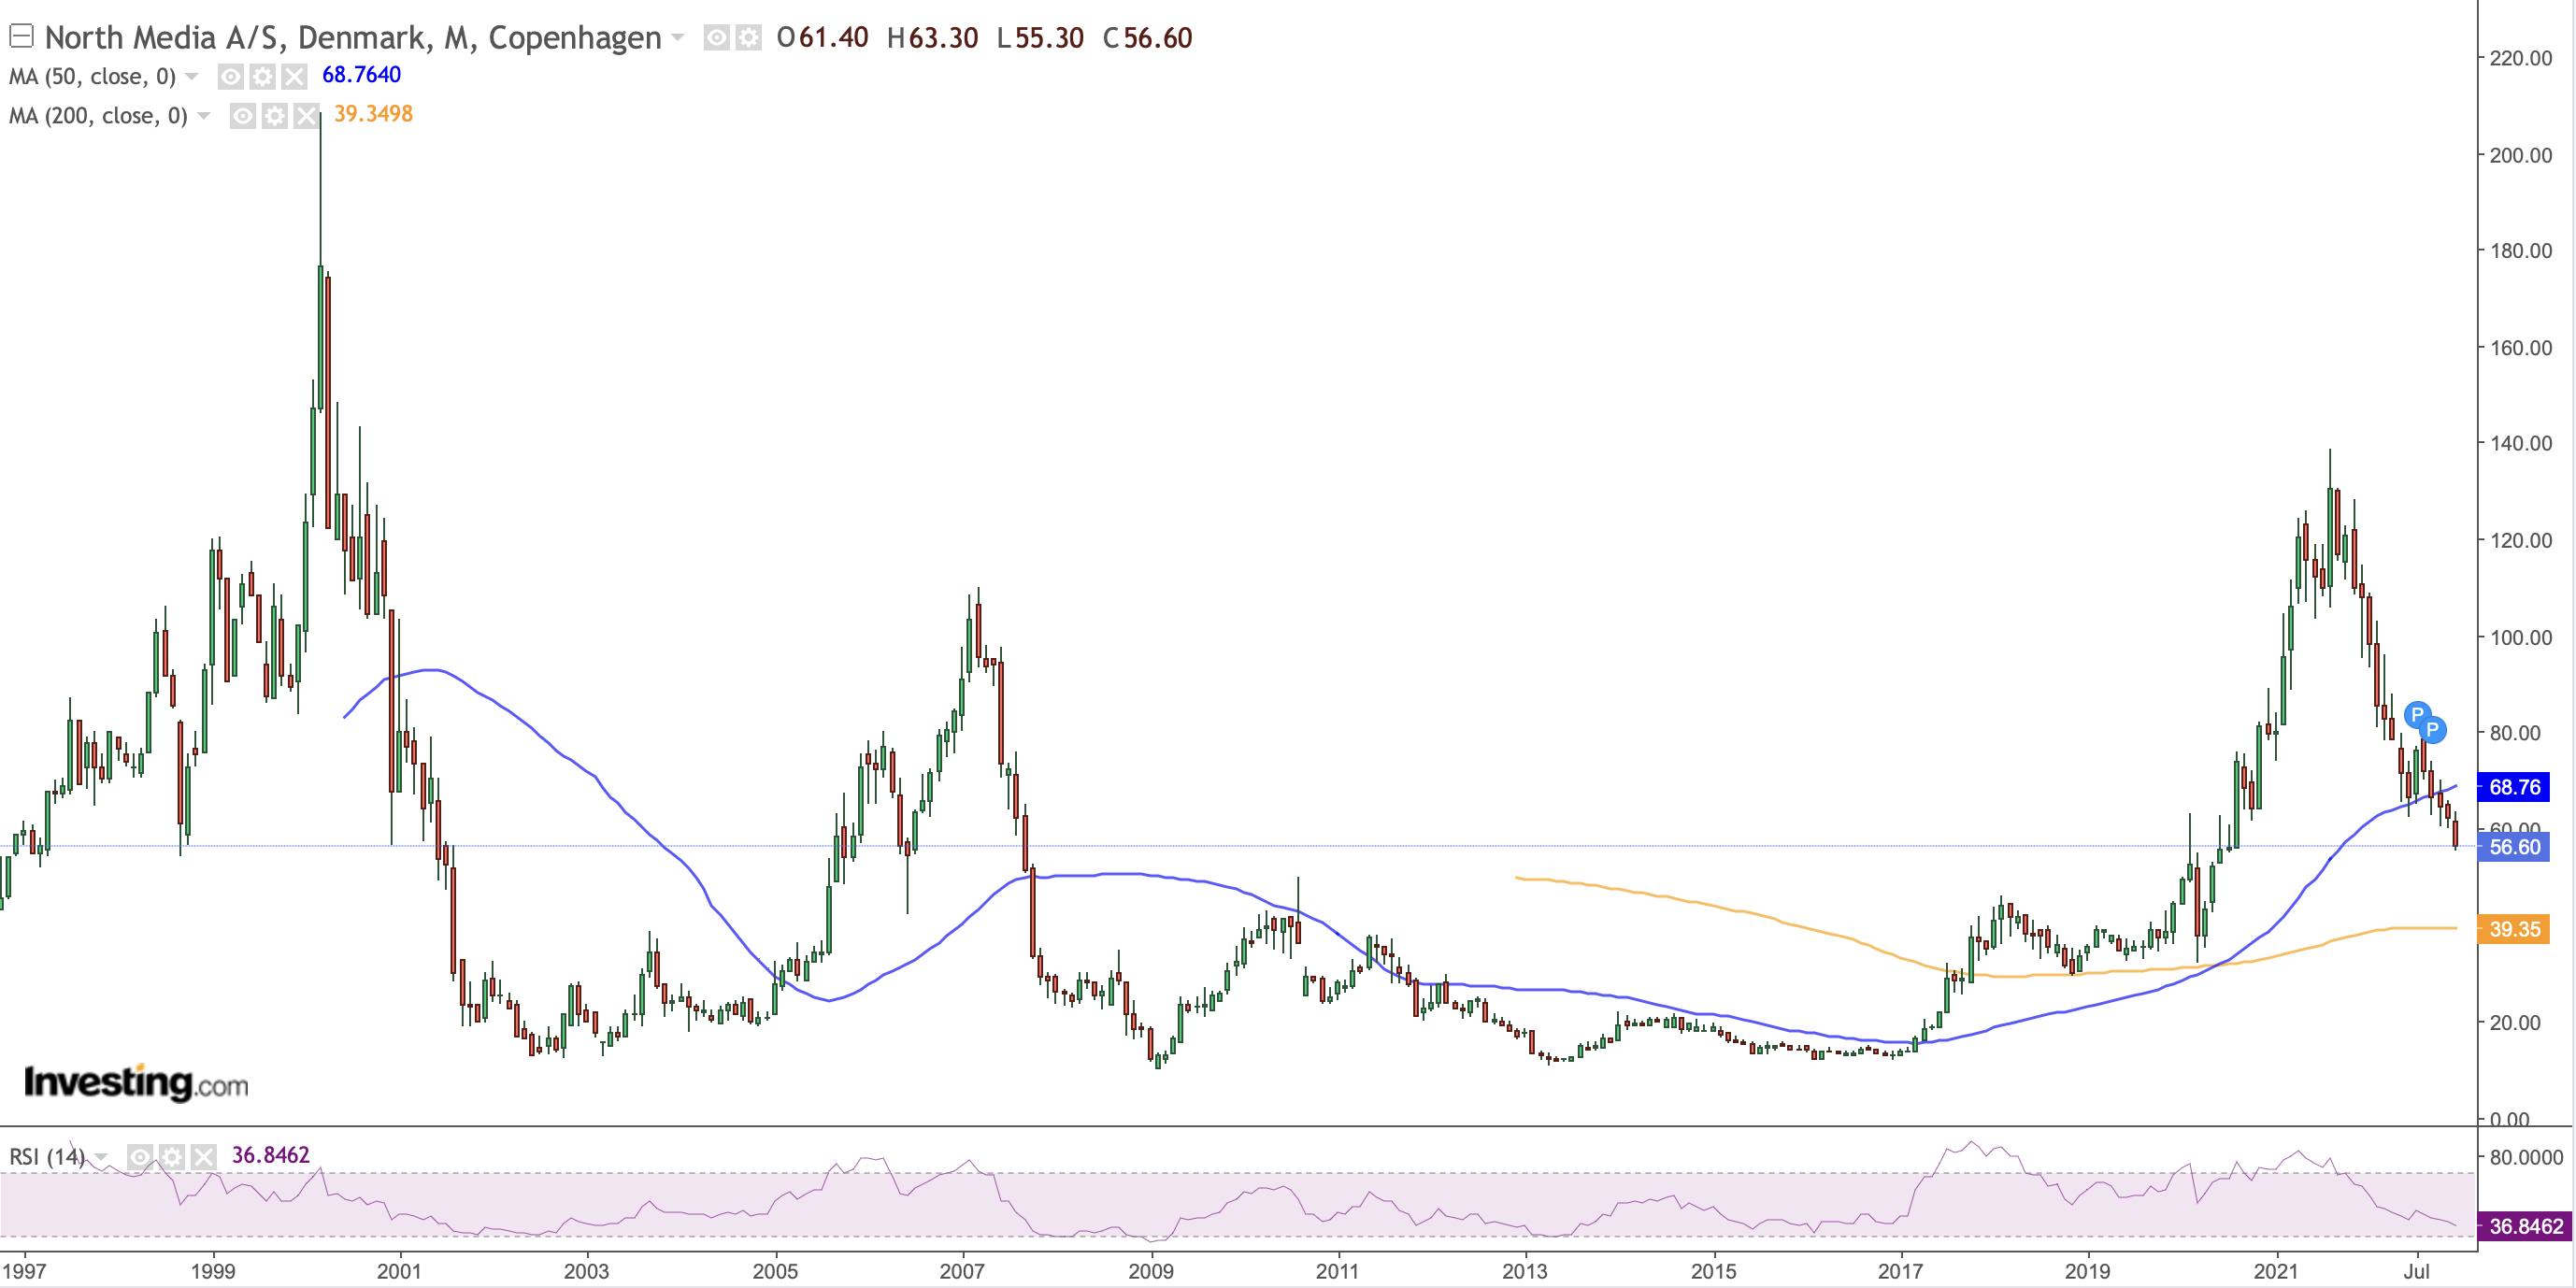
After the year 2000, it dropped down to the level of 11, and similarly after 2007. So this will likely happen this time as well
 This has been a fun find, especially since there is an exceptionally large amount of cash on the balance sheet. A major driver of the company’s value is how many years of cash flow we will get from Fk Distribution’s business. I can’t really say much about that myself, but I believe the cash flow will last longer than what is currently priced into the stock.
To reiterate: I recommend reading those annual reports and quarterly reports from 2020 and 2021. They very clearly outline the forecasts and guidance, strategic goals, and updates for each business.
Here is an analysis of an extreme case from ABG Sundal Collier: (found on the NM investor page)
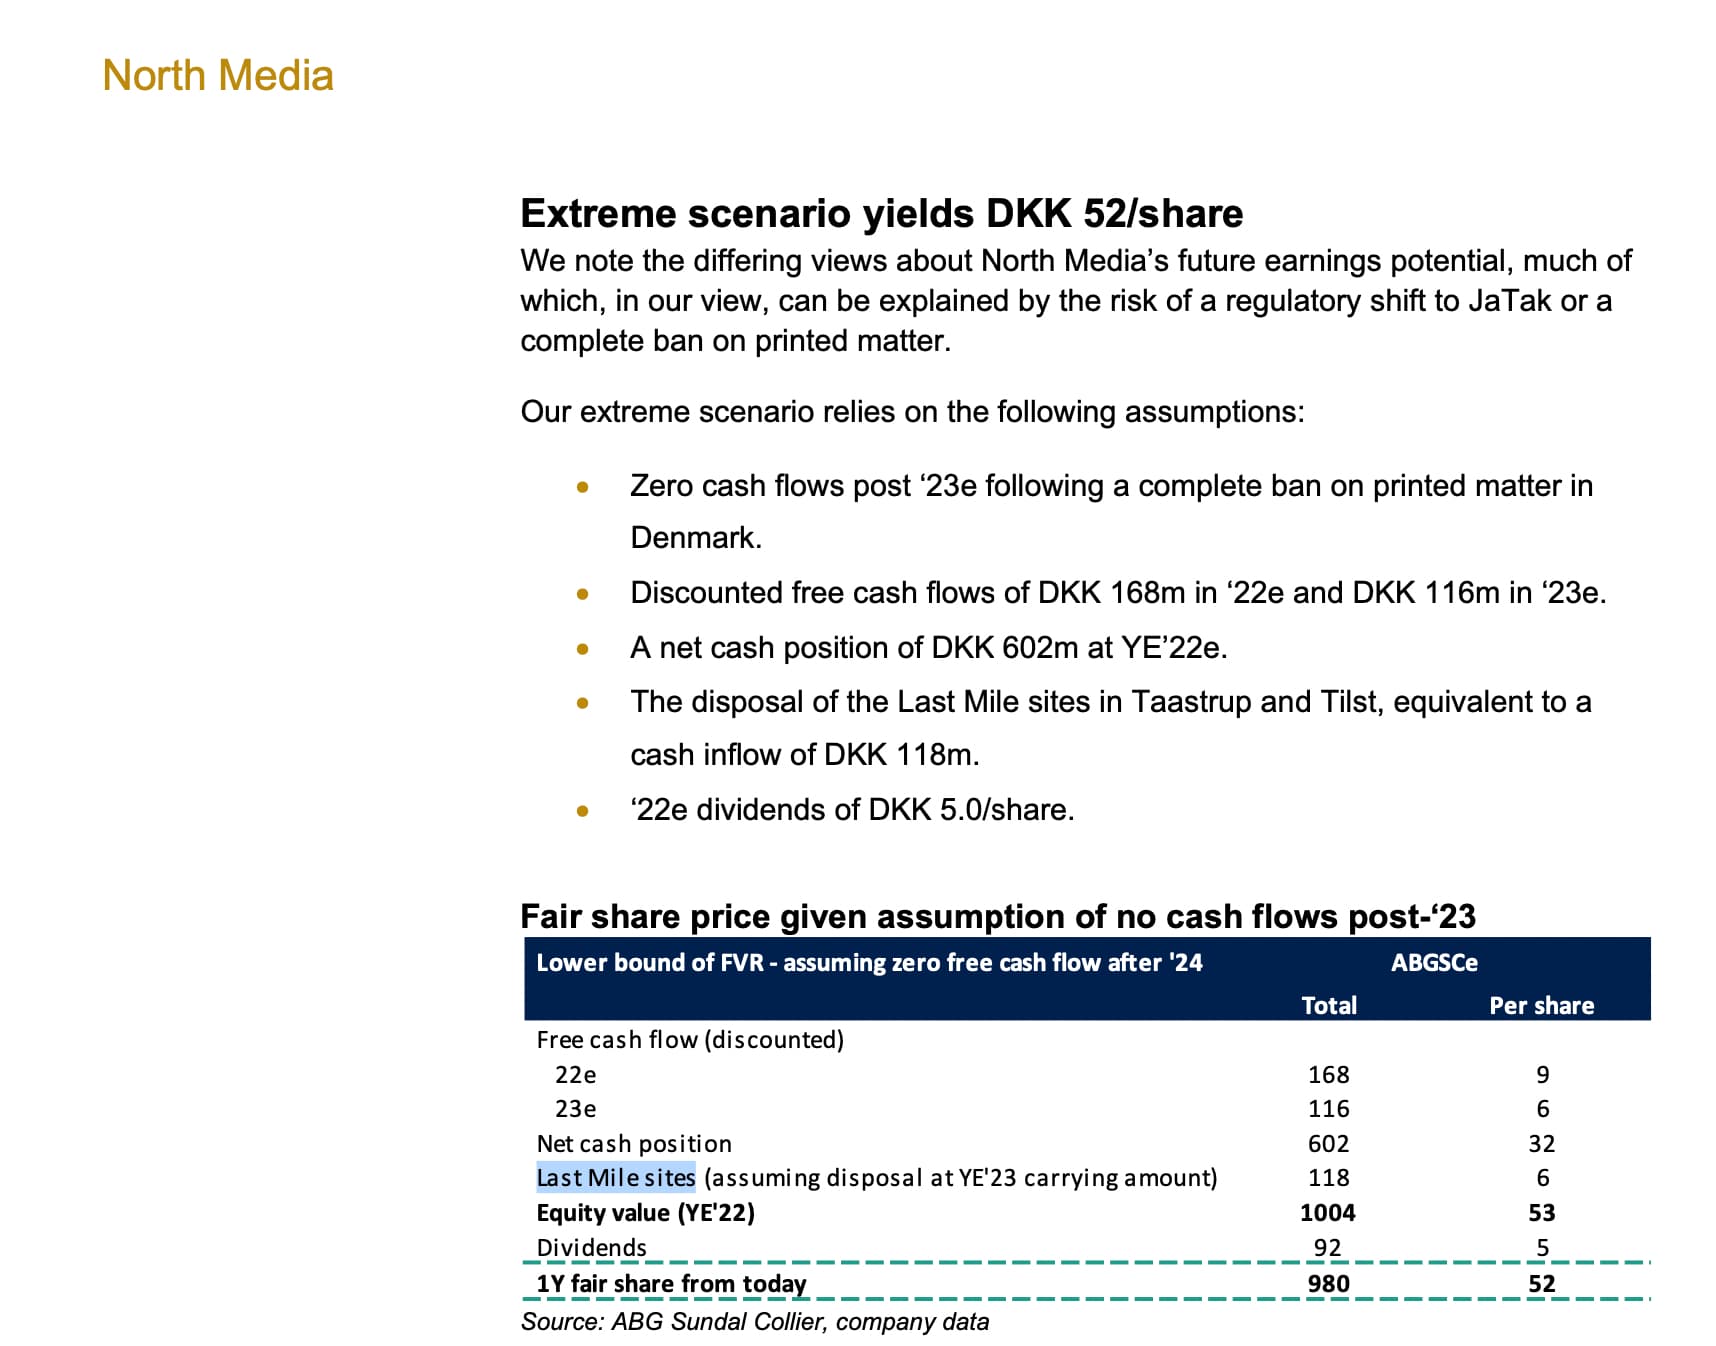
I couldn’t find a thread about this here on the forum, so hopefully through this we can figure out together whether these shares should be sold now or held.
E: The results for 2020 and 2021 were slightly incorrect

 However, as you said, BoligPortal is likely in their sights, as well as Ofir. I’m not sure what to think about that, as these are a big part of the company’s future. Of course, if it’s bought for a high price and cash flow is received from FK for a few years, the value would be unlocked through that and the company would disappear pretty quickly.
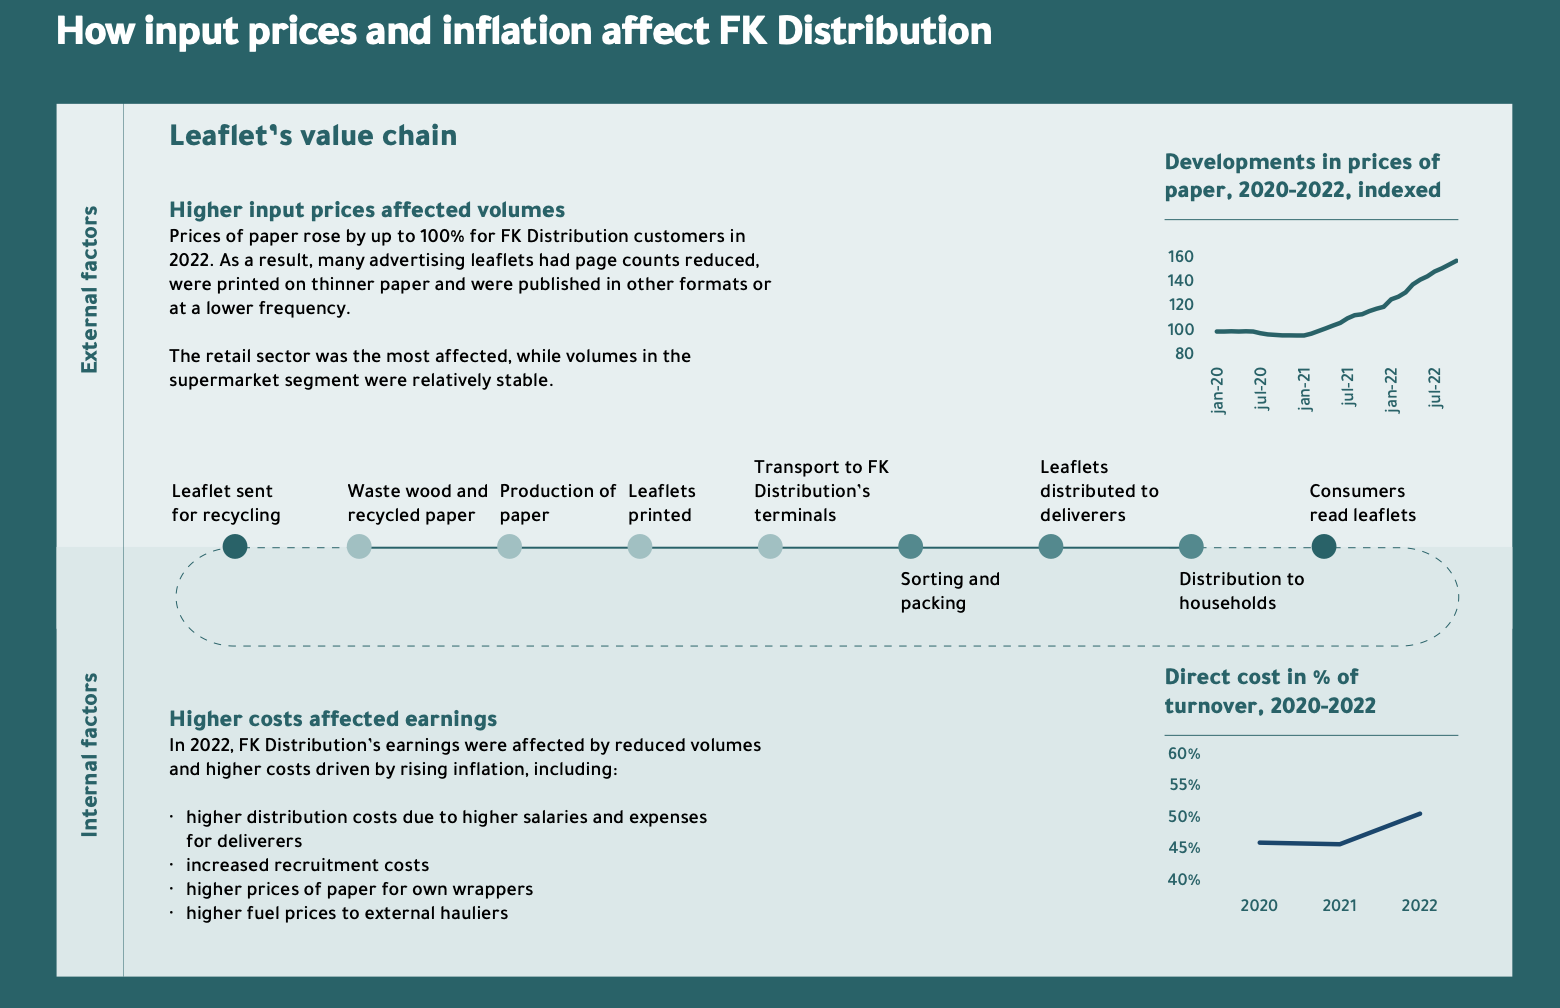


 A quick deep dive into this and a bit of a company status update on Twitter as well!