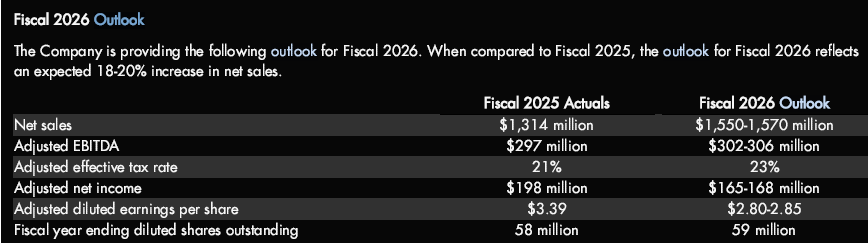E.L.F. Beauty - welcome to the beautyverse

Opening a thread for the growth rocket elf, which has now come down sharply after lowering its 2025 guidance.

Homepage

I haven’t done a more detailed analysis yet, as the valuation has been as tight as a violin string. Now that things are clearly moving towards more normal levels, it would be interesting to hear if anyone on the forum has looked into it more closely or is familiar with the products.

Elf is going through a similar phase to Celsius. It has grown very rapidly and turned profitable, which led to a blatant overvaluation. Now that growth has leveled off, everyone is rushing to sell, and this is reflected in a sharp drop in the share price. Most of the revenue comes from the domestic market (US), and the margins for low-price point products are impressive (~70%). I believe that affordable products have the potential to start gaining market share in international markets and increase that less than 20% share of revenue.

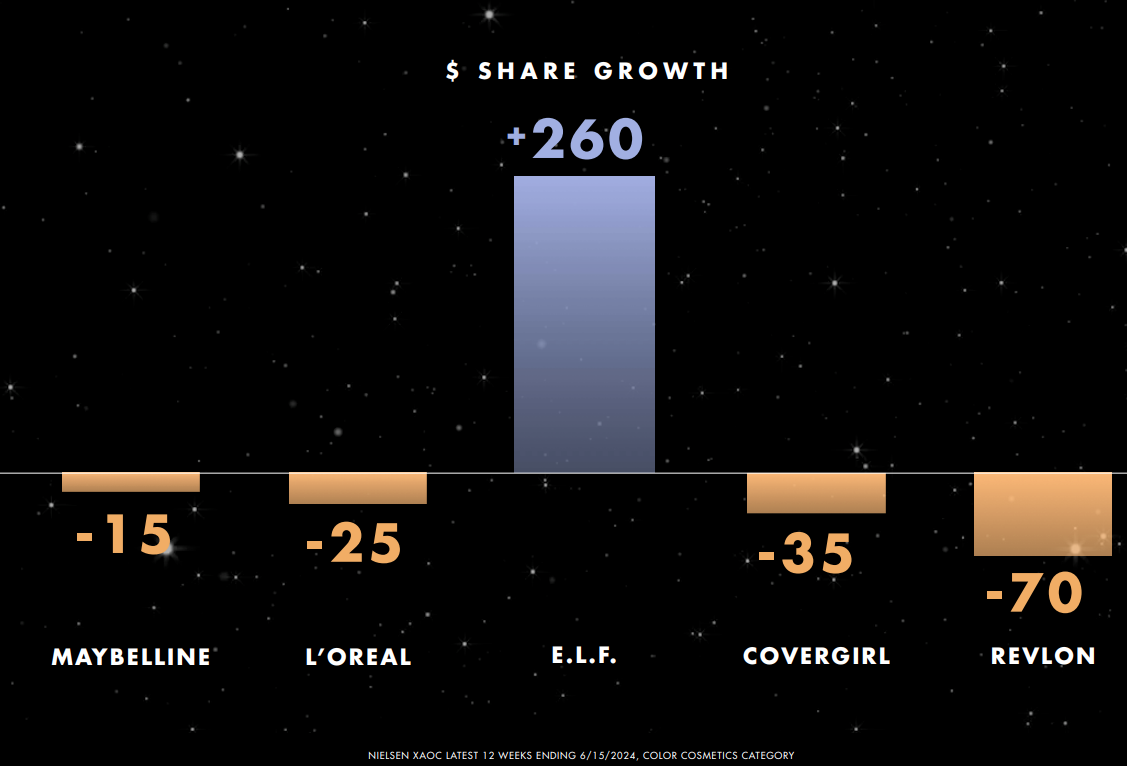
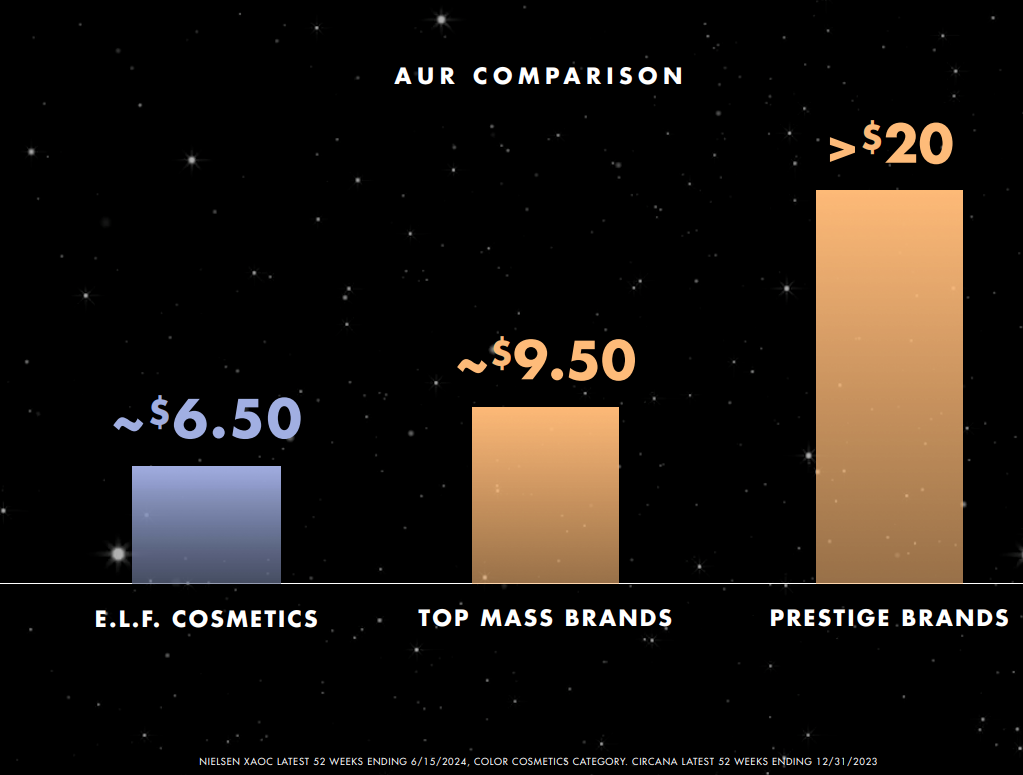
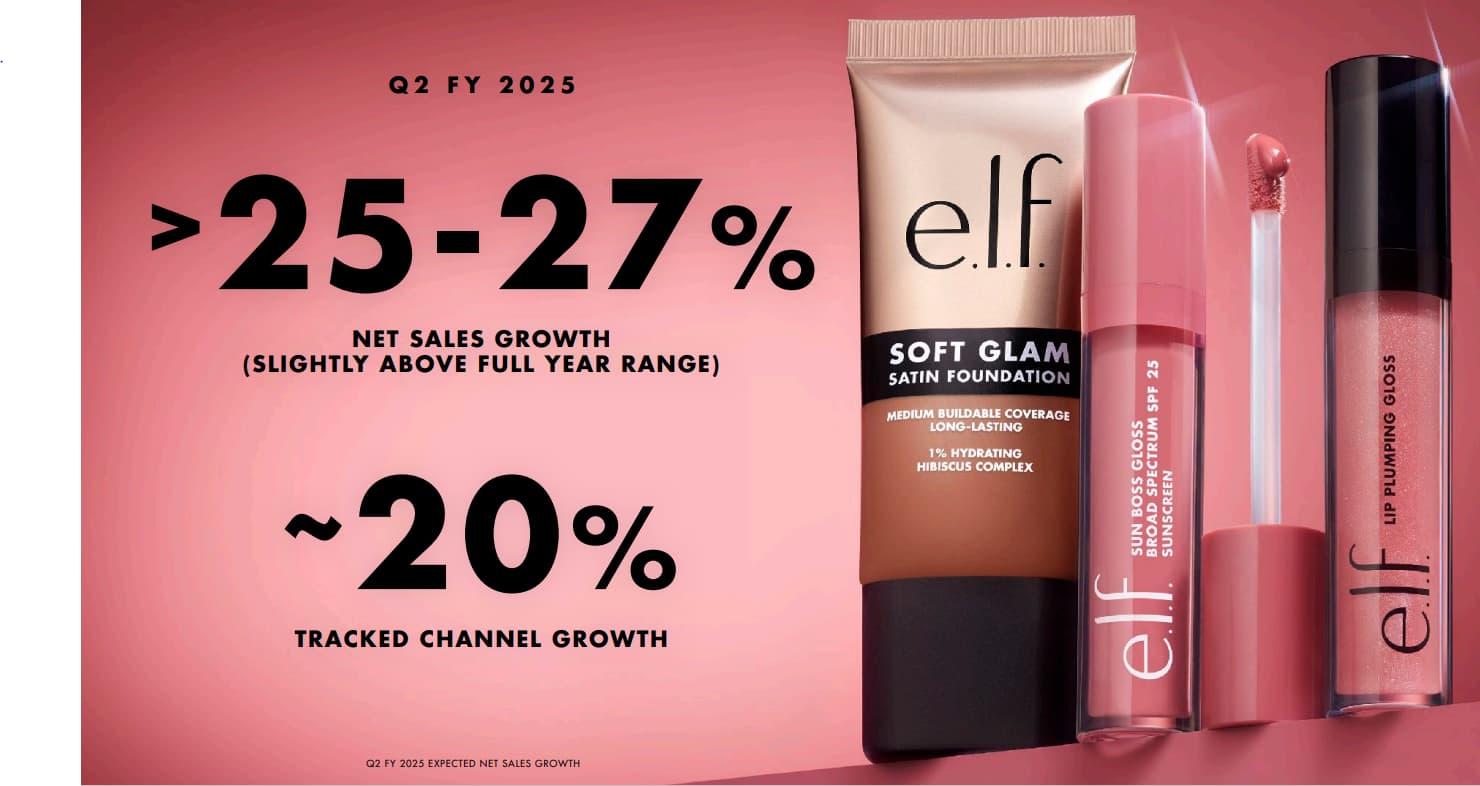
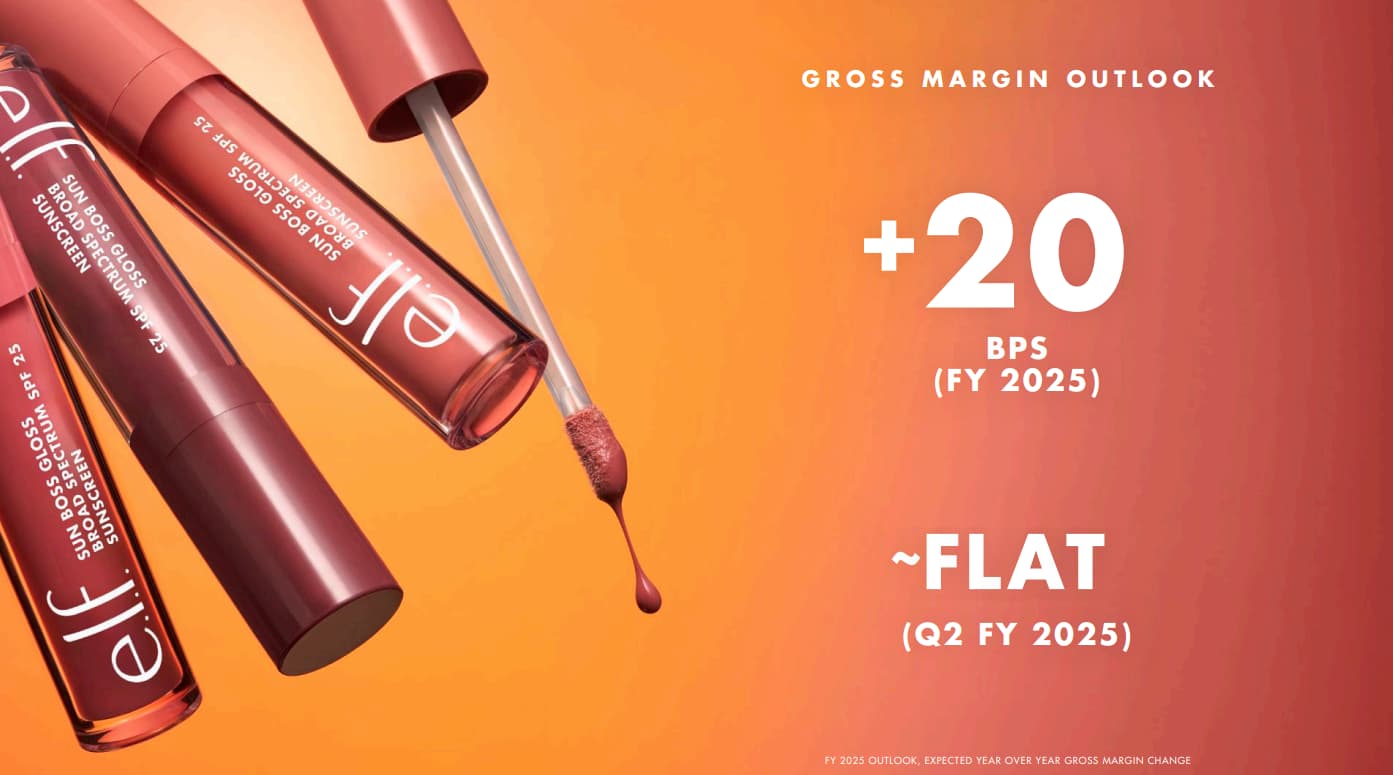
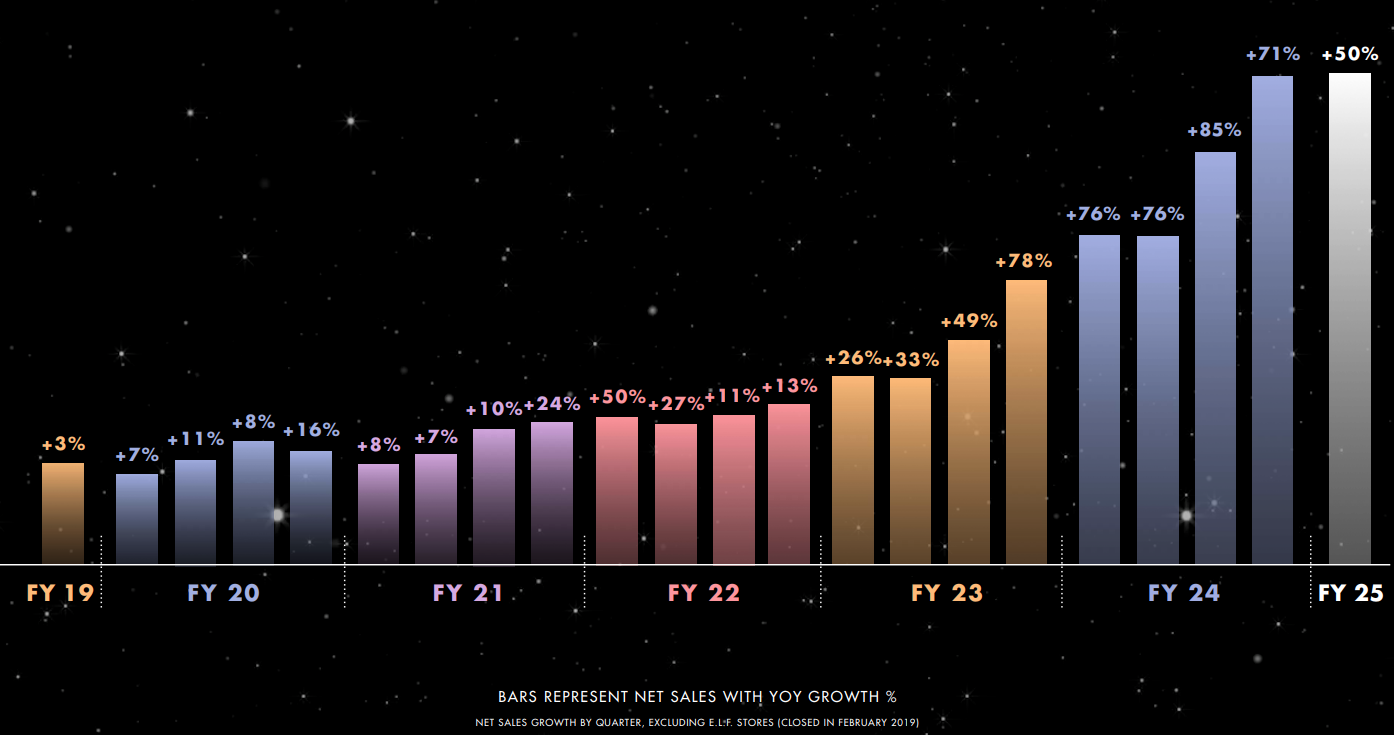
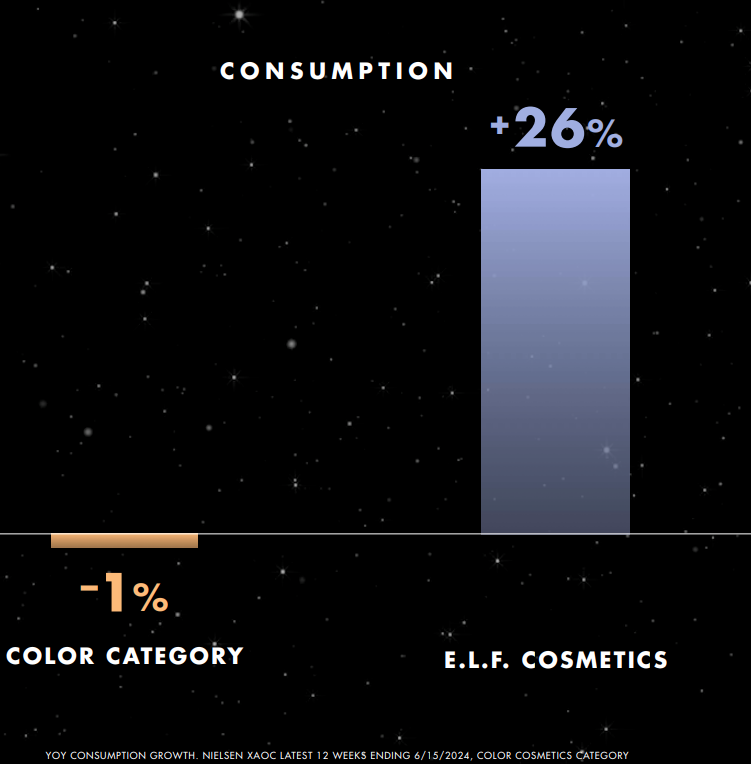
A few pages from the Q2 presentation.


9 Likes

Well yeah, this sells to Buffett’s investment too :wink:

“Our family of brands includes e.l.f. Cosmetics, e.l.f. SKIN, Naturium, Well People and Keys Soulcare. Our brands are available online and across leading beauty, mass-market, and specialty retailers. We have strong relationships with our retail customers such as Target, Walmart, Ulta Beauty and other leading retailers that have enabled us to expand distribution both domestically and internationally.”

A quick breakdown found:

“In the fiscal year ended March 31, 2024, national and international retailers comprised 84% of our net sales. The remaining 16% came from e-commerce channels.
The United States accounted for 85% of our net sales in the fiscal year ended March 31, 2024. The remaining 15% was attributable to international markets.”

The CEO seems like a real go-getter; I haven’t dug into the management more than that.

Financial management seems disciplined; they could afford the skincare company acquired last year, and the balance sheet is flat after the acquisition (EV~MC).

If you start digging into the cash flow statement, prepaid expenses, stock-based compensation, growth in accounts receivable, and inventory turnover cause extra work; they must be adjusted—they fluctuate quite a bit.

In the current year (Q1), revenue and gross margin jumped +50% vs Q1 2023, but SG&A doubled, leaving a smaller net income on the bottom line.

Management’s comments only mention normal cost growth, which is a bit concerning. I would have rather heard about ‘temporary integration costs’ or similar regarding last year’s acquisition.

“increase was primarily related to an increase in marketing and digital spend of $40.1 million, increased compensation and benefits expense of $15.1 million, increased operations costs of $10.7 million, increased retail fixturing and visual merchandising costs of $9.4 million, increased professional fees of $4.9 million and increased depreciation and amortization of $4.5 million”

You can estimate the valuation using whatever numbers you want, but it’s not easy. It’s easy to make false conclusions from the cash flow statement. Based on last year’s net income, the P/E is 45.
4 Likes

Tulos ulkona ja ainakin aftermarket perusteella miellytti markkinaa.

– Delivered 50% Net Sales Growth –

– e.l.f. Cosmetics Gained 260 Basis Points of Market Share –

– Raises Fiscal 2025 Outlook –

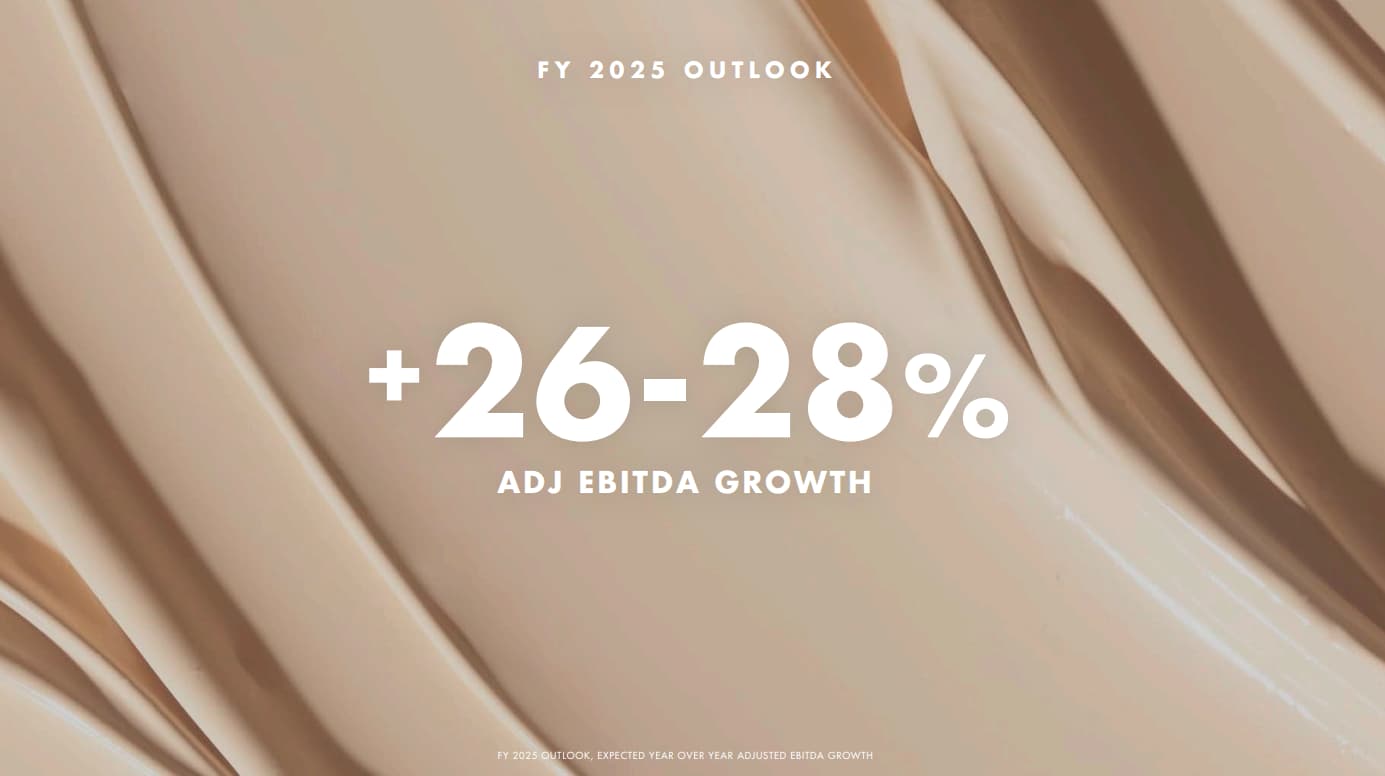
The updated outlook for fiscal 2025 reflects an expected 25-27% year-over-year increase in net sales, as compared to an expected 20-22% increase previously.

  • Gross margin increased approximately 80 basis points to 71%, primarily driven by favorable foreign exchange impacts, lower transportation costs, price increases in our international markets, cost savings and mix, partially offset by inventory adjustments.

  • Net income was $47.6 million on a GAAP basis. Adjusted net income (net income excluding the items identified in the reconciliation table below) was $64.3 million.

  • Diluted earnings per share were $0.81 on a GAAP basis. Adjusted diluted earnings per share (diluted earnings per share calculated with adjusted net income excluding the items identified in the reconciliation table below) were $1.10.

  • Adjusted EBITDA (EBITDA excluding the items identified in the reconciliation table below) was $77.4 million, or 24% of net sales, up 4% year over year.

3 Likes

Activist short-seller Muddy Waters Research published a report:

MW’s founder Carson Block interviewed on the topic on Bloomberg:

1 Like

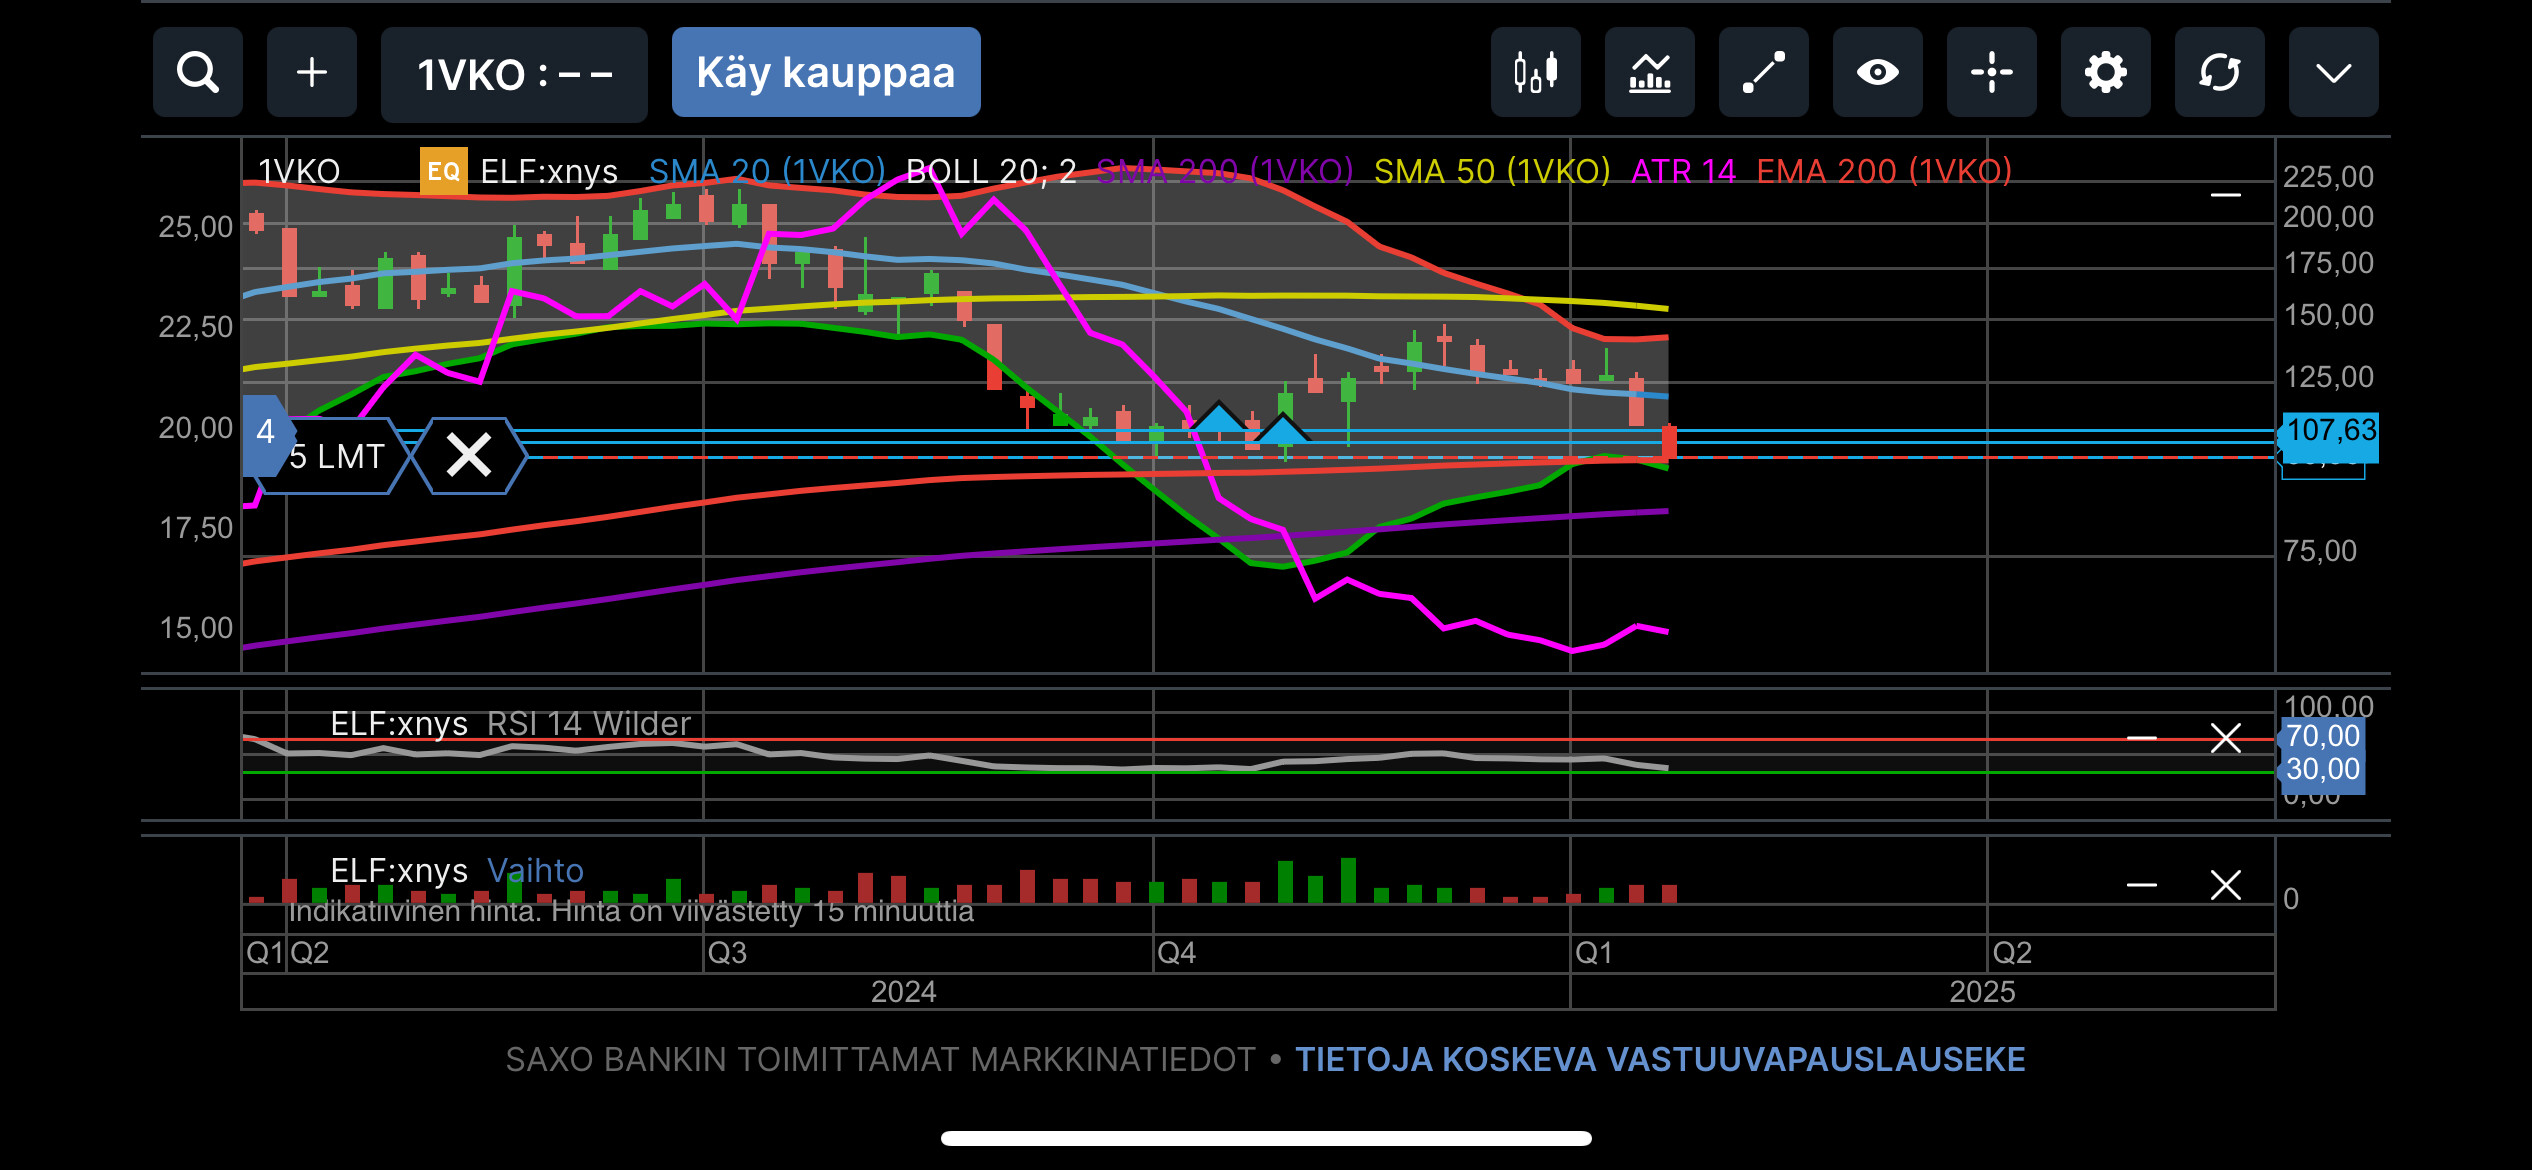
Elf took an interesting dip on Friday, and practically all the gains since the last earnings report (Q2) have now been eaten up. Q3 figures will be released next Thursday.

Last time I bought a bit at these levels, and it might not be a bad idea to add now if support is found around the hundred mark.

IMG_8230

A short report is out, and about 12% of the shares are shorted. Additionally, the effects of Trump’s tariffs increase uncertainty.

3 Likes

Pörssin mentyä kiinni saadaan Q3 luvut.
Odotuksissa on ~21% kasvua vuositasolla (330M$)

Adjusted EPS 0.76$.

Edit: toteuma

ELF Beauty (NYSE: ELF) reported third quarter EPS of $0.74, $0.03 worse than the analyst estimate of $0.77. Revenue for the quarter came in at $355.3M versus the consensus estimate of $329.03M.

1 Like

This guidance resulted in a -24% premarket drop. :exploding_head:

Guidance

ELF Beauty sees FY 2025 EPS of $3.27-$3.32 versus the analyst consensus of $3.61.

ELF Beauty sees FY 2025 revenue of $1.30B-$1.31B versus the analyst consensus of $1.34B.

2 Likes

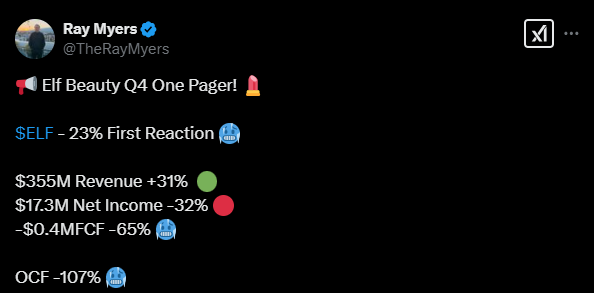
ELF dropped quickly and sharply after a weak report, especially due to lowered forecasts. The company exceeded revenue expectations, but earnings lagged, and the entire beauty industry suffered from weakening demand in the early part of the year.

CEO Tarang Amin said he still believes in the brand and sees the situation as temporary. He mentioned the post-season lull, a decrease in social media activity, and potential price pressures due to tariffs, but he remained optimistic about the future.

https://x.com/TheRayMyers/status/1887624723099418952

image
image

1 Like

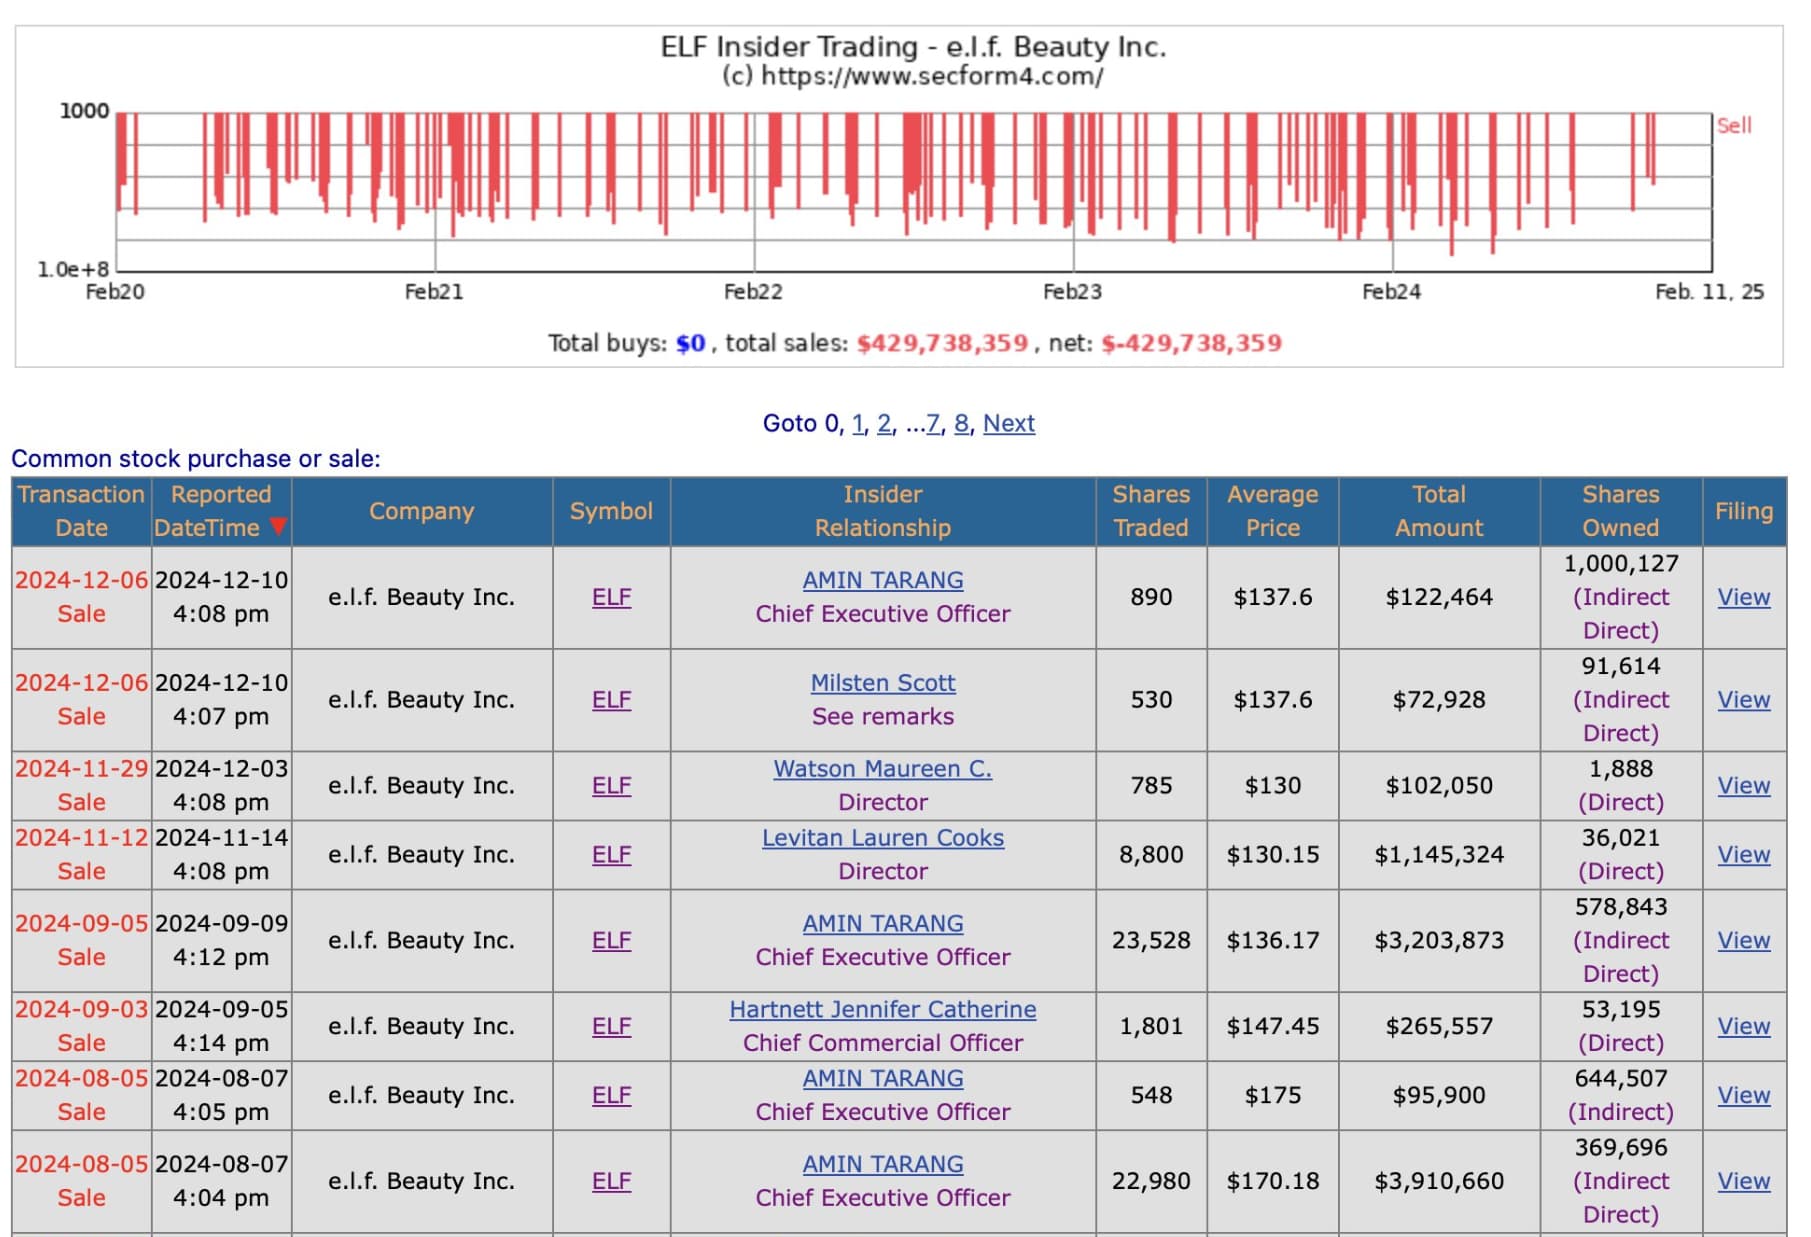
The tweet below discusses insider transactions. :slight_smile:

https://x.com/TidefallCapital/status/1888968093793132781

image
image

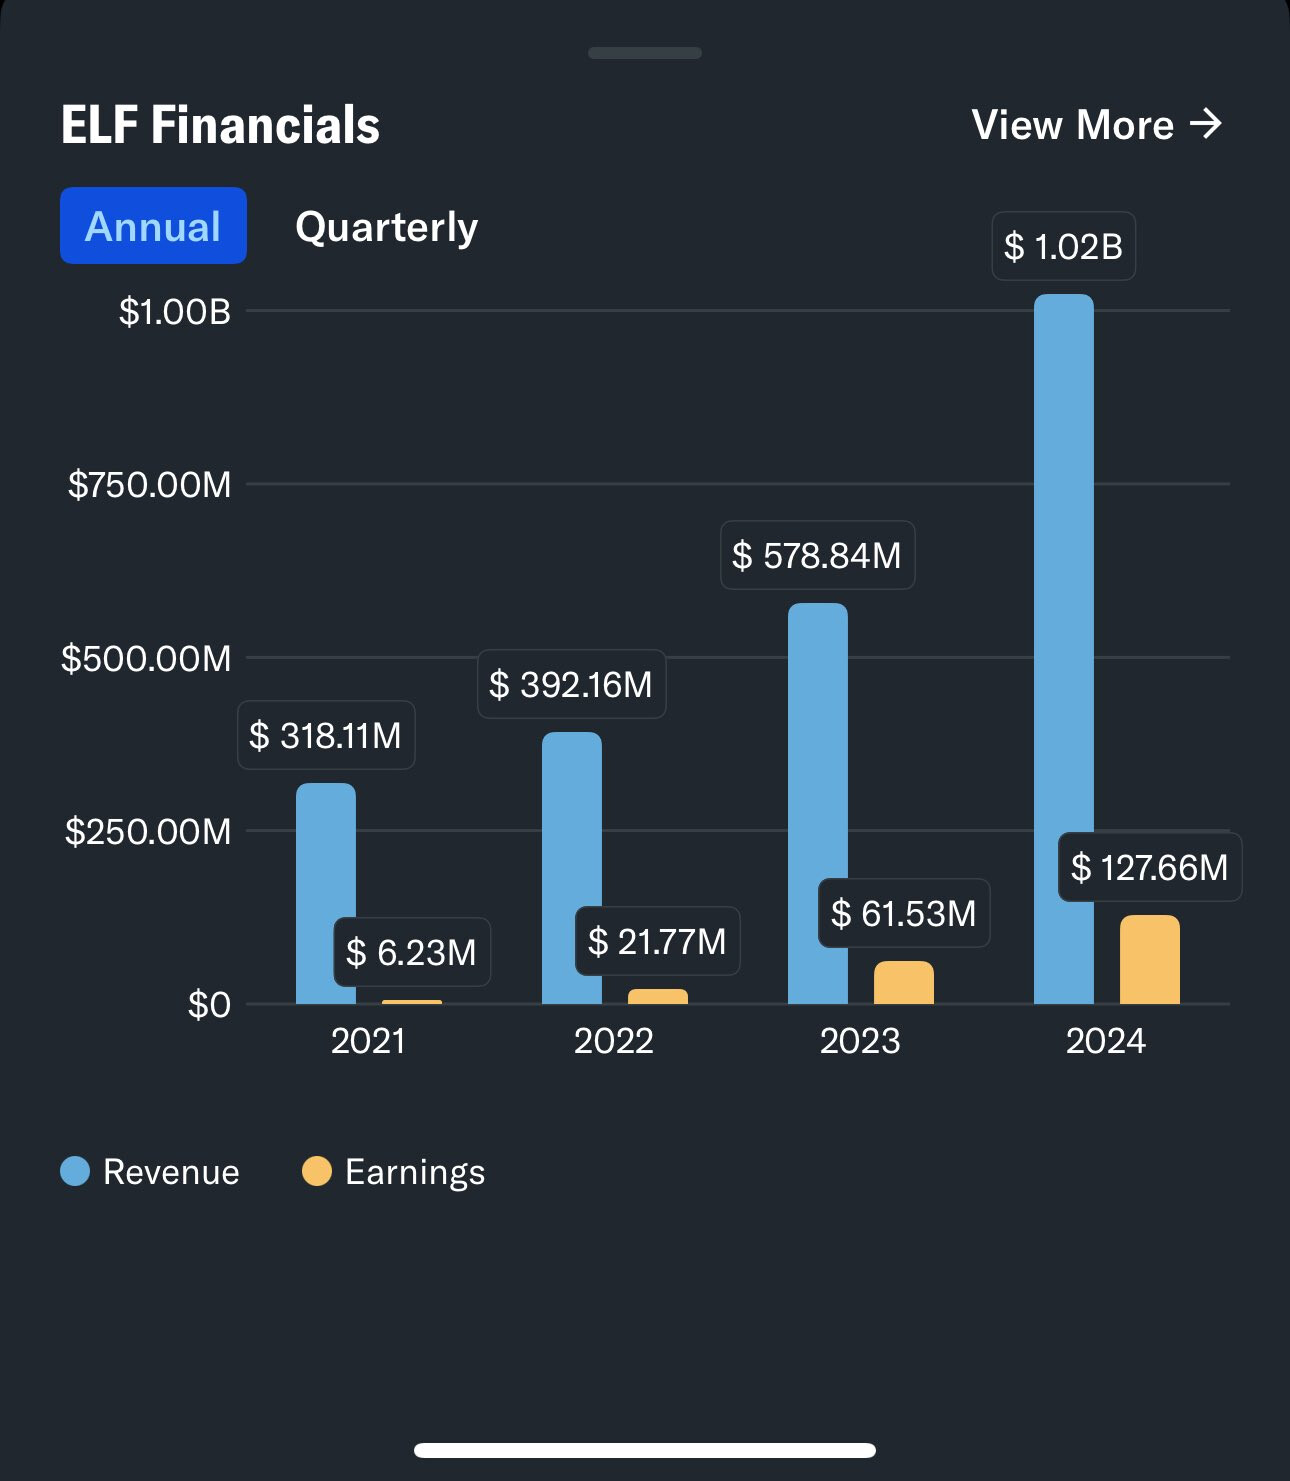
Here’s a pretty good tweet describing the development of revenue and profit. :slight_smile:

https://x.com/Genoisinvesting/status/1889684914099921106

image
image

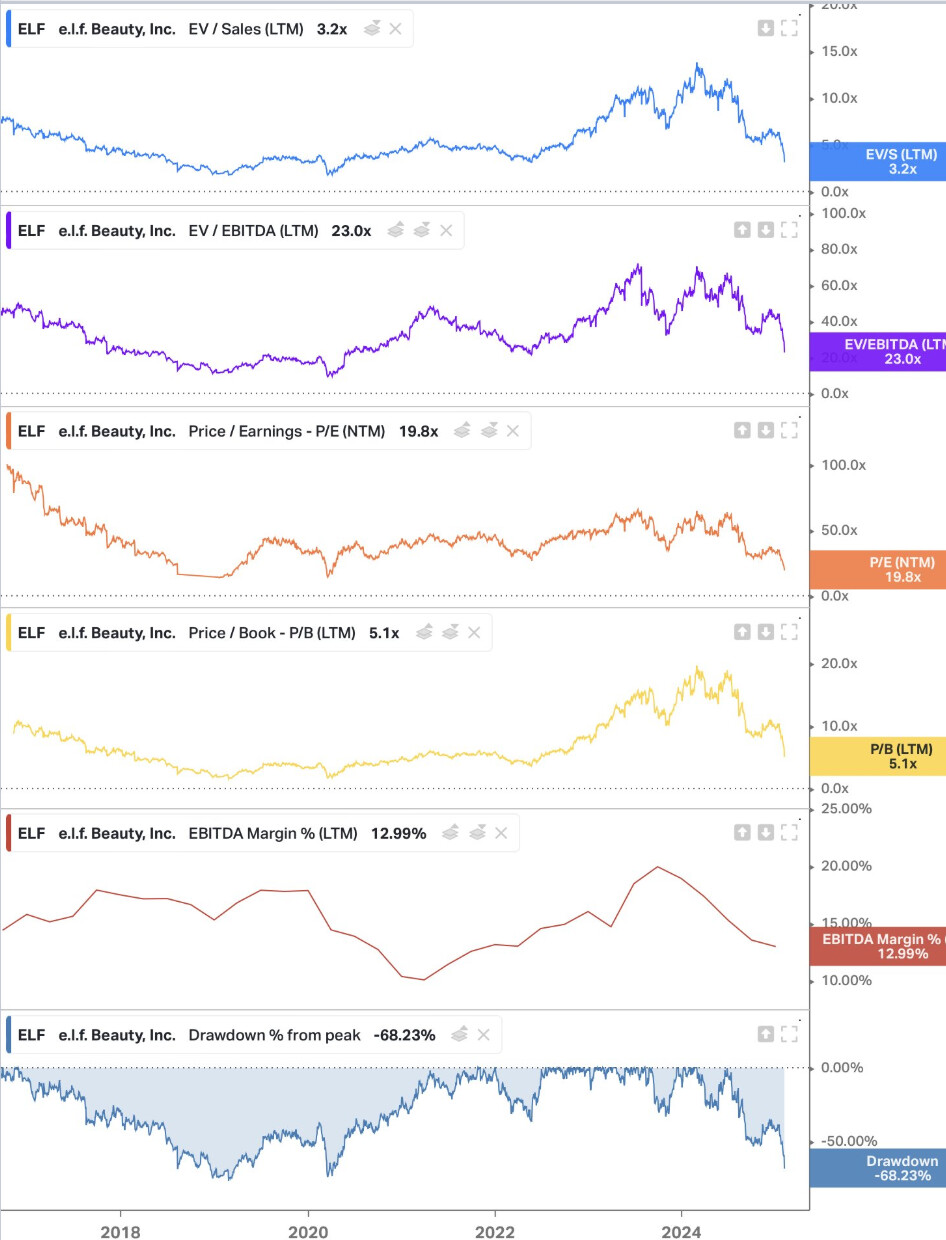
We could also bring the tweet below about changes in key figures here. :slight_smile:

https://x.com/TidefallCapital/status/1887920502850879610

image
image

3 Likes

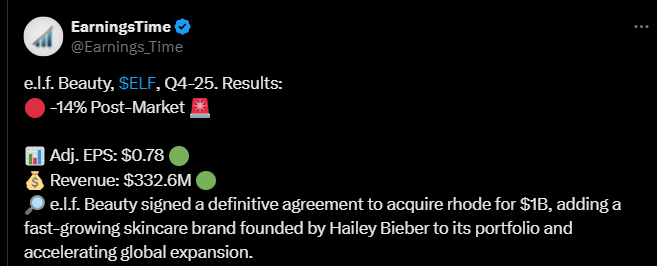
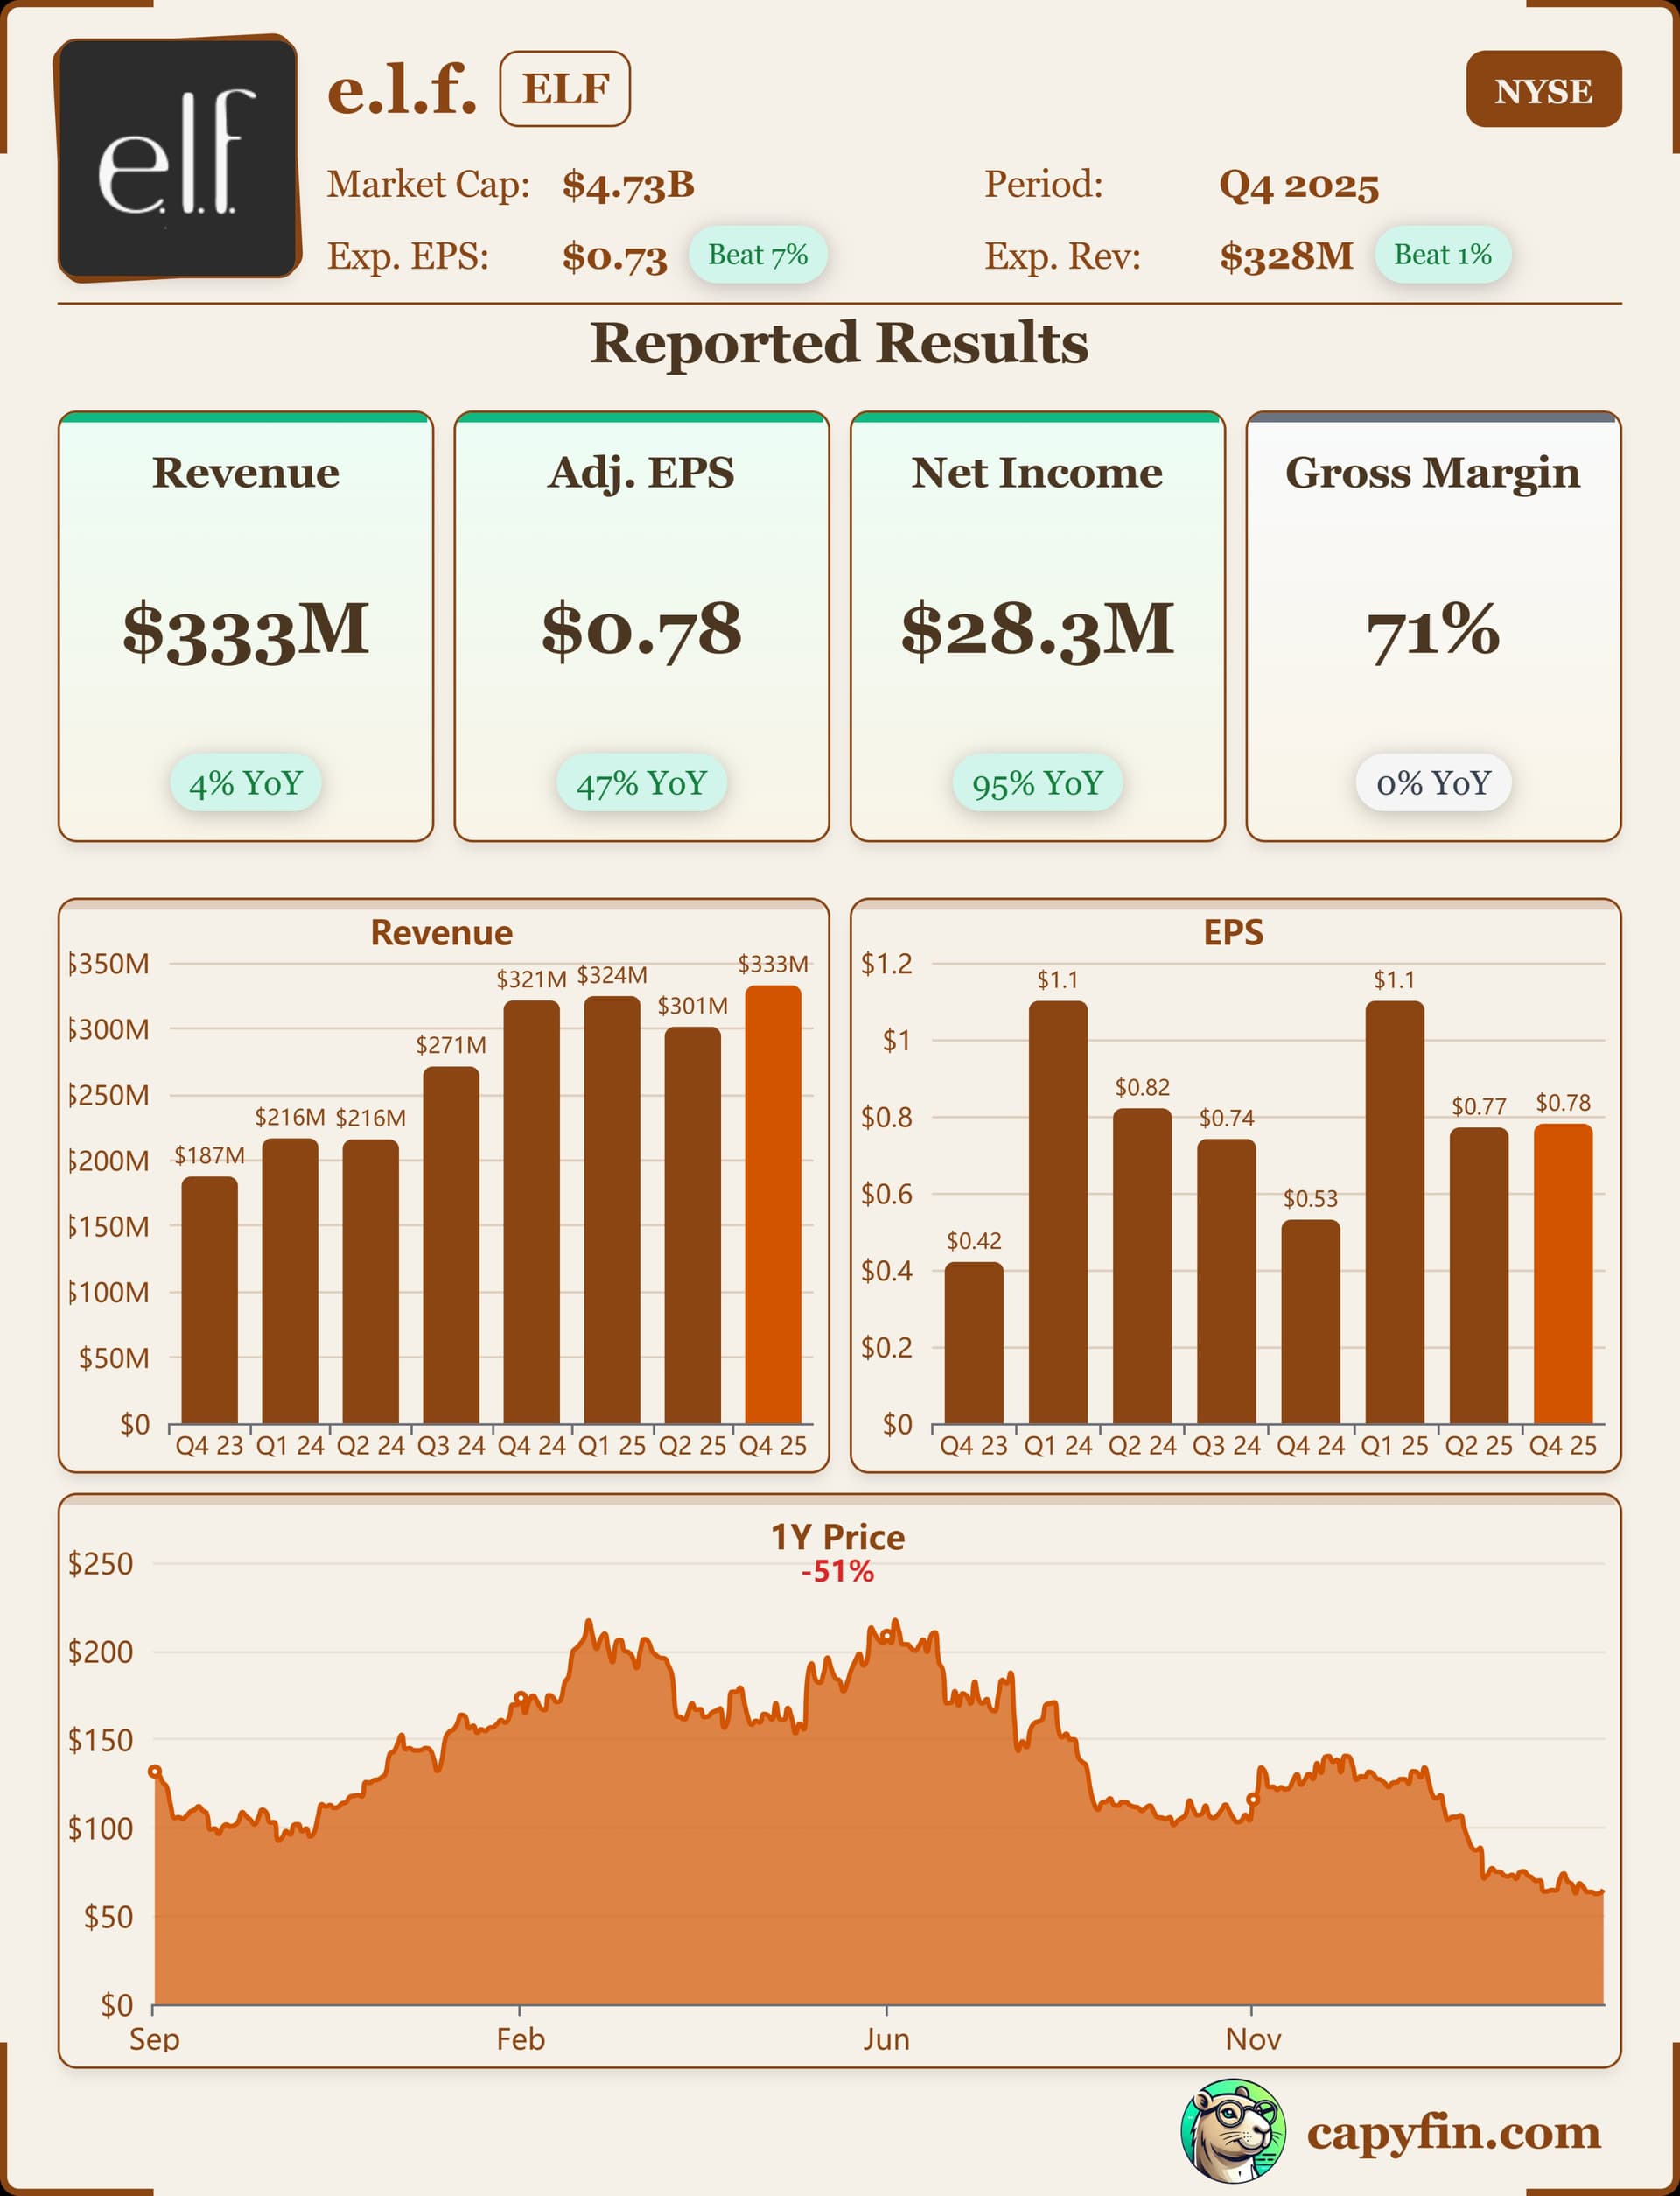
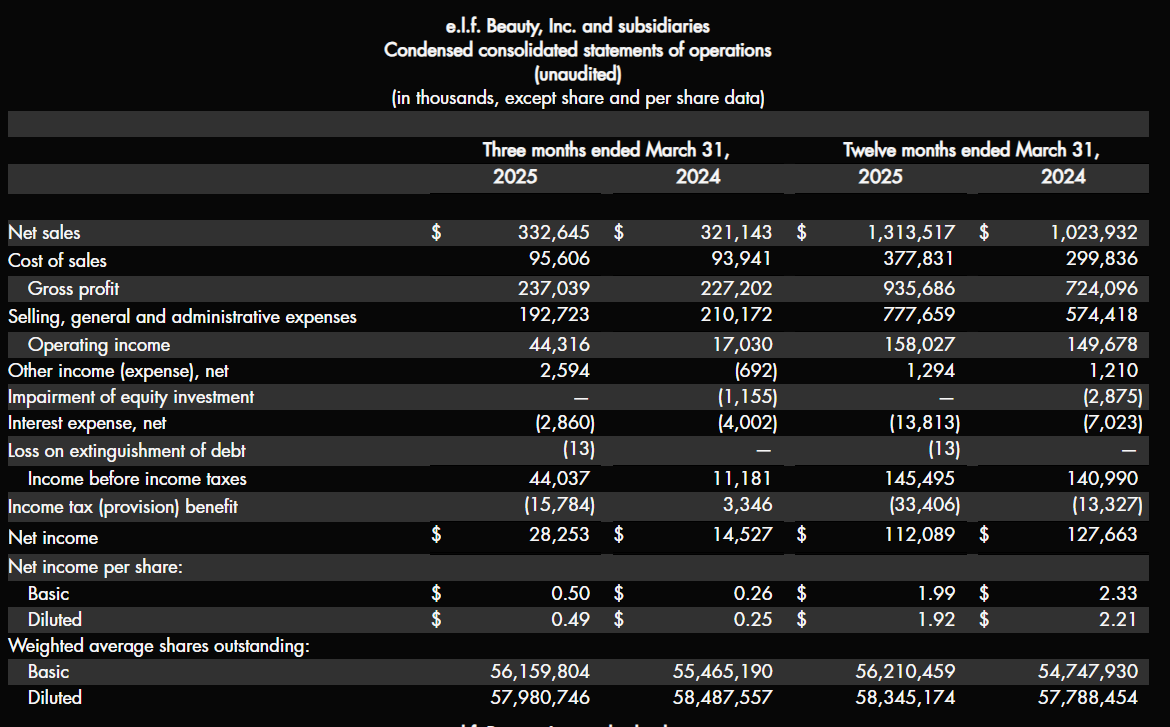
e.l.f. Beauty reported a strong quarter: revenue and earnings grew significantly, and market share in the United States also increased.

The company succeeded in expanding its international operations and improving profitability. Marketing and digital investments were cut, and the company also announced the acquisition of Rhode.

https://x.com/Earnings_Time/status/1927820482092384506
image
image


Company’s Own Materials

image

2 Likes

It still seems to be a trend for a celebrity to establish their own beauty brand (makeup, perfume, etc.) and then leverage their millions of followers to boost it. At this stage, a larger entity buys out the rising brand, but what happens after that? Do these businesses, built entirely around a person’s brand, have genuine business potential, or is this an attempt to acquire potential customers? A billion customers sounds like a lot.

” In its latest fiscal year ending in March, the brand generated $212 million in net sales from just 10 products, including hits like its Pocket Blush and Glazing Milk essence. This month, Rhode announced it will launch in all Sephora US and Canada stores in the fall, and in Sephora UK by the end of the year.”

Indeed, money is being made there, and with a very small number of products.

“What we saw in Rhode was another like-minded disruptor,” he said. “I see Hailey as much more than a celebrity, she is one of the most thoughtful founders I’ve ever met. She has incredible instinct, a beautiful aesthetic that’s absolutely resonating with her community.”

This time, the celebrity is indeed a skilled entrepreneur, which is certainly also true.

”Bieber will continue in her capacity as Rhode co-founder, chief brand officer and head of innovation, as well as act as a strategic advisor for E.l.f. The remaining Rhode team, including co-founders Lauren and Michael D. Ratner and CEO Nick Vlahos, previously of The Honest Company, will join E.l.f. Beauty. Under the terms of the agreement, E.l.f. has agreed to pay $800 million for the brand — $600 million cash and $200 million in shares — with a potential $200 million earnout based on the brand’s growth over the next three years.”

Bieber will continue with the brand as well as E.l.f.'s head of innovation & advisor. Part of the purchase price is tied to the brand’s growth over the next 3 years. In this respect, the commitment of the key person seems good.

E.l.f. assisted in the initial growth phase and noticed the rapid growth of the brand founded in 2022. The collaboration worked well and sales expanded internationally, so it was a good opportunity to strengthen the collaboration by joining forces.

2 Likes

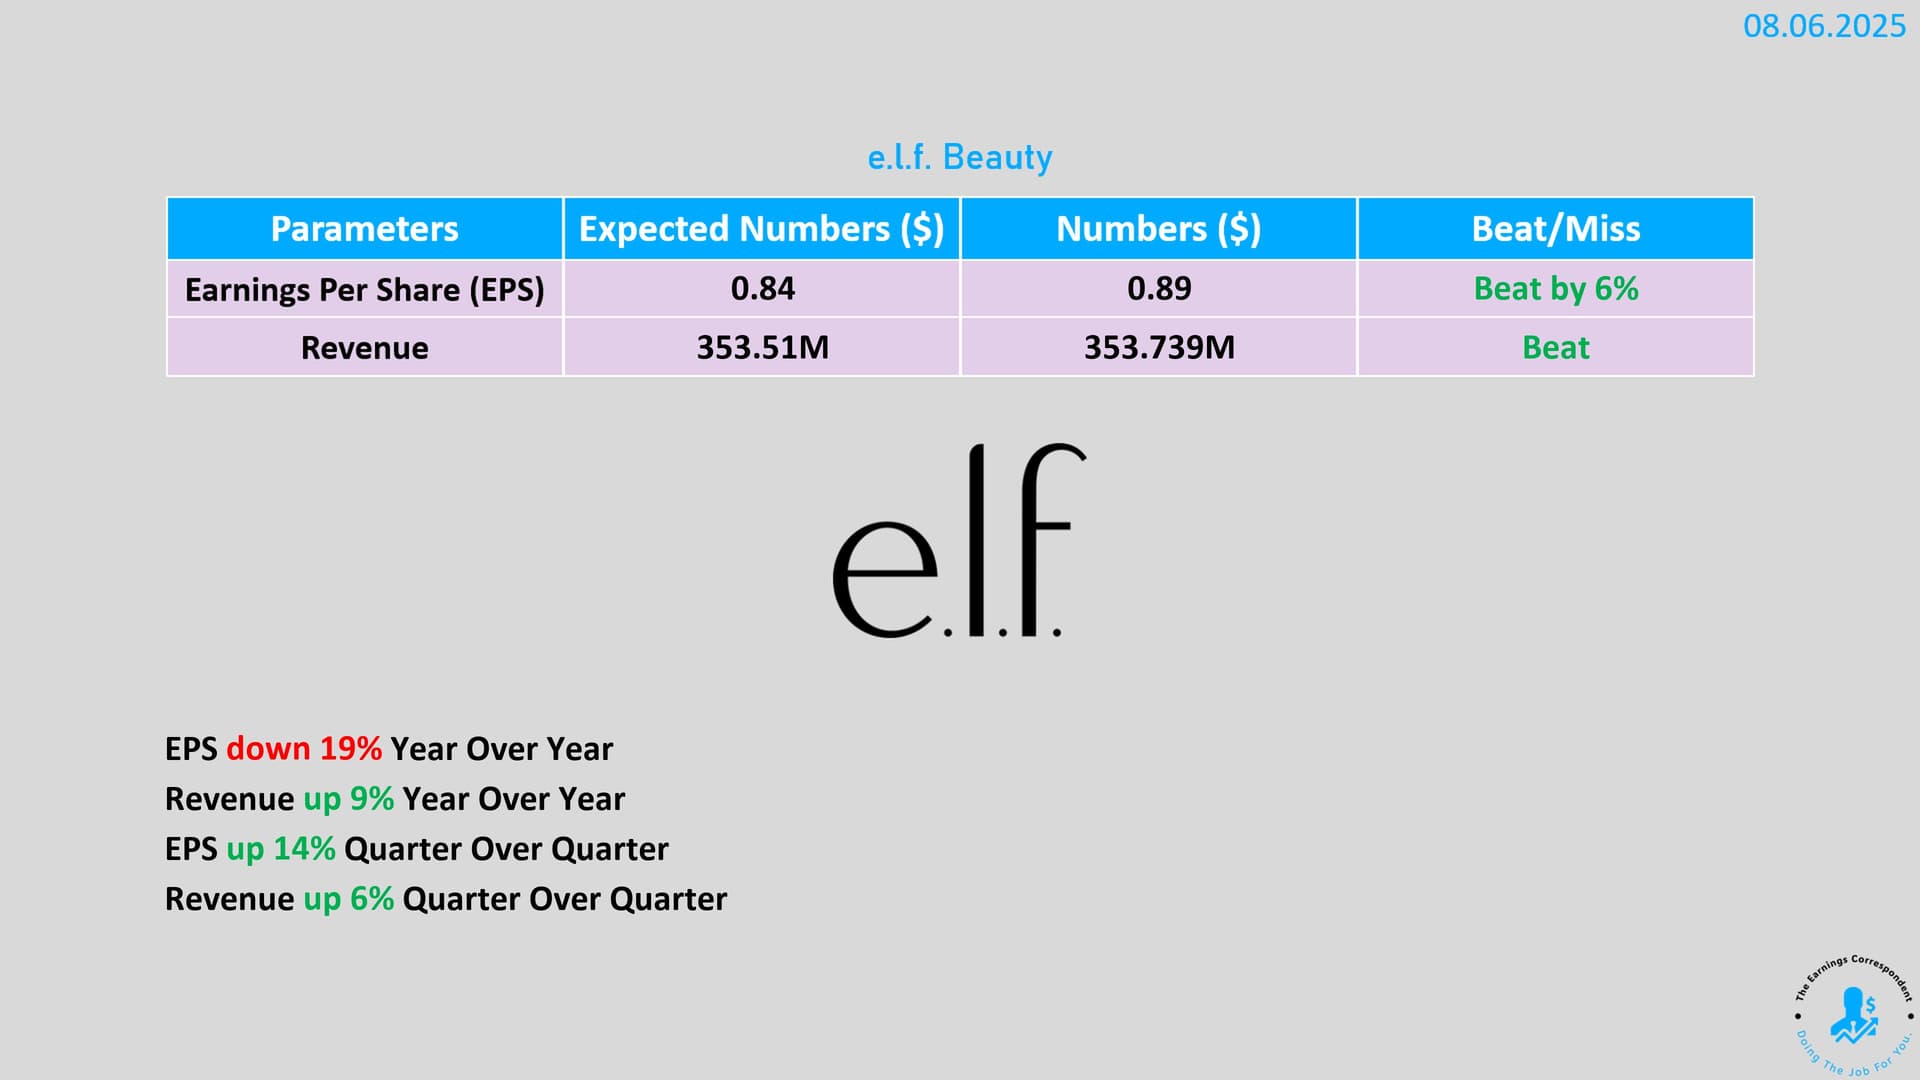
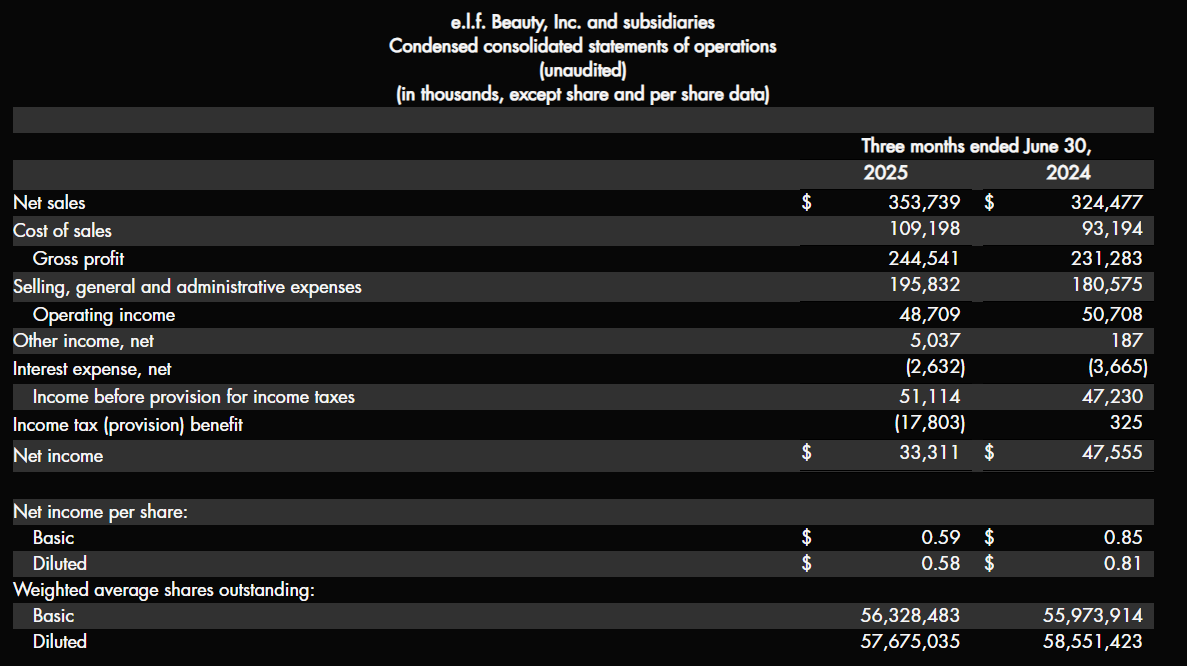
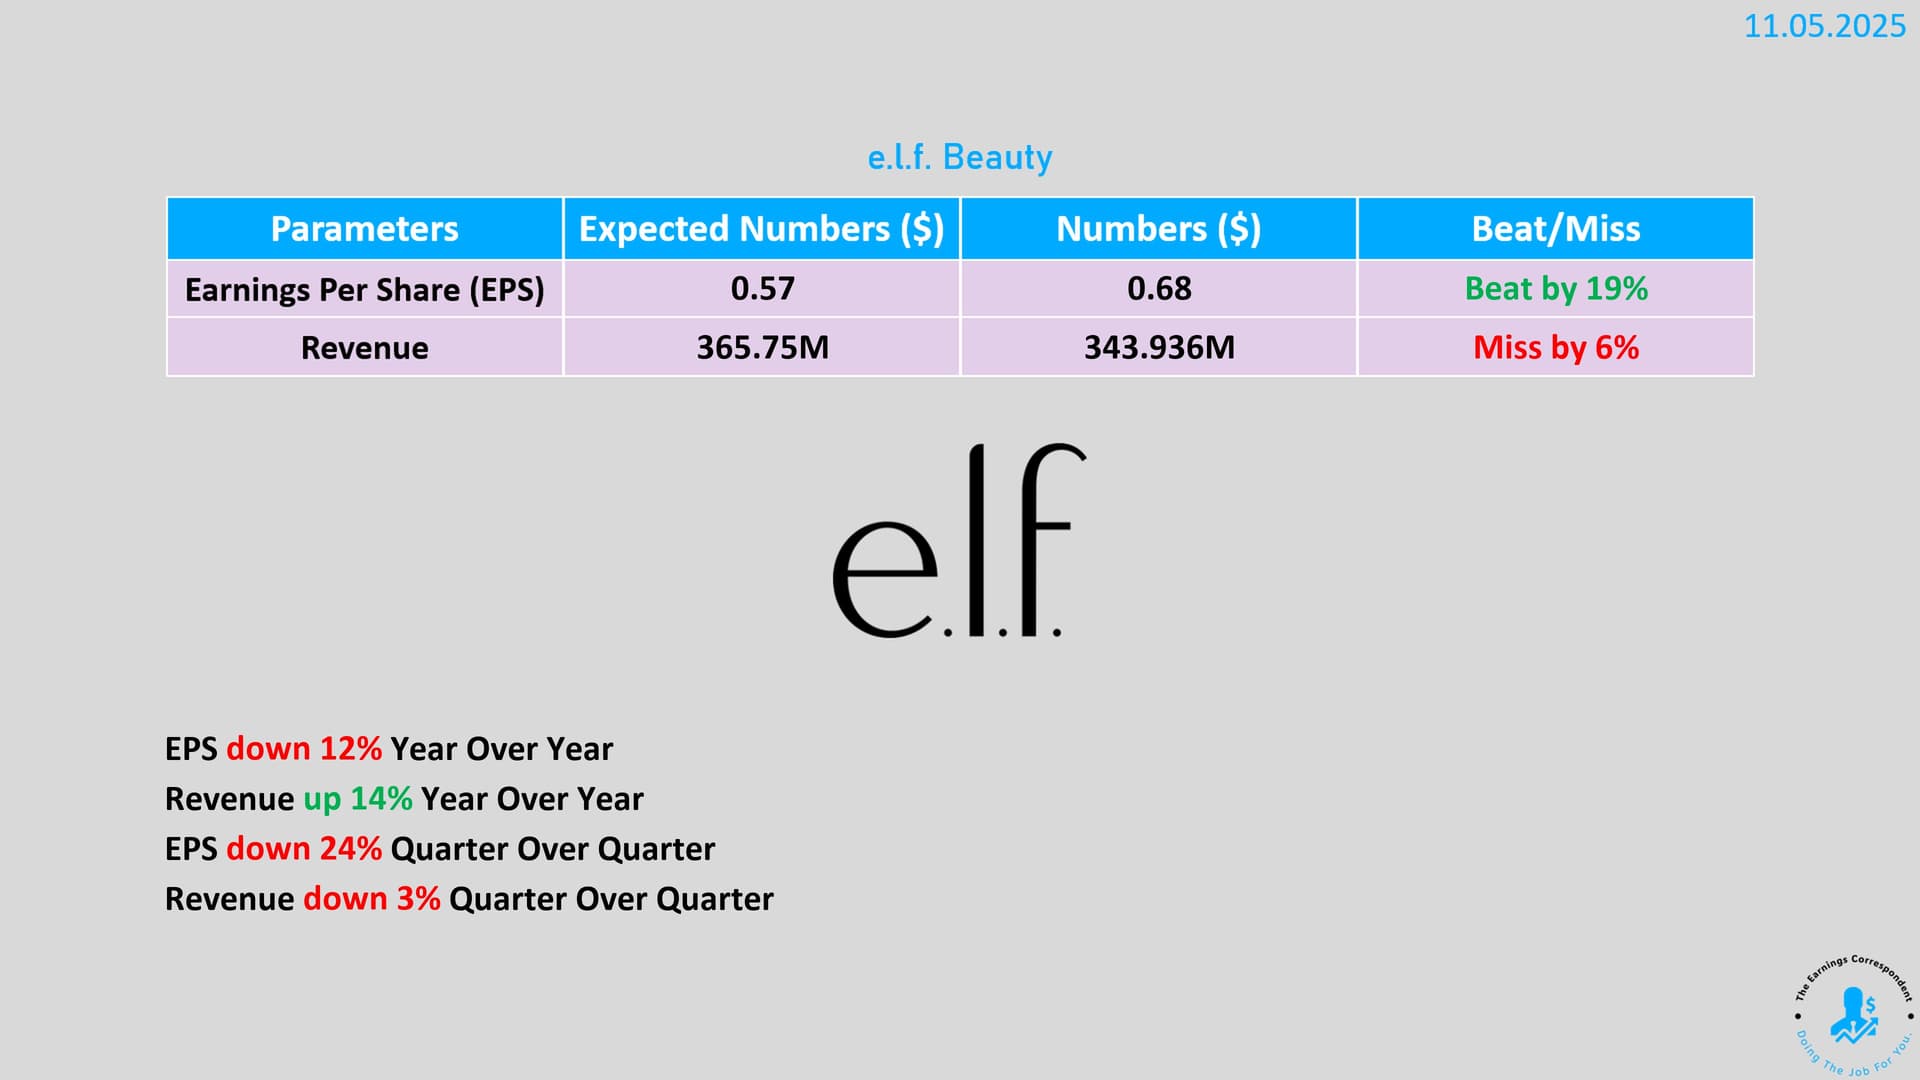
E.L.F. reported strong growth, driven by good development in both brick-and-mortar stores and online, domestically in the US as well as internationally. Profitability remained at a good level, although the gross margin slightly weakened due to tariffs.

According to the company itself, growth continues to be strong thanks to innovative products, attractive pricing, and effective marketing. There was a lot of chatter in the company’s words, or maybe I just didn’t get it. :slight_smile:

https://x.com/earnings_guy/status/1953185791032586349
image
image


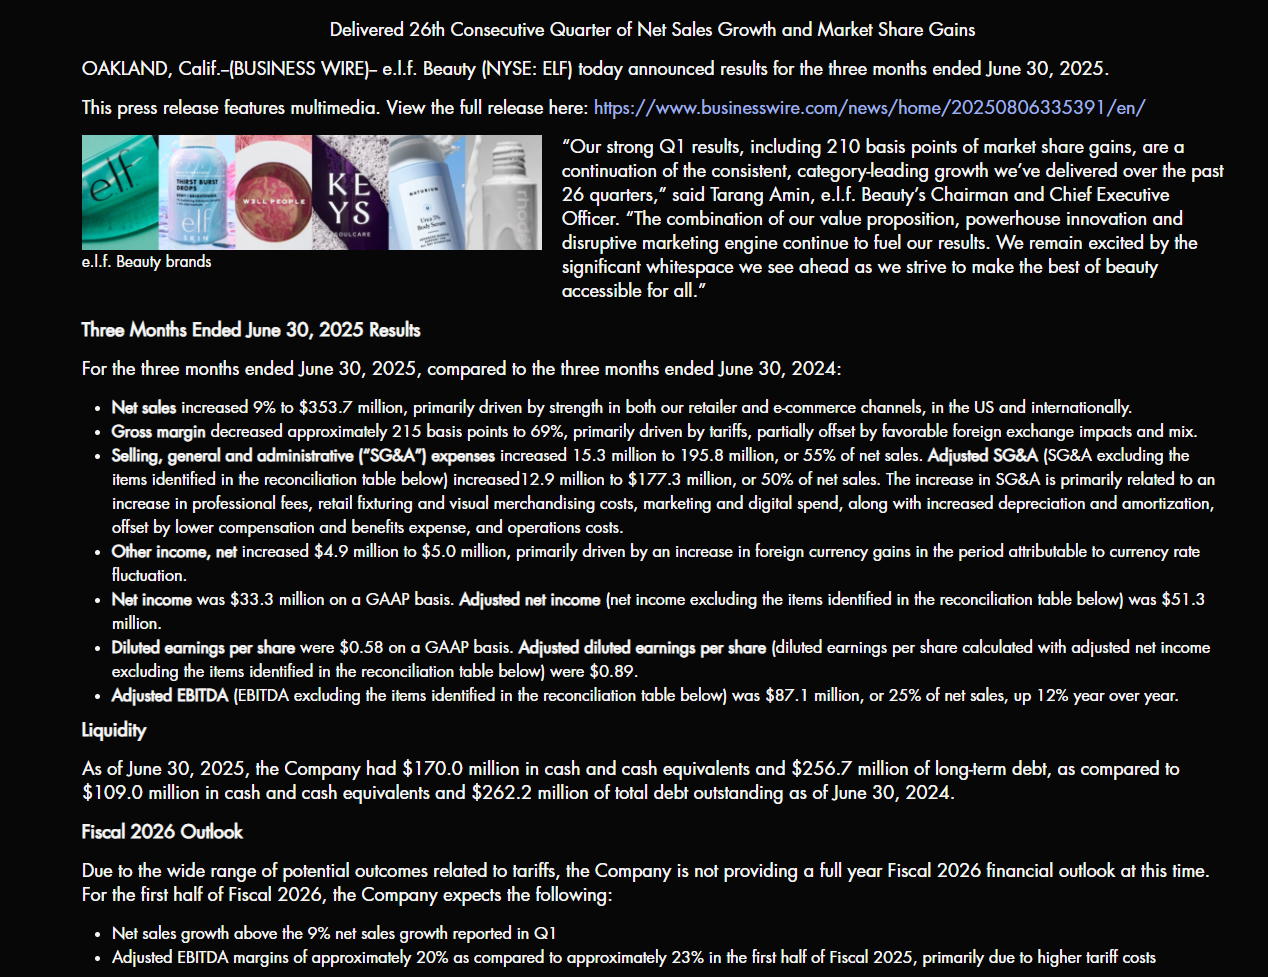
Company’s own materials

image
image

2 Likes

Customs duties certainly hit unpleasantly when manufacturing is in China, and the guidance shows a bit of growth stagnation. This could be an opportunity for the patient to jump on board if one believes in the temporary nature of the problems. I myself will probably still wait for a buying opportunity lower down.

A noteworthy observation from this summer is that E.L.F products had clearly appeared in Kicks and Sokos stores. Perhaps its expansion into Europe will start more significantly due to customs duties.

2 Likes

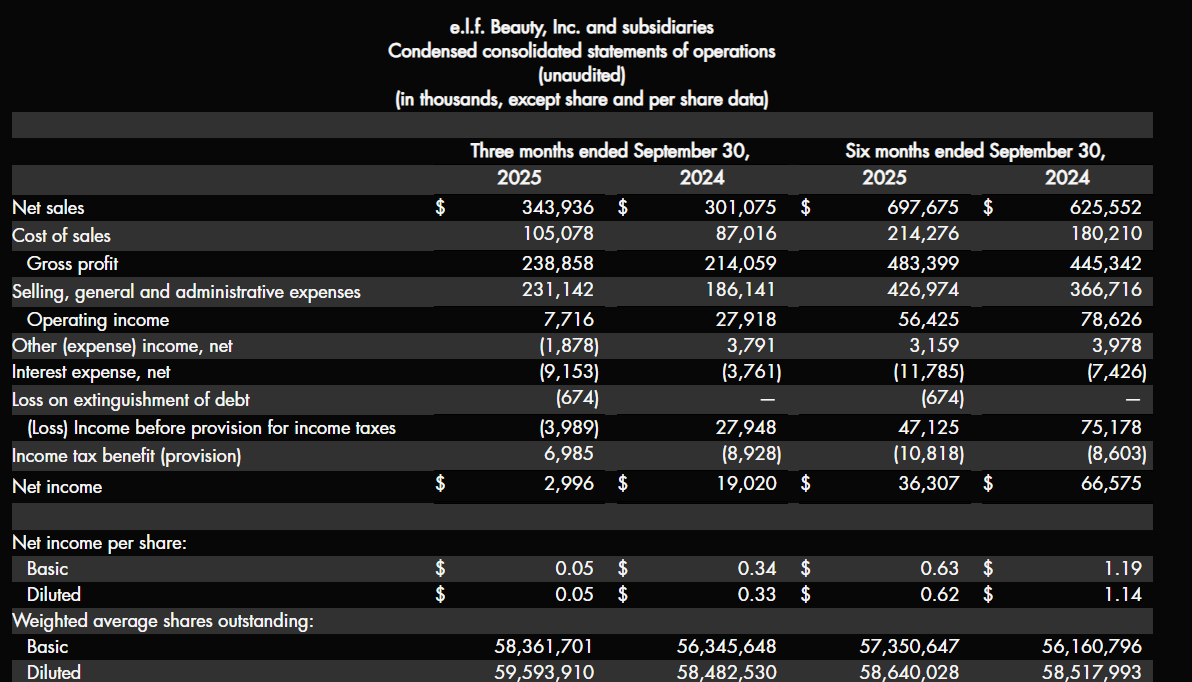
E.L.F. significantly grew its revenue both in retail stores and online, as well as domestically and internationally. Margins slightly weakened primarily due to customs duties, but pricing and product mix subsequently stabilized the situation.

The unadjusted result remained modest, but the adjusted result was clearly better. Management emphasized that the brand gained more market share and the new launch at Sephora performed exceptionally well, which reinforces confidence in continued growth.

https://x.com/earnings_guy/status/1986179508529971661


Company’s own materials


Huh, what a reaction in the aftermarket. -24% hit the board. Should I grab elffi back into the portfolio? :slight_smile:

1 Like

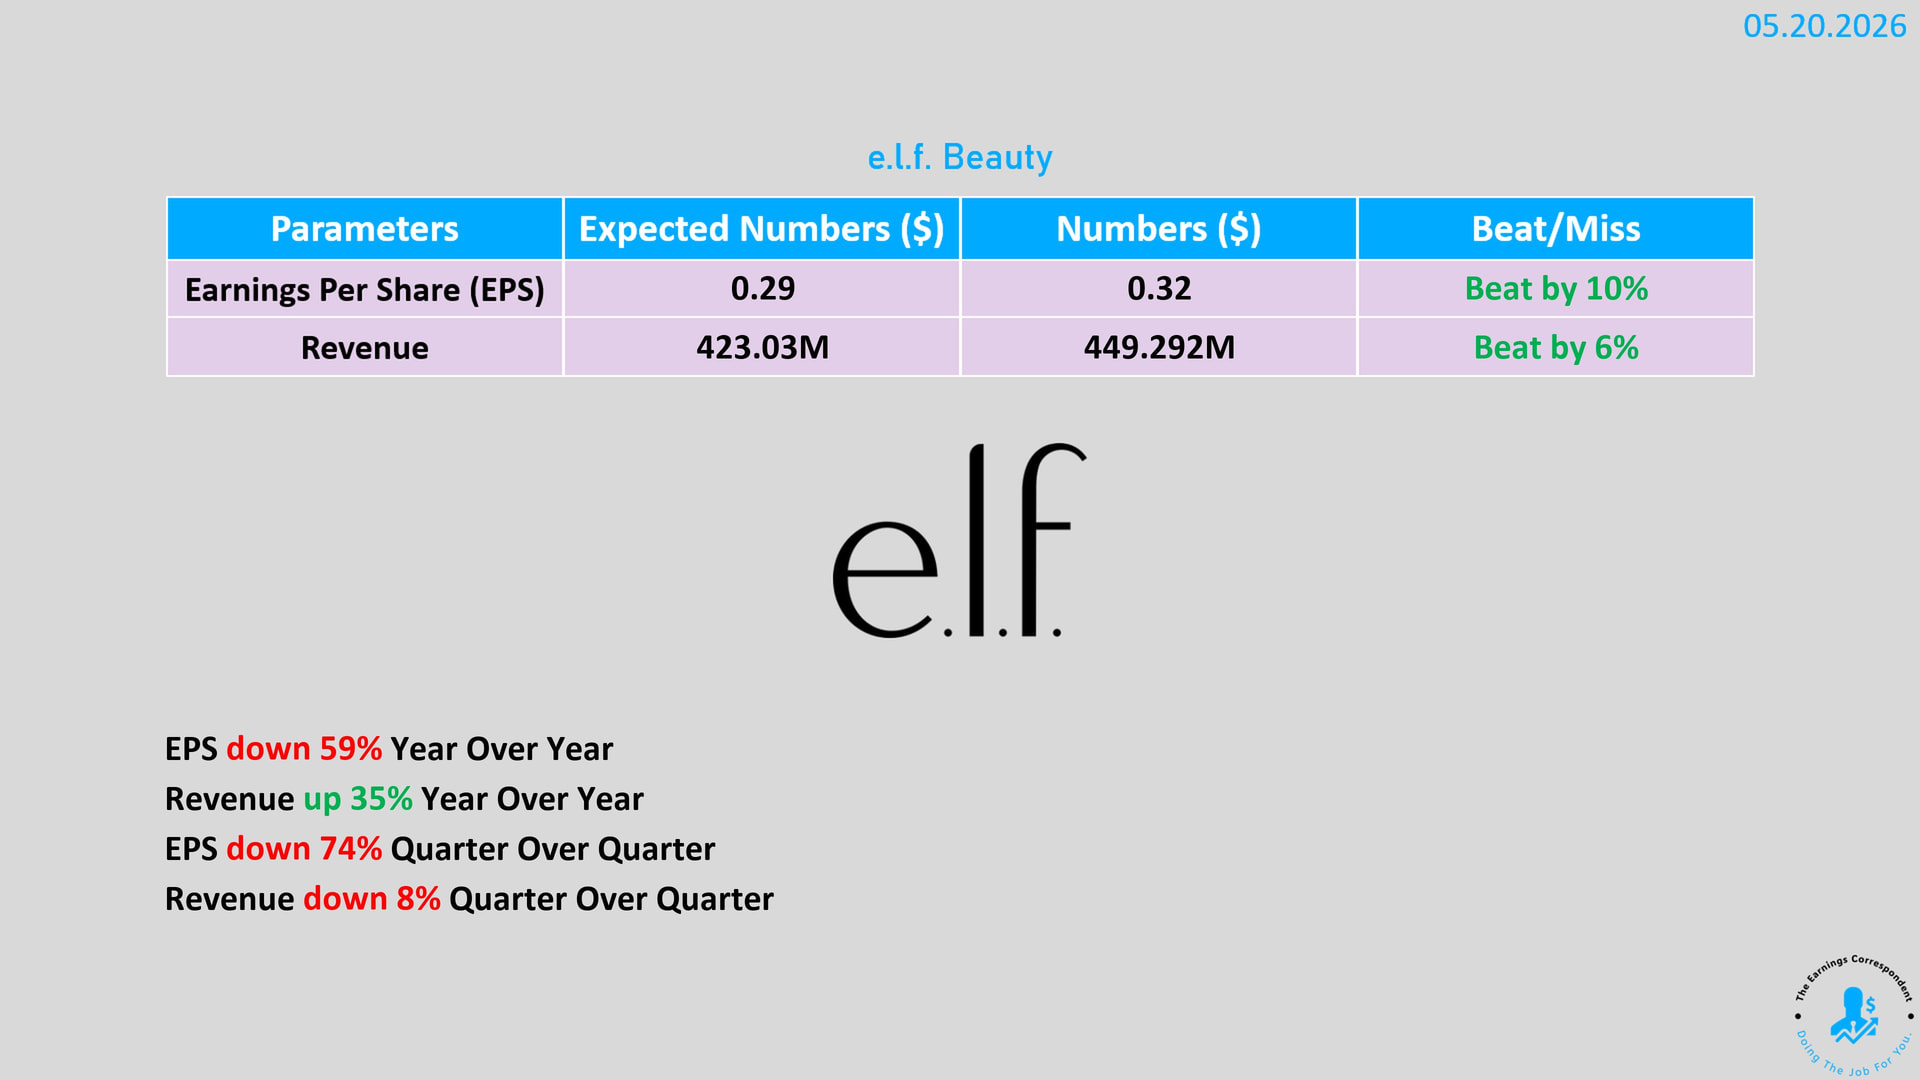
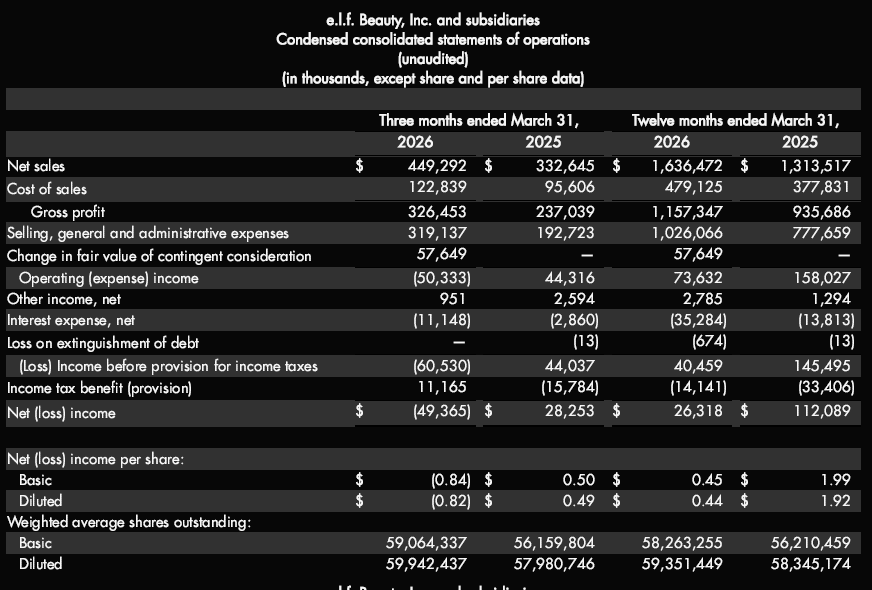
e.l.f. Beauty’s results were a mixed bag.

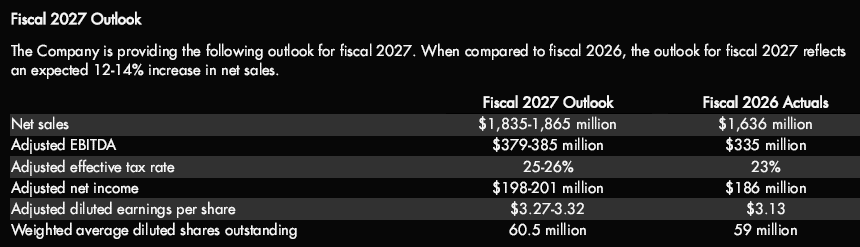
Revenue grew strongly in both brick-and-mortar and e-commerce, exceeding expectations, and adjusted earnings were also slightly better than forecasts. However, the earnings guidance for 2027 fell short of market expectations.

https://x.com/earnings_guy/status/2057190933859311625


And here is a bit more on the same topic:

E.l.f. intends to lower the prices of some of its products to stimulate faded demand.

The company raised its prices last year due to tariffs, but the weakening of consumer purchasing power has reduced sales volumes. E.l.f. performed better than expected driven by its Rhode brand, and the company’s future earnings guidance fell short of expectations.

Despite the price cuts, the company expects tariff refunds, which on the other hand will support its profitability.

Key Points

  • E.l.f. Beauty plans to walk back some of its tariff-fueled price increases to offset a slowdown in unit sales as consumer have been pulling back.
  • “We’ve seen units drop off a bit more in the last few months as consumers have particularly been suffering with higher costs,” CEO Tarang Amin told CNBC in an interview. “There’ll be additional items that we will test lower pricing on to really be able to reinforce our value proposition at a time when the consumer is suffering.”
  • E.l.f.’s plan for price reductions came as it reported fiscal fourth-quarter earnings that beat expectations on the top and bottom lines.

https://www.cnbc.com/2026/05/20/elf-beauty-elf-earnings-q4-2026.html


The company’s own materials


3 Likes

I am on board with this one and I’m definitely staying put at these levels. The price has dropped to an incredibly low level by all metrics. The markets liked the results, and the stock was clearly up in after-hours trading.

2 Likes

The article below discusses E.l.f., which is growing through affordable products and social media. Three-quarters of its products cost ten dollars or less, and customer feedback is directly incorporated into product development. The article also mentions how price hikes due to tariffs ate into sales, yet subsequent price cuts only boosted demand for a few products.

The vast majority of the approximately $50 million in tariff refunds is going toward marketing, on which the company already spends about a quarter of its revenue.

Seeing what resonates with consumers and how that translates into numbers is something Fields has long been passionate about.

“I love thinking about what makes a person purchase an item,” she said. “Seeing the numbers behind it … what makes one product more successful than another? Why does this marketing work better than that? It’s just fantastic, and in the CFO seat, you see everything across the company.”

Key Points

  • E.l.f. Beauty CFO Mandy Fields says the cosmetics and skincare company has remained committed to affordability amid its rapid expansion.
  • Leveraging social media influencers is a big part of E.l.f.’s marketing strategy.
  • E.l.f. has launched several products because of the feedback it’s received through social media platforms.

https://www.cnbc.com/2026/10/16/elf-beauty-cfo-mandy-fields-tariffs-marketing-makeup.html

1 Like