The market reaction to Xplora’s Q2 report on Wednesday was -31%, and the stock is now available at its lowest price since April 2025 (closing price 24.65 NOK).
Is anyone still following this? Any comments from those familiar with the company?
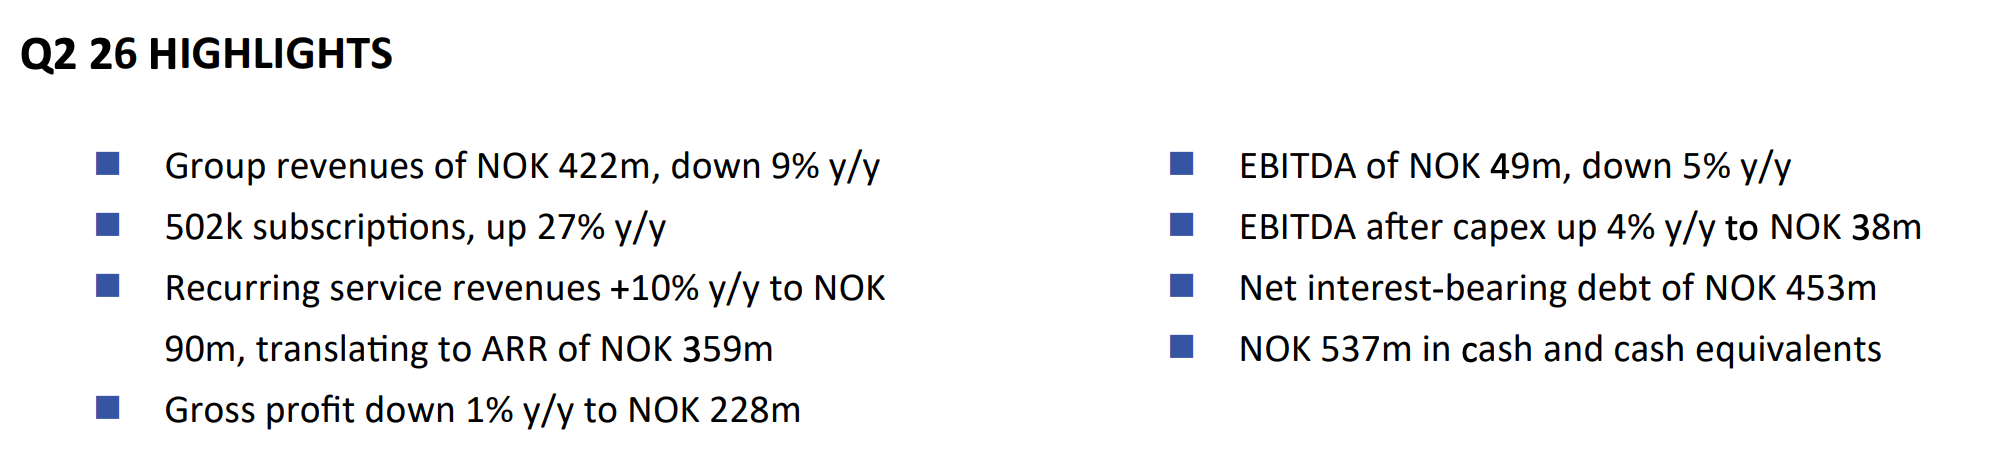
A decline in revenue is, of course, a slightly negative trait for a growth company. However, the press release (Xplora Q2 26: Surpassing the half million mark on subscriptions in Q2, with H1 EBITDA after capex up 50% to NOK 56m) focuses on subscriber growth and a review of the entire H1 figures.
Subscriptions grew by 27% y/y, but ARR only by 10%, meaning ARPU decreased. Germany and other international markets are mentioned as the reason. ARR also fell compared to Q1, which seems like a bit of a bad sign. According to Redeye, the thesis for the senior segment took a hit.
From the CEO’s comments:
Xplora remains, first and foremost, a growth company. A key strength of our business strategy is its ability to adapt to changing consumer market conditions. When consumer demand softens, we place greater emphasis on protecting margins and operational efficiency, while continuing to expand our recurring revenue base. During the second quarter, our subscription base reached 502k subscriptions. We added 28k subscriptions in the quarter, increasing the subscription base by 108k, or 27% year-over-year. While the Nordic subscription base continues to grow, most new subscriptions are generated in Germany and other international markets, where ARPU is slightly lower. Service revenue increased by 10% year-over-year and annual recurring revenue (ARR) reached NOK 359m. EBITDA amounted to NOK 49m in the quarter and NOK 76m for the first half of 2026.
From the press release:
During the quarter the company executed key strategic initiatives to continue the progress towards the target of 1 million subscriptions. By signing an SPA for the acquisition of emporia Group, a market leader in senior mobile phones in the DACH region, Xplora strengthened the foundation for the roll-out of subscription services in the Senior segment, as well as defining natural markets for exploring new MVNOs. In addition, the company also launched the pilot for the retail point-of-sale (POS) system through a Nordic retail partner in late Q2 26. Although at an early stage, a POS system enables distribution of Xplora services through retail partners alongside device sales.
“With a growing portfolio across both the Children & Youth and Senior segments, an expanding Xplora Connect ecosystem, more than half a million subscriptions, and a broader international footprint, we are well positioned to deliver long-term profitable growth. Our focus now is on disciplined execution to realise the full potential of this platform,” says Kirkbak.
Redeye’s quick comment (free, but requires login):
Xplora (Initial take Q2): One pilot store complete with Power
Redeye reads Xplora’s Q2 2026 as a volume miss with margins intact. Group revenue of NOK422.0m fell 9 per cent y/y and came in below every published estimate, with the shortfall almost entirely in Senior devices, while gross margin rose to 54 per cent and EBITDA excluding one-offs held at NOK61m against NOK60m. Subscriptions and service revenue landed where the July pre-announcement implied, but ARR fell sequentially to NOK359m and grew 10 per cent y/y against subscriber growth of 27 per cent. The quarter damages the 2027-28 senior services thesis. Senior subscriptions are the product of device volume, attach rate and store count: this print took device volume down and leaves the store count far below what a full August rollout implied, so the two inputs compound rather than offset. Redeye expects the shares to be marked 10-15 per cent lower.
Before the report, the average target price from two analysts was 65 NOK (the share price was ~36 NOK before the collapse on the day of the results). It will be interesting to see those after the updates.
After the market closed, it was also announced that the CEO and CFO had been shopping.