If most of the assets are tied up in a single company, I believe it’s a matter of diversification. At least that’s how I would act myself and not keep all my eggs in one basket.
In addition to that, they most likely also sold a later block of 2 million shares in equal parts, meaning a large reduction for both.
Good scenario: They are relatively young individuals who cashed in their first million after taxes into their own account. According to a quick Google search, they didn’t have any other significant direct assets, so this could be very sensible risk management now that buyers were found, regardless of their view on the company’s future. On the other hand, based on their surname (it was mentioned on the Sijoitustieto forum that Rebecca’s maiden name might also be Koivukoski), a fairly strong weight in the company will remain in the future while waiting for a potential inheritance. So I really don’t know if there is a direct family relation to the Chairman of the Board, but there might be.
Bad scenario: Both are employees of the company with a fairly good view of the company’s situation, even though neither is at the executive team level. In their work, they have drawn the conclusion that the future doesn’t look very rosy and have started selling.
Everyone can draw their own conclusions as to which scenario is at play, or if it’s something else. At first, I was even quite positive about those large block trades; I consider the good scenario quite possible. But now that the buyer(s) of the blocks seem to have been acting mostly with a trading mindset—meaning they have already dumped a large portion of the blocks back to the market on a spread of a few percent—it’s hard to remain very positive about this. It would have been quite positive to get some breadth among the company’s significant owners, but now the shares seem to have ended up mostly with retail investors via a detour.
6 Likes
Tekova would be quite a tasty bite to swallow for, say, a serial consolidator at the current valuation level. Larger construction companies could also acquire Tekova while keeping it as a separate subsidiary. Perhaps this would bring the “longer track record” desired by analysts. I wouldn’t be surprised if Tekova gets swallowed up at some point. Although the currently substantial dividend curiously encourages holding Tekova. As a “family-owned” company, Tekova will surely continue to take care of a good dividend in the future.
8 Likes
[quote="Alamaki, post:323, topic:56159"]\nLarger construction companies could also acquire Tekova while keeping it as a separate subsidiary\n\n[/quote]\n\nI was actually thinking about this myself when those block trades started happening more frequently—that someone like Lujatalo or Lapti could have been building a stake with the idea that Tekova’s concept would bring them competitiveness in the data center market, which, combined with a strong balance sheet, could enable even large-scale data center contracts. In theory, an acquirer here could have paid off the investment with just a couple of contracts in a couple of years.\n\nBut well, this turned out to be just daydreaming, as it really looks like the blocks have largely already moved to new hands, meaning a long-term major buyer wasn’t found after all.
2 Likes
Today, clear retail-driven (?) selling with an accelerating pace towards the end of the day. After all, Tekova’s employees have bought shares with loan money granted by the company, and the loan repayments are quite likely timed for the end of the year. I would guess today’s seller fits this profile.
Large owners are not selling on the screen, that has already been proven quite well.
6 Likes
If the subscription price for employees was originally €0.122/share, you wouldn’t expect such heavy selling pressure for loan repayments at the current valuation.
1 Like
One could similarly think: why would anyone need a loan if the subscription price was so low? The loan still has to be paid back, and few employees likely have tens or hundreds of thousands in extra cash now, just as they didn’t at the time of the subscription.
2 Likes
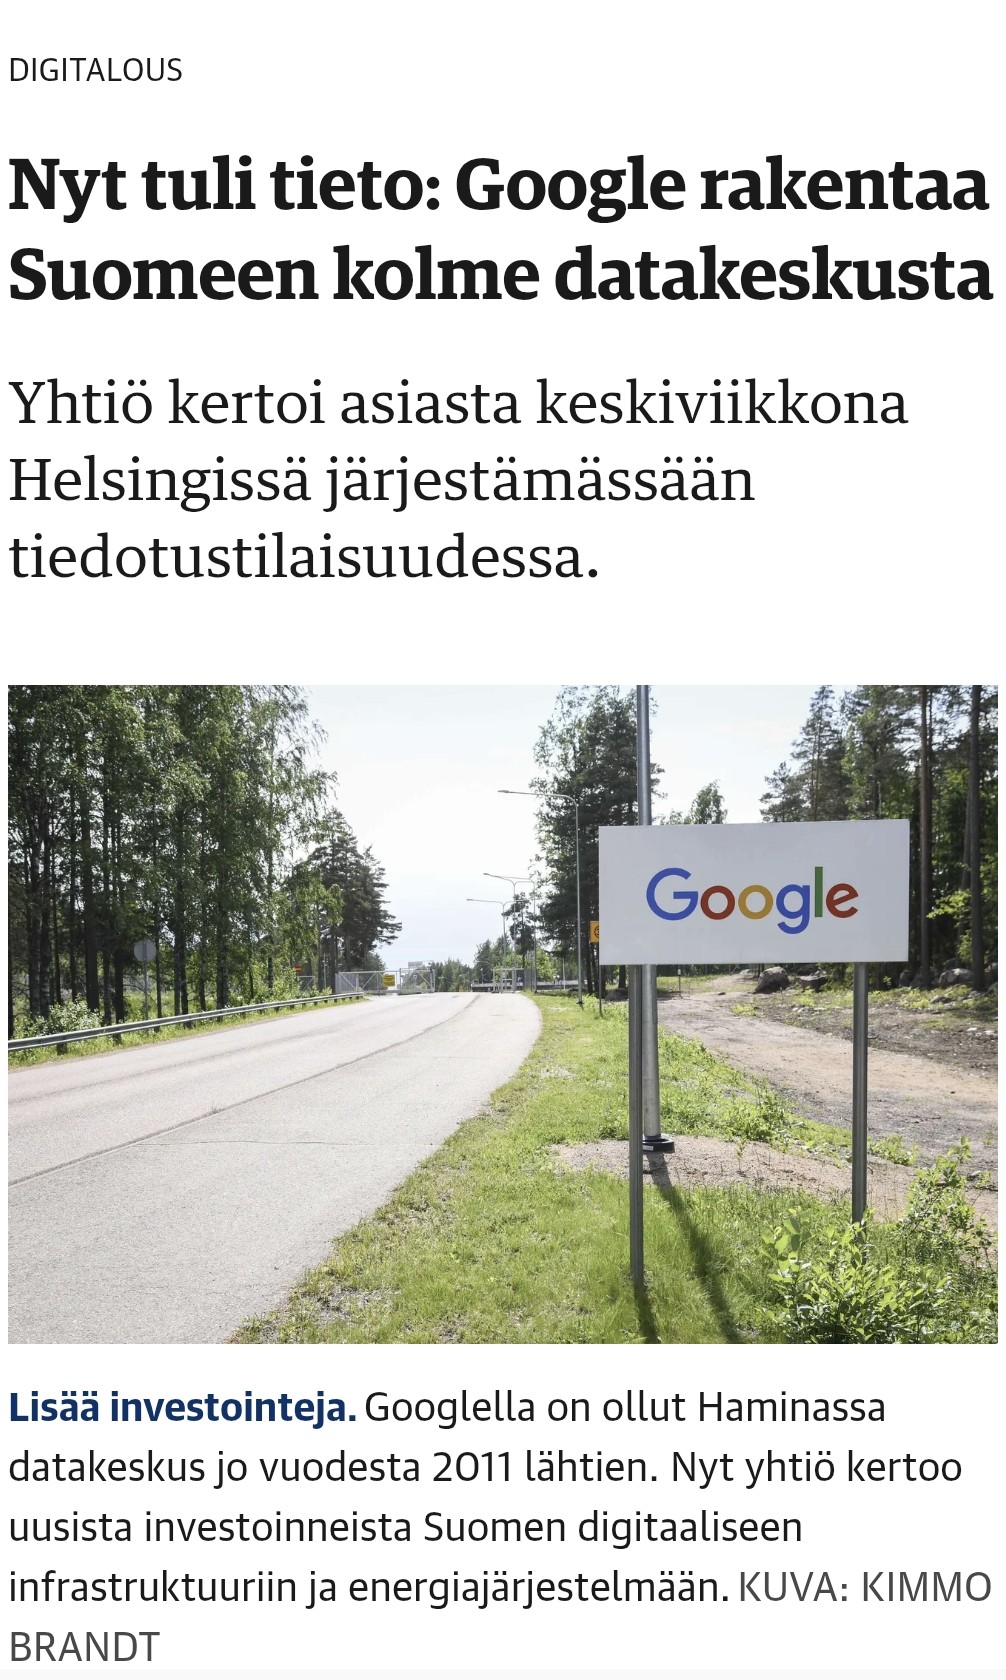
There is an article with a picture in Kauppalehti today. Do you think even a few crumbs of these investments could end up in Tekova’s basket? What do you wiser folks think?
2 Likes
Indeed, the old large owners apparently aren’t selling on the order book, but those shares certainly look like they’ve ended up there via a detour after all. In other words, large owners sold their shares in block trades to traders, who have been rapidly unloading their positions with a steadily shrinking spread.
Hardly anything to do will drop to Tekova from these projects, unless they end up in a subcontractor role, which they probably don’t have much of a craving for, at least with typical contract models. These are simply too big projects for Tekova’s size class.
However, it can certainly have an indirect impact in that these eat up the resources of large companies and can thus leave Tekova with more opportunities in individual construction projects in the < €50M range. These data centers are popping up at such a pace now that even the resources of YIT, SRV, and company cannot stretch to everything when they have other work to do as well. After this Google news, it already makes one want to say that if Tekova doesn’t secure a single data center project into a contract within the next 6 months, it will be a major failure in this market situation.
13 Likes
That’s a very good point: when larger players direct a big chunk of their resources towards bigger available projects, it leaves smaller ones for players of Tekova’s size. In any case, it really perks up the sector.
2 Likes
[quote=“ollikohan, post:329, topic:56159”]
Nämä on ihan liian isoja hankkeita Tekovan kokoluokkaan.
[/quote>
Let me correct myself a bit. When comparing Google’s newly announced €13B investment to Nebius’s Lappeenranta project (~€8.5B and 310 MW investment), scaled directly like this off the top of my head, Google could now be looking at a total of around 470 MW, which would also align well with the PPA agreement announced with Fortum (50% of Loviisa is ~500 MW). This is calculated very roughly at a high level; 1 MW can cost a very different amount depending on what exactly is being done, but calculated off the cuff like this, the order of magnitude could be something like that.
However, Google’s investment is split across four different locations/data centers, meaning an even split would yield ~100–150 MW per center. Nebius’s expansion project in Mäntsälä contracted by Tekova was 50 MW, and this brought in a solid €30M+ in billings for Tekova. So, again calculated off the cuff, each of those four Google centers could be roughly double to triple the size of Mäntsälä in terms of construction work, putting the scale at €50–100M. The lower end of this is actually at a level that Tekova could handle after all, assuming Google doesn’t bundle the projects into a single contract.
So I wouldn’t completely rule out the possibility of Tekova getting to build some of these Google centers either. I still don’t think it’s likely, but perhaps it is possible after all.
4 Likes
Hmm, I wonder if it’s even a good thing to get into data center projects. As far as I know, they have pretty strict contracts and delays etc. result in hefty penalty invoices. You’d think that in Finland there would be enough sports halls, Rusta, Puuilo, new warehouses, data centers (twhtsita → twh/data centers), etc. for that kind of revenue.