Christoffer Jennel:in ennakkokommentit, kun Starbreeze julkaisee Q4-tuloksensa 18.2.
We expect Q4 revenue to remain at a low level with somewhat challenging year-on-year comparisons due to the timing of the PD3 launch. We also expect continued cash flow pressures in the quarter due to negative earnings and high investment levels. There are still limited details surrounding PAYDAY 3’s (“PD3”) second year and therefore management’s commentary on this topic will be of particular interest in the Q4 report, as well as the latest development of Project Baxter. While we still see 2025 as a transitional year for PD3, the agreement with KRAFTON alleviates cash flow pressures, putting the company in a stronger position for its 2026 release. Given the currently low expectations for PD3, as reflected in the valuation, any meaningful uptick in player activity could provide support for the share price at current levels.
Here are Christoffer’s comments on the Q4 results.
EDIT:
Replaced with the Finnish version that came later:
Starbreeze’s Q4 revenue and operating profit were largely in line with our expectations, with revenue being slightly higher, although this was solely due to earlier-than-expected revenue from the KRAFTON partnership. In addition, PD3’s revenue was significantly below our forecasts, and management did not provide concrete information on 2025 plans to address the game’s persistently low player activity. At the same time, Starbreeze appears to be making progress in Industry discussions with potential Project Baxter partners, although final agreements have not yet been made.
Jennel has made a new company report on Starbreeze.
"Automatic translation: Original published in English on 2/19/25 at 9:22 AM. Please note that the automatic translation currently covers only this text and may contain errors. You can provide feedback on the quality of automatic translations and potential errorshere.
Revenue and earnings were in line with our forecasts, although the revenue distribution was somewhat surprising. No concrete information was provided on PAYDAY 3’s (“PD3”) second-year plans, as they are still being planned and discussions with potential Project Baxter partners are ongoing. The current share price reflects very low market expectations, and as short-term financial risks decrease, we believe this offers a potential opportunity for contrarian investors with a high risk tolerance. We reiterate our Add recommendation and raise our target price to SEK 0.24 (previously SEK 0.22)."
Starbreeze repurchases the publishing rights for Payday 3 from PLAION through a directed share issue. The value of the issue is approximately SEK 33 million.
Dilution for existing shareholders is 9.1% and 5.4% of voting rights.
Good solution and Embracer takes a strategic position as an owner, if only they can turn the game’s dismal player numbers around for better figures on the bottom line.
These rights acquisitions had not gone unnoticed even by Cristoffer.
Our initial reaction to today’s announcement is mixed. On the one hand, gaining full control of PAYDAY 3 could be beneficial for the company as it offers greater agility and decision-making freedom. On the other hand, the increased financial and operational risks could be a negative factor if the game’s performance continues to falter. Additionally, while we view the addition of a reputable shareholder like Embracer to be positive, the dilution, giving up nearly 10% of the company’s equity to finance the transaction, is somewhat excessive in our view.
The cash situation looks a bit worrying, but Starbreeze doesn’t seem concerned at all. Was there already a new IP title in the works?
As a positive sign, I looked at PD3 statistics. Player numbers are still low, but perhaps the latest update will give it a boost, and the content has started to attract players compared to a year ago. The game has sold copies, however, and SB has frequently run discounts on the game.
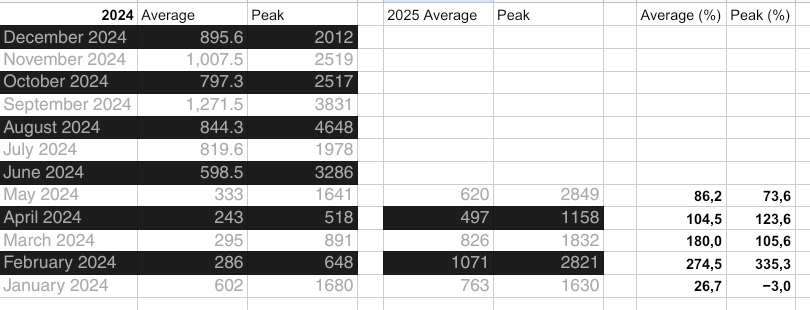
The PD2 situation, compared to last year, showed a player decline, but not a massive one. The fact that these players have not fully transitioned to the newer installment suggests that the bitterness among PD2 veterans runs deep.
An interesting situation is at hand, now that the PD rights have been regained and there’s also some recovery in PD3 player numbers.
Opportunity for a turnaround?
Payday rights in Starbreeze’s hands
Content has improved and there’s a small turnaround in player numbers.
The departure of PD2 players doesn’t significantly impact revenue, but the transition to PD3 hasn’t fully materialized.
Cash is weak, but the arrival of a new anchor owner increased confidence. And SB, with a new CEO, is looking forward.
Christoffer Jennel’s preview comments as Starbreeze publishes its Q2 report tomorrow.
Starbreeze will publish its Q2 report on Tuesday, August 19. We expect revenue to remain roughly stable compared to Q1, but to be significantly higher year-over-year, due to the KRAFTON partnership and the acquisition of full publishing rights for PAYDAY 3 (PD3). These factors should also boost games-related revenue. Lower depreciation and a generally lighter cost structure are expected to support a significant improvement in operating profit. We expect cash flow to benefit from both improved profitability and delayed Q1 payments from game sales, which were instead received in Q2. With the completion of Project Baxter’s “vertical slice” at the end of May, we will be looking for updates in the Q2 report on potential partnerships and general development progress. We also expect clarity on PD3’s future development/roadmap, especially now that Starbreeze owns the full publishing rights to the game.
Third-party publishing accounted for SEK 6.7 million (8.8).
Work-for-hire accounted for SEK 19.6 million (0).
EBITDA* amounted to SEK 5.9 million (8.1). Taking into account items affecting comparability for the current period, EBITDA amounted to SEK 13.3 million.
Cash flow from operating activities amounted to SEK 39.2 million (2.7).
Depreciation, amortization and impairment amounted to SEK 30.8 million (78.9).
Profit/loss before taxes amounted to SEK -25.4 million (-70.6).
Basic and diluted earnings per share amounted to -0.02 SEK
(-0.05).
The period January-June 2025
Net sales amounted to SEK 121.5 million (96.8).
PAYDAY 2 accounted for SEK 20.4 million (20.1).
PAYDAY 3 accounted for SEK 50.8 million (45.3).
Third-party publishing accounted for SEK 10.1 million (26.2).
Work-for-hire accounted for SEK 37.2 million (0).
EBITDA* amounted to SEK 21.6 million (56.6). Taking into account items affecting comparability for the current period and the comparative period, EBITDA amounted to SEK 42.5 million (36.7).
Cash flow from operating activities amounted to SEK 27.4 million (81.1).
Depreciation, amortization and impairment amounted to SEK 75.3 million (150.7).
Profit/loss before tax amounted to SEK -54.9 million (-91.5).
Basic and diluted earnings per share amounted to -0.03 SEK (-0.06).
Cash and cash equivalents amounted to SEK 156.4 million (334.6).
Cristoffer Jenner has written the text in Swedish, and AI has translated it for us Nordics:
Starbreeze’s Q2 revenue was 54 MSEK, which was clearly below our forecasts (65 MSEK). Although the share of contract work exceeded our forecasts, the revenue shortfall was mainly due to the softness of PAYDAY-related sales and a weaker-than-expected contribution from the 3PP title Roboquest after its platform expansion. PAYDAY 3’s revenue was particularly soft, at 18 MSEK, when our forecast was 30 MSEK. However, we acknowledge that our assumptions may have been too front-loaded regarding the timing effect of acquiring full publishing rights, which will allow Starbreeze to retain all PD3-related revenues going forward.
Despite this, we feel that the very low expectations for PD3 and the release of Baxter, reflected in the current valuation, offer an opportunity to be a contrarian. Therefore, we reiterate our Add recommendation but lower the target price to SEK 0.22 (was SEK 0.26).
And as my own comment, it’s interesting that since there’s no other concrete information about Baxter than that it’s related to D&D, it’s hard to give it any value yet
Starbreeze gives a similar comment to our own domestic company regarding the upcoming co-op shooter game
The PD3 situation is that the player count for August actually dropped to the same level as last year. Starbreeze has occasionally sold the game at discounts below the PD2
Starbreezen toimitusjohtaja Adolf Kristjansson oli Cristoffer Jennelin haastattelussa.
In this interview, CEO Adolf Kristjansson shares his reflections on the second quarter, discussing the company’s strongest achievements, the impact of recent strategic initiatives, and the ongoing development of PAYDAY 3.
Copied from Paradox (see e.g. Stellaris). Not necessarily a bad idea for these games where the pile of DLCs has grown so large that most players skip them because the whole package already costs too much. It’s an open question how well this resonates with players. The price tag has at least been set somewhat realistically.
Well, that went strongly again. Starbreeze discontinues the development of the new AAA game Baxter and focuses on Payday development.
Starbreeze Sharpens Focus on PAYDAY Franchise — Baxter Discontinued as Part of Strategic Shift
Starbreeze AB (publ) today announces that it will discontinue development of Project Baxter. Following a strategic review, the Board of Directors and management have concluded that resources are best deployed to accelerate the growth of Starbreeze’s flagship PAYDAY franchise. The decision results in a non-cash impairment of approximately SEK 255 million in the third quarter of 2025 related to previously capitalized development costs. The write-down reflects disciplined portfolio management, ensuring that investment is concentrated in projects with the greatest long-term value creation potential.
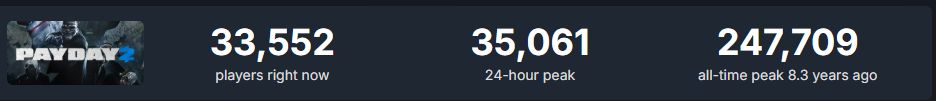
Payday2 player counts are at a quite reasonable level, but Payday3 is still a complete disaster.
–
I stated the following already in April 2024 and still agree, although in the meantime the company has significantly depleted its cash on the failed Baxter project and Payday3 life support.
Here are Christoffer Jennel’s comments regarding the news of Starbreeze rejecting Baxter.
On Thursday, Starbreeze announced the discontinuation of Project Baxter and a refined strategy. This is a significant strategic change, as Baxter had been a key part of the company’s diversification efforts. Going forward, resources will be focused on accelerating the PAYDAY franchise. In the near future, the decision will trigger a non-cash impairment of approximately SEK 255 million in Q3’25 and a reduction of approximately 44 full-time equivalents (FTEs). Management expects to achieve positive cash flow in 2026 thanks to a lower cost structure and reduced investment needs. Following this news, we anticipate downward pressure on our forecasts and will return with updated forecasts in the coming days.
EDIT:
Here is a new video from the Inderes Nordic YouTube channel, where Christoffer Jennel interviewed Starbreeze’s Jonas Skantz and Adolf Kristjansson.
Here is a company report from Jennel and Riikola, made after the latest news.
The actual PDF report is in English, and the “comment section” is made by automatic translation.
Following last week’s announcements, we lower our recommendation to Reduce (previously Add) and our target price to SEK 0.15 (previously SEK 0.22). The revised strategy, including the removal of Baxter from the production pipeline, marks a decisive change in the company’s strategy and removes yet another key diversification basis from our investment story. Although contract work projects are expected to become a more natural part of operations, Starbreeze is practically returning to focusing on a single franchise, which it previously tried to move away from. While we have raised our near-term revenue forecasts for the PAYDAY franchise and contract work, the strategic reorganization removes two major titles from our forecasts, leading to a lower-than-expected base for revenue, earnings, and cash flow during the forecast period. Due to the current weak player activity, we believe that despite the low absolute valuation, the company has a lot to prove before a stronger scenario can be confidently priced in.
Hi everyone! My name is Christoffer Jennel and I’m responsible for analysis monitoring at Starbreeze. Since our forum has now switched to multilingual mode, you can ask me questions and I will participate in the discussion here.
@christoffer.jennel has given his preliminary comments as Starbreeze reports its Q3 results next week on Tuesday.
*The quarter is dominated by the announced termination of Project Baxter, which leads to a non-cash impairment charge of approximately 255 MSEK, significantly impacting the reported Q3 result. Without the impairment, we expect the adjusted operating profit to be approximately -4 MSEK, which represents an improvement from the previous year, driven by higher expected revenues and lower normalized depreciations. Revenue growth (37% y/y) is expected to be mainly due to KRAFTON’s work-for-hire partnership, but we also expect growth in PAYDAY-related revenues thanks to the acquisition of full publishing rights. Following the strategic shift to fully focus on the PAYDAY franchise, we are closely monitoring the progress of implementation, the PAYDAY (3