Polight’s Q3 results were published today, and tomorrow is the company’s tech-focused CMD. The event was “sold out” in two days, so hard facts clearly interest investors.
I’ve said this before, but I like the CEO’s style. Previous mistakes are admitted and feet are kept firmly on the ground, even though a breakthrough looming after more than 20 years is within reach. Earnings calls are more than just running through dry, bland numbers. In hockey they talk about advanced stats, but they equally emphasize the importance of the eye test. For me, the earnings call is just like that.
The most essential part of the Q3 release is here:
Although poLight’s revenue in the quarter was low, and a fraction down on the same period last year, market activity remains buoyant.
AR|MR is not the only area offering opportunities. We also see attractive potential in the industrial segment. In the longer term, other significant markets, such as healthcare, may also provide opportunities. For the present, however, we remain focused mainly on AR|MR and the industrial segment, in that order of priority.
“Buoyant” probably best translates to very lively. OEMs’ AR/MR devices are beginning to mature for the consumer segment as well. Mobile phone manufacturers are looking for a new market in the Wearables segment, which AR/MR glasses represent.
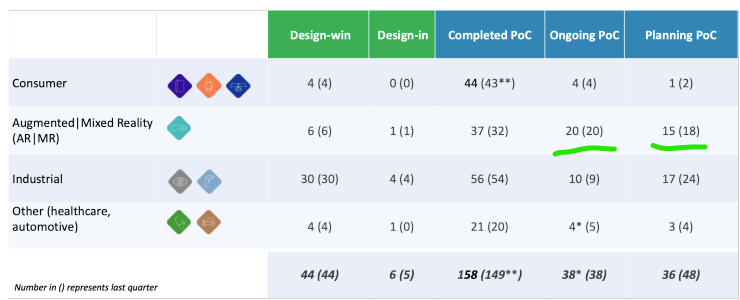
The pipeline image illustrates the liveliness of the AR/MR segment. If compared to a broader segment (Consumer/Industrial), a single narrow product group is the largest when summing up the Ongoing POC / Planning POC activities. The first AR/MR device with significant volumes is expected to reach mass production “soon”. I assume that will happen within the next 3 months.
Based on the earnings call, the device would be in the high-end category, and the sales figures the highest in Polight’s history, but of course more precise numbers are not available at this stage.
The most interesting piece of information in the Industrial segment was the following:
- Design-in related to the first industrial humanoid application. An initial smaller purchase order received (24 September 2026).
In my opinion, machine vision for robotics bolted onto a humanoid chassis will be a significant sector for Polight in the coming decade. In implementations for mobile robots, I think “auto focus” is mandatory, but at the same time one must note that Polight won’t take the entire cake with its products. VCM-based products are competitive, but one can still notch up the TAM figure.
According to the earnings call, regarding other segments, they aren’t actively selling, but are instead focusing on the most financially significant targets in the near term. The issue is not demand, but resources. There’s no need to push things by force, so to speak.
The share price initially dipped sharply, but recovered toward the afternoon. In any case, the company is moving in the right direction, and the share price will follow the upward trend sooner or later.