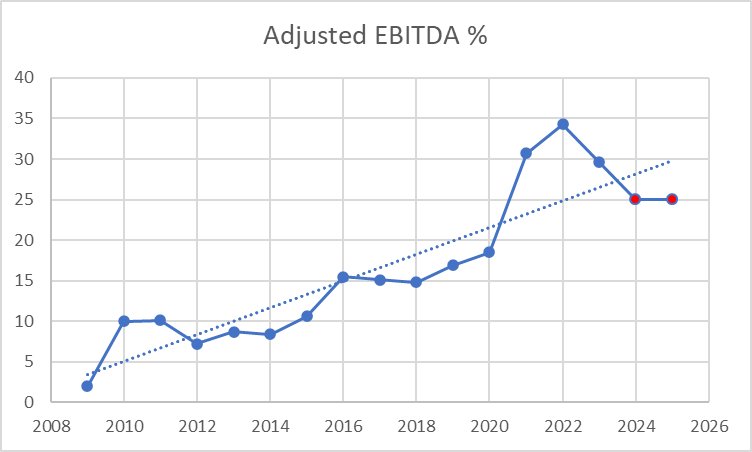
Perhaps my choice of words “structurally transformed within the last couple of years” was poor. Likewise, the company had indeed titled its slide “Structurally Improved Our Business Since IPO” (in 2016). But neither of these is strictly true, because if you look at Atkore’s EBITDA margin since 2009 (in the image below), this transformation has in a way been underway since 2010, when the company’s ownership base and the entire management changed. In this sense, the future guidance of 25% for margins (red dots) is just a consistent progression in the company’s fairly linear profitability growth once the outlier years 2021-2023 are filtered out. (This is not an inherently self-scaling business model). Therefore, it’s a bit difficult to name any single major change behind this profitability growth. Rather, it is the result of small incremental improvements made over the years, backed by systematic work, planning, and strategic execution. When things just work, and perhaps a company has the kind of corporate culture and management that just makes it work. In that case, there naturally shouldn’t be any ceiling for margin improvement.
But I will try to get that longer prose written about the company in the coming days.
EDIT: Atkore’s own thread: https://keskustelut.inderes.fi/t/atkore-inc-sahkonsuojausratkaisujen-valmistaja/44743?u=homeros