Gaming Innovation Group (STO: GIGSEK, OSL: GIG) is an iGaming company operating mainly from Malta that has grown at a rate of over 15% over the past few years with improving profitability.

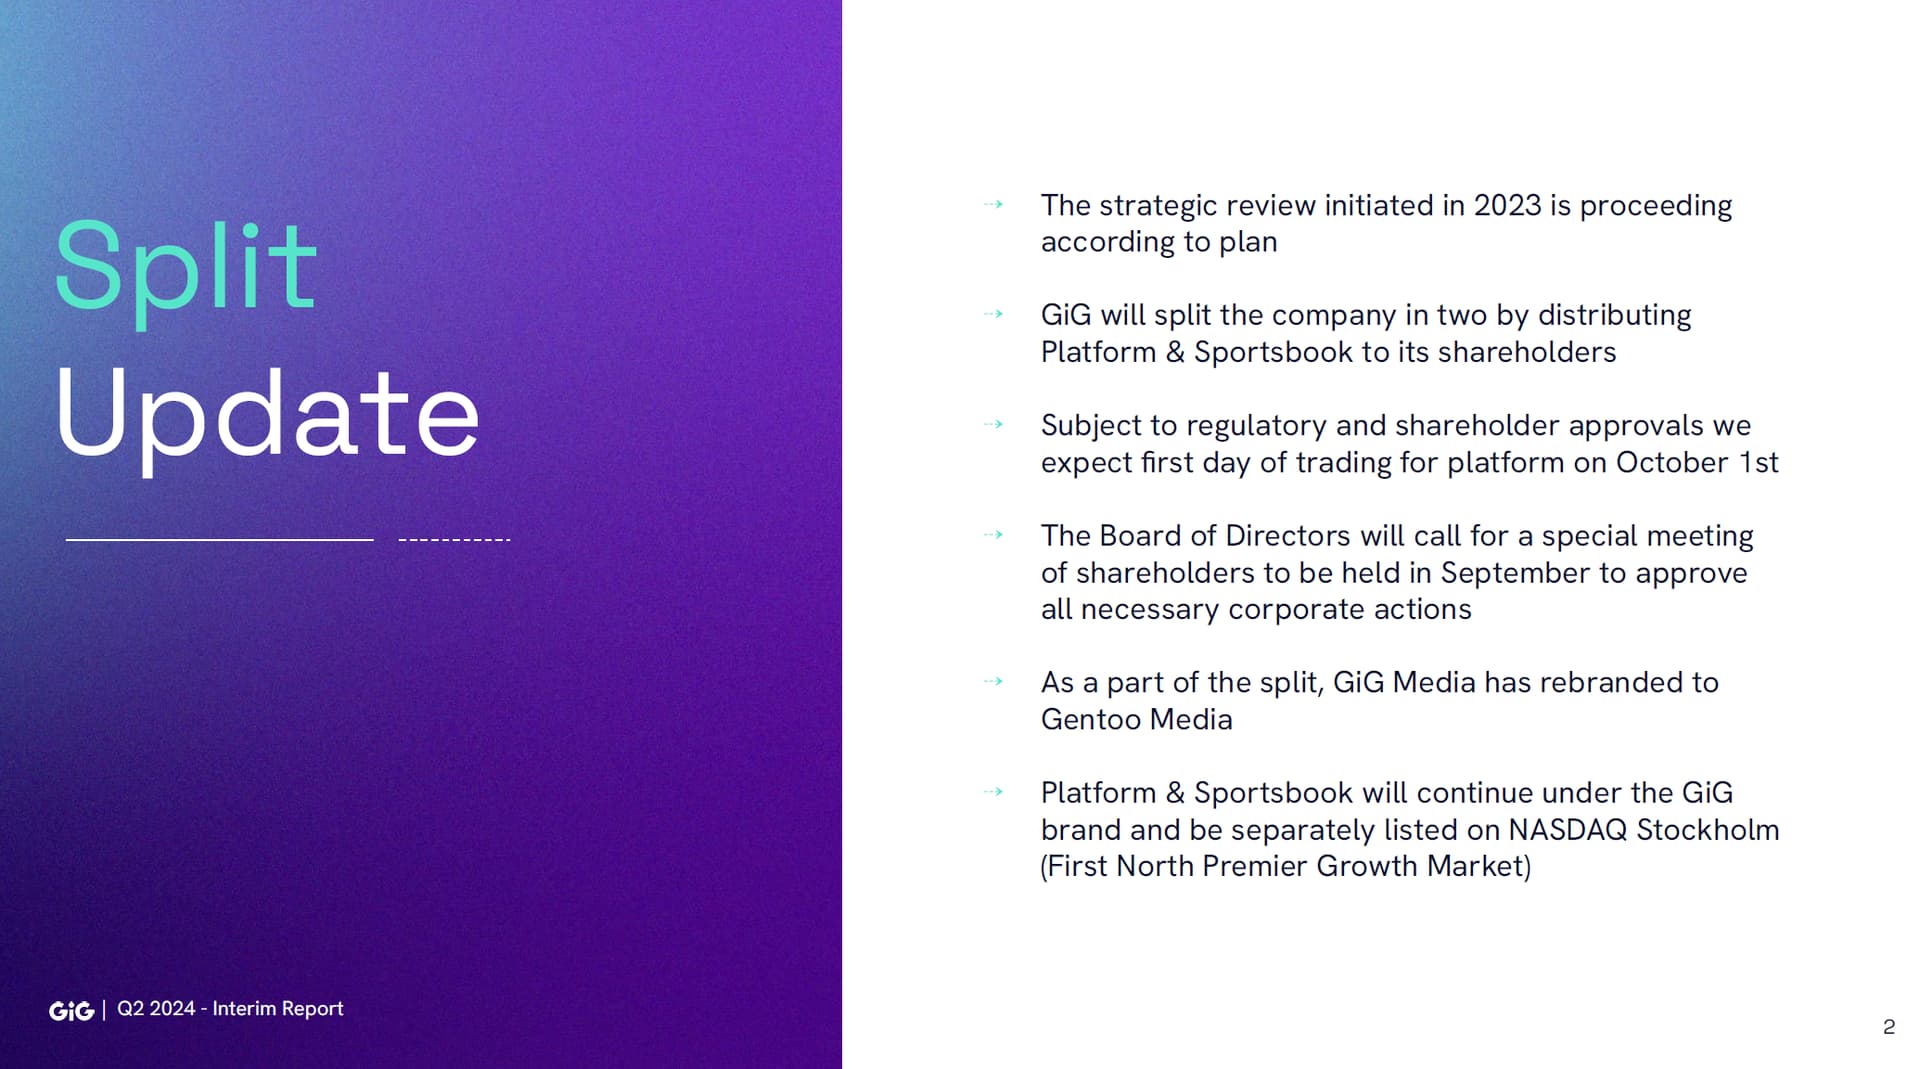
GiG consists of two business units: 1. Media and 2. Platform & Sportsbook. What makes the case particularly interesting is that GiG aims to split the (in my opinion, undervalued) units into separate companies during Q3/2024. From a valuation perspective, it therefore makes sense to treat these two separately.
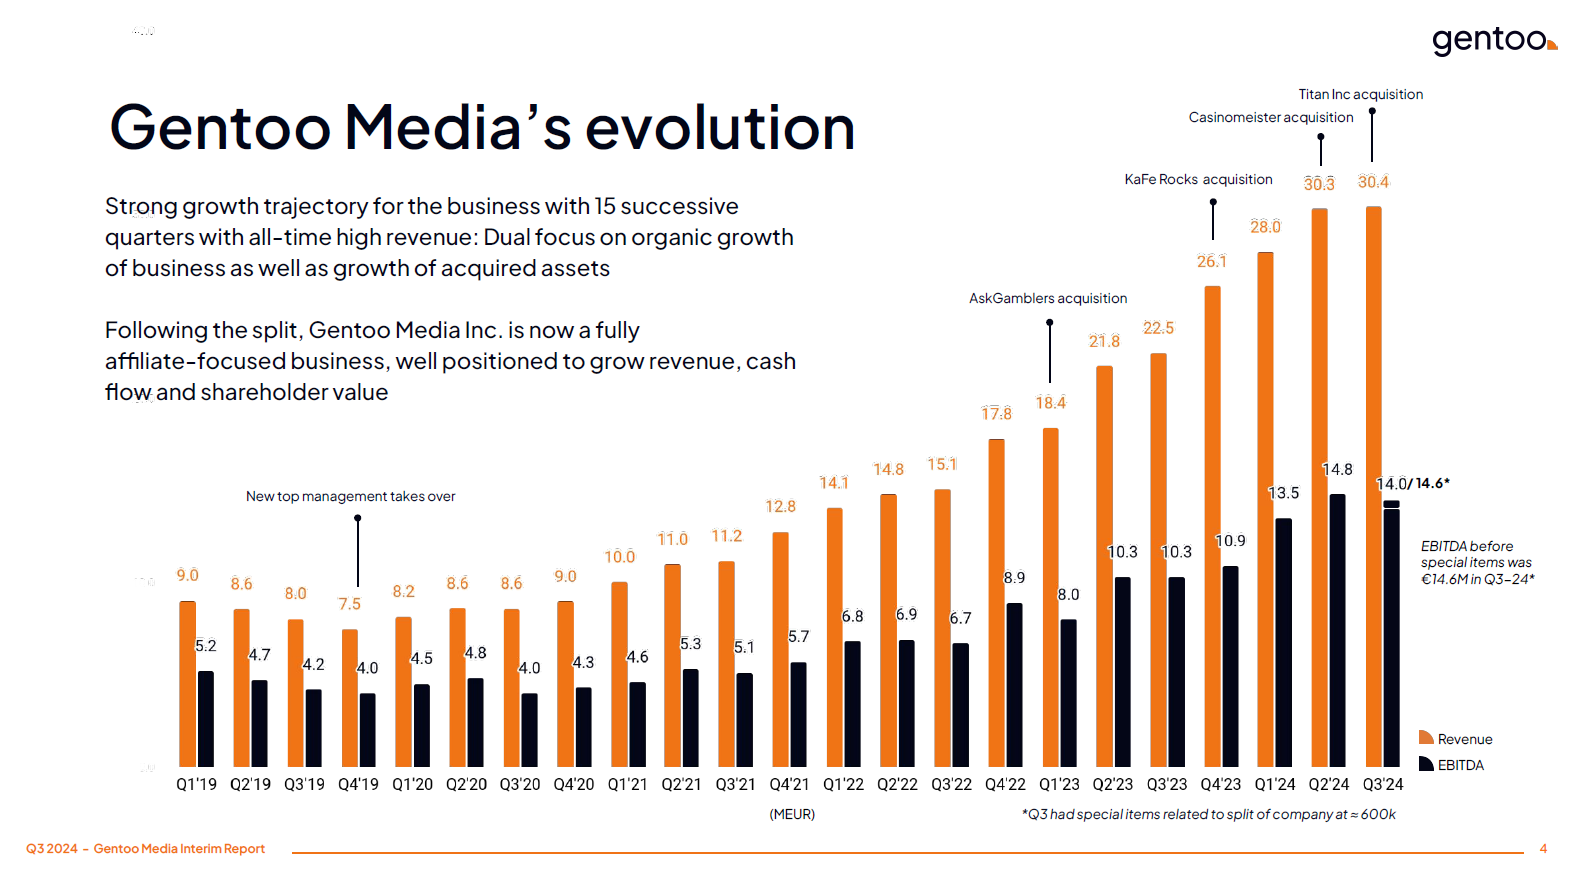
GiG Media: A serial acquirer churning out 45% EBITDA
Media focuses on the iGaming affiliate business, and it accounts for about 80-90% of GiG’s current value. Since its founding in 2015, Media has acquired affiliate assets, practically iGaming-focused websites, from which visitors are directed to become customers of online casino and betting companies. Media has about 260 employees across Europe.
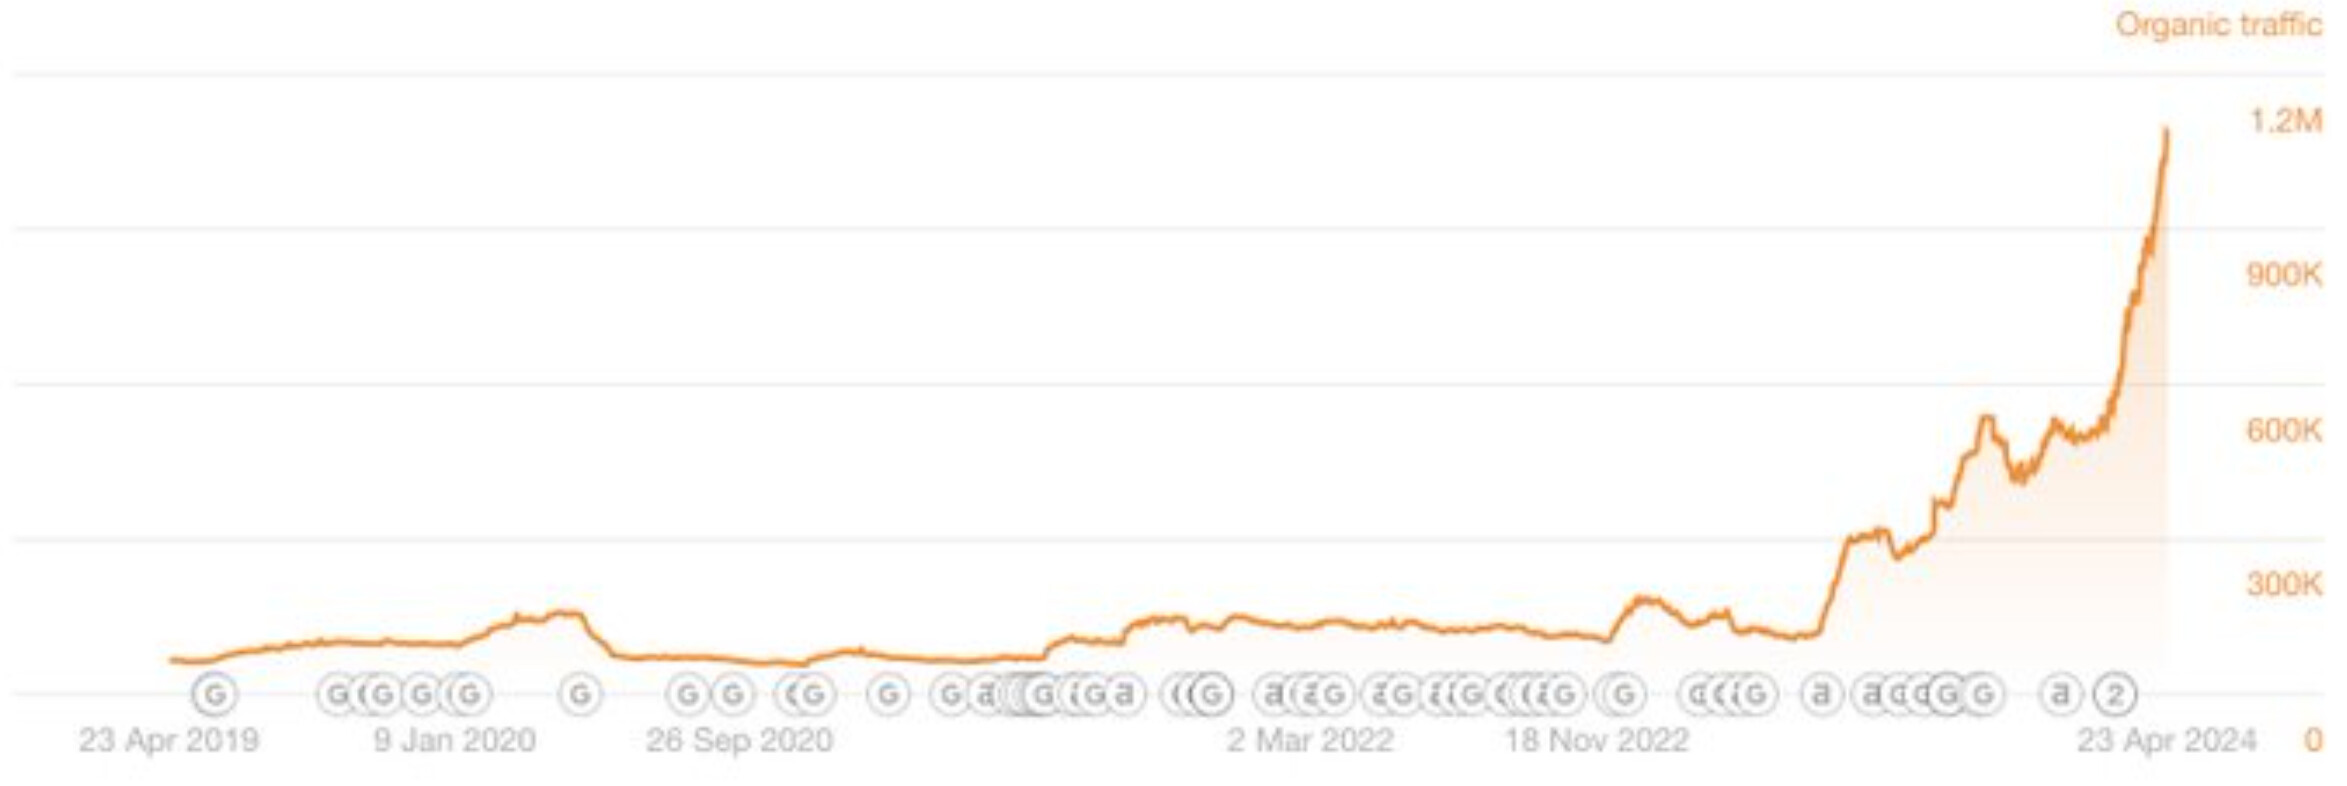
Media operates a good 100 websites, the most popular of which include wsn.com and askgamblers.com. Media also has a partnership agreement started in 2022 with the UK’s News UK, through which Media manages the betting sections of the popular media outlets The Sun and talkSPORT.
Media also offers services for the execution of marketing campaigns. About 2/3 of Media’s revenue comes from its own publishing operations (Publishing) and 1/3 from services (Paid services).
What makes Media’s unsexy business interesting is GiG’s proven expertise in acquiring affiliate assets and tuning them into prime condition. Simplified, Media buys websites at a favorable valuation and aims to strongly grow the recurring cash flow they generate.
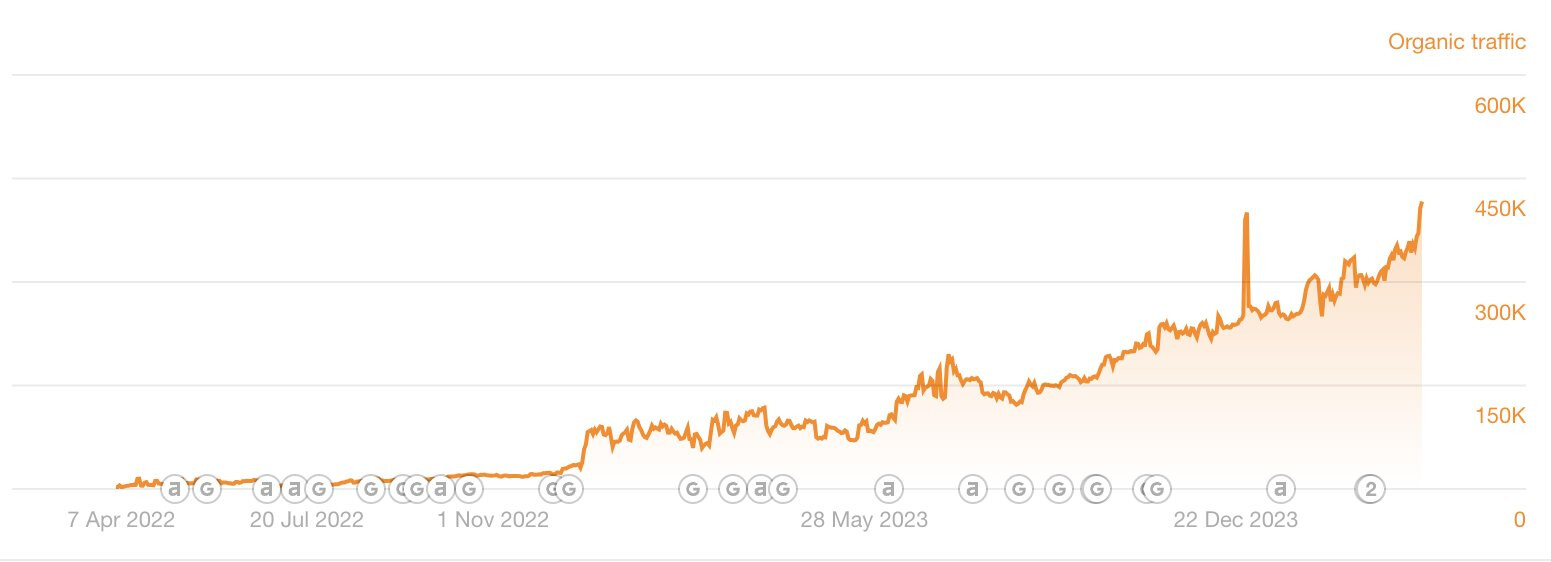
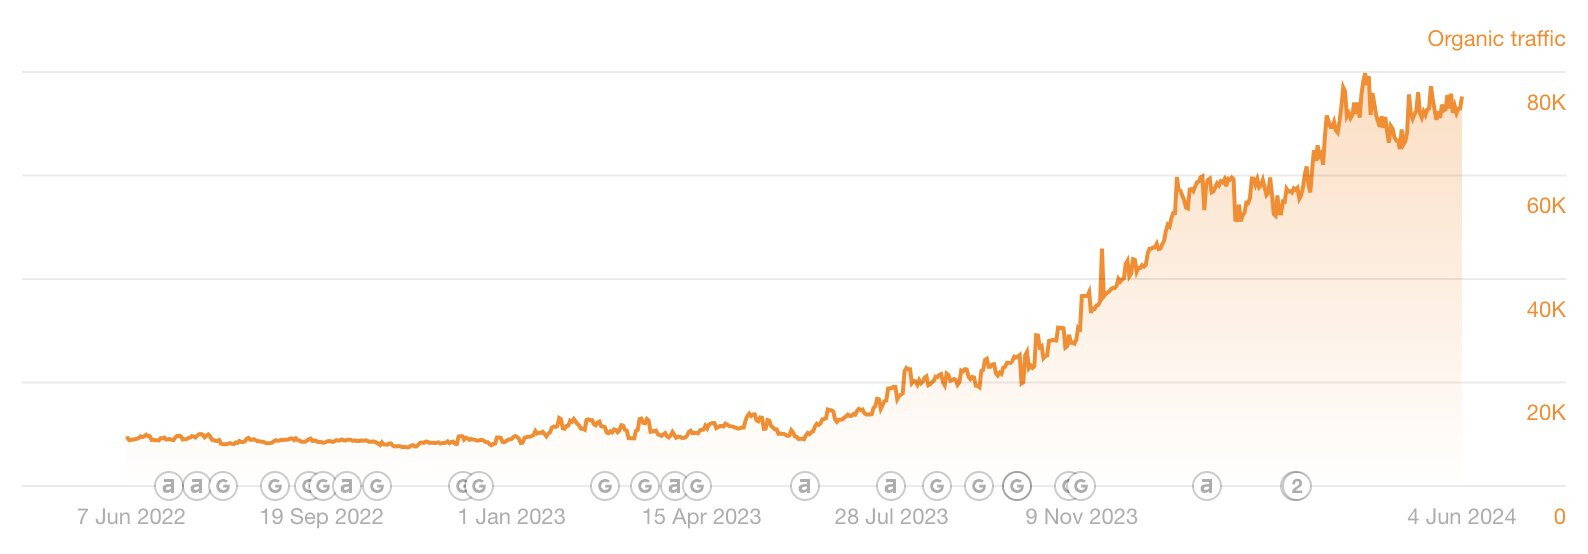
As the most recent example, GiG acquired AskGamblers from Catena in January 2023 at an EBITDA multiple of 4. Under Media, AskGamblers has more than doubled its EBITDA in under a year. In Q4, revenue grew by a further 32% QoQ and 93% YoY, and growth is expected to continue this year as Gamblers transitions to using Media’s technology platform and expands to cover the sports side as well, with the Euro 2024 football tournament and the Paris Olympics approaching.
As the newest acquisition, there is KaFe Rocks from late 2023, the development of which will be interesting to follow in the coming quarters. The company, which focuses on the US market, was acquired for 35 million euros, of which 15 million euros was paid immediately and 20 million euros over the next couple of years depending on financial development. KaFe Rocks is expected to bring in at least 10 million euros in EBITDA in 2024, meaning the acquisition’s EBITDA multiple would be 3.5.
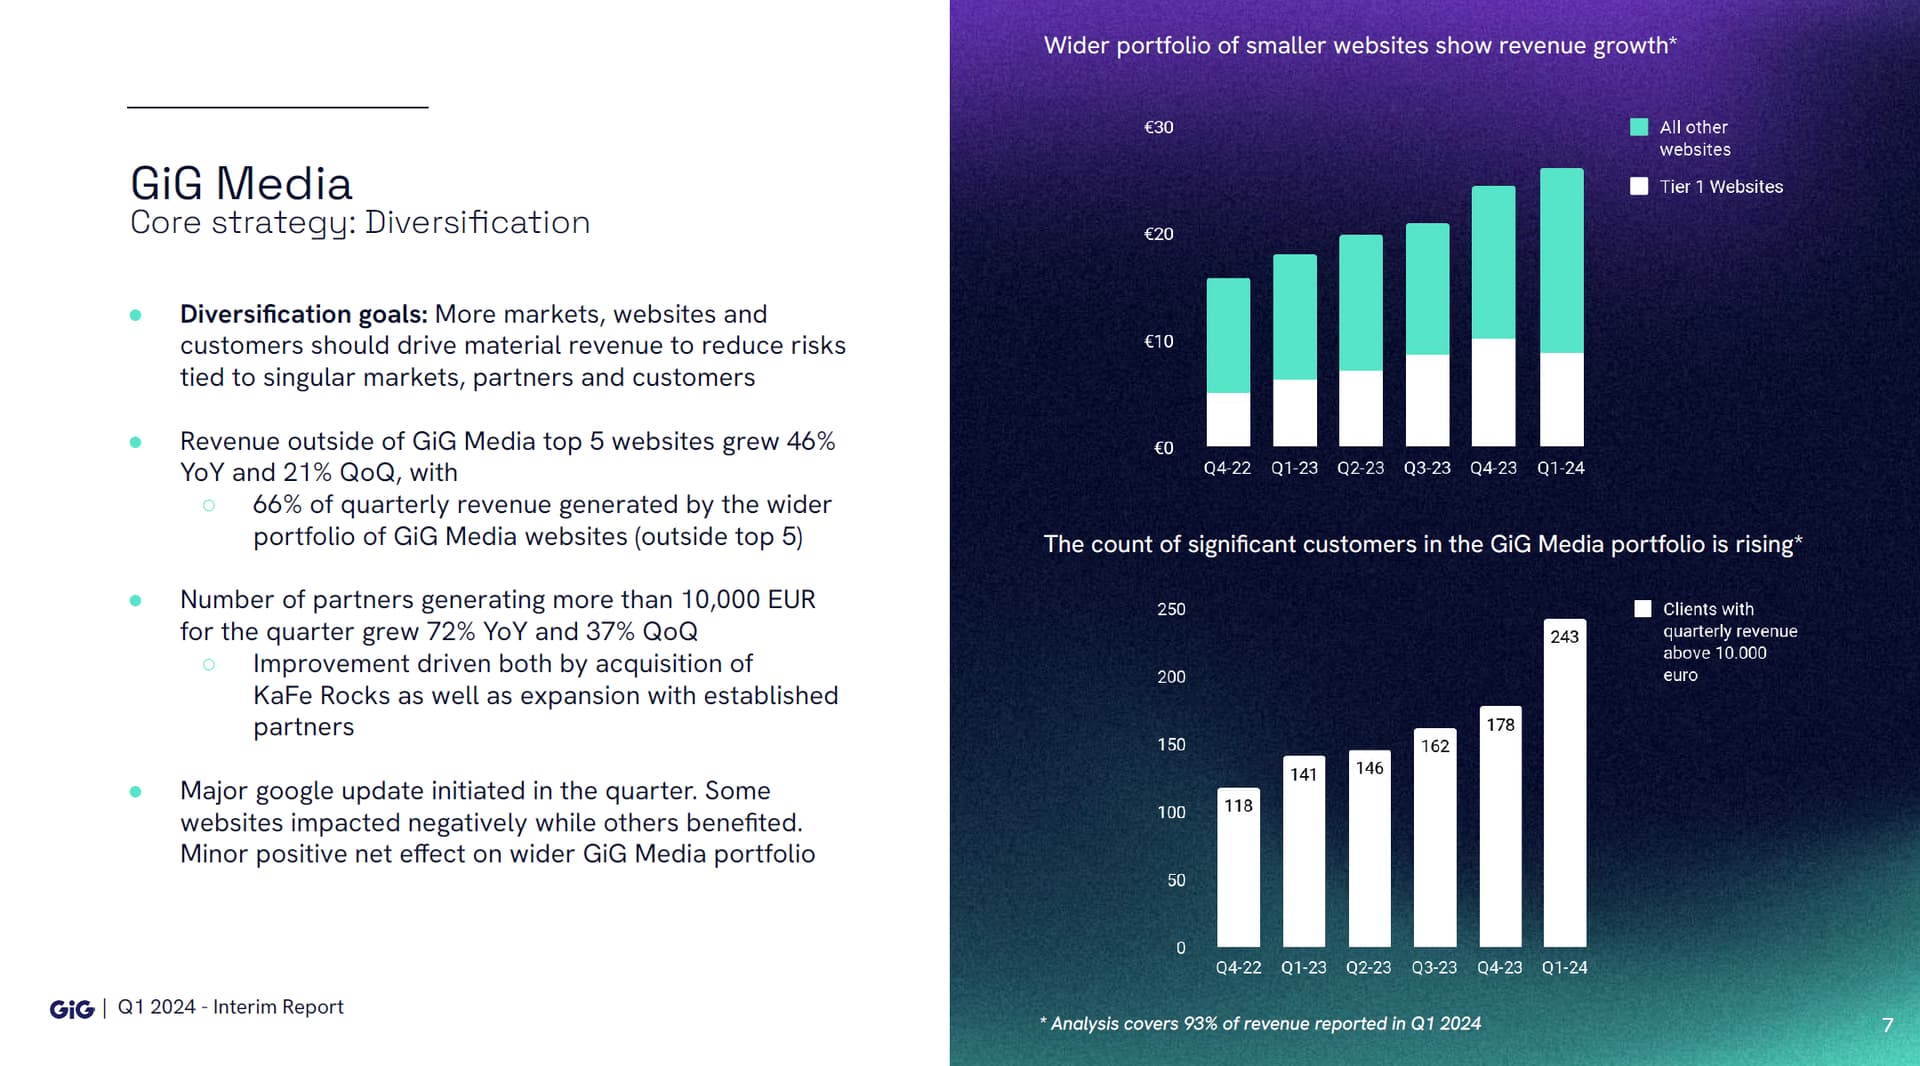
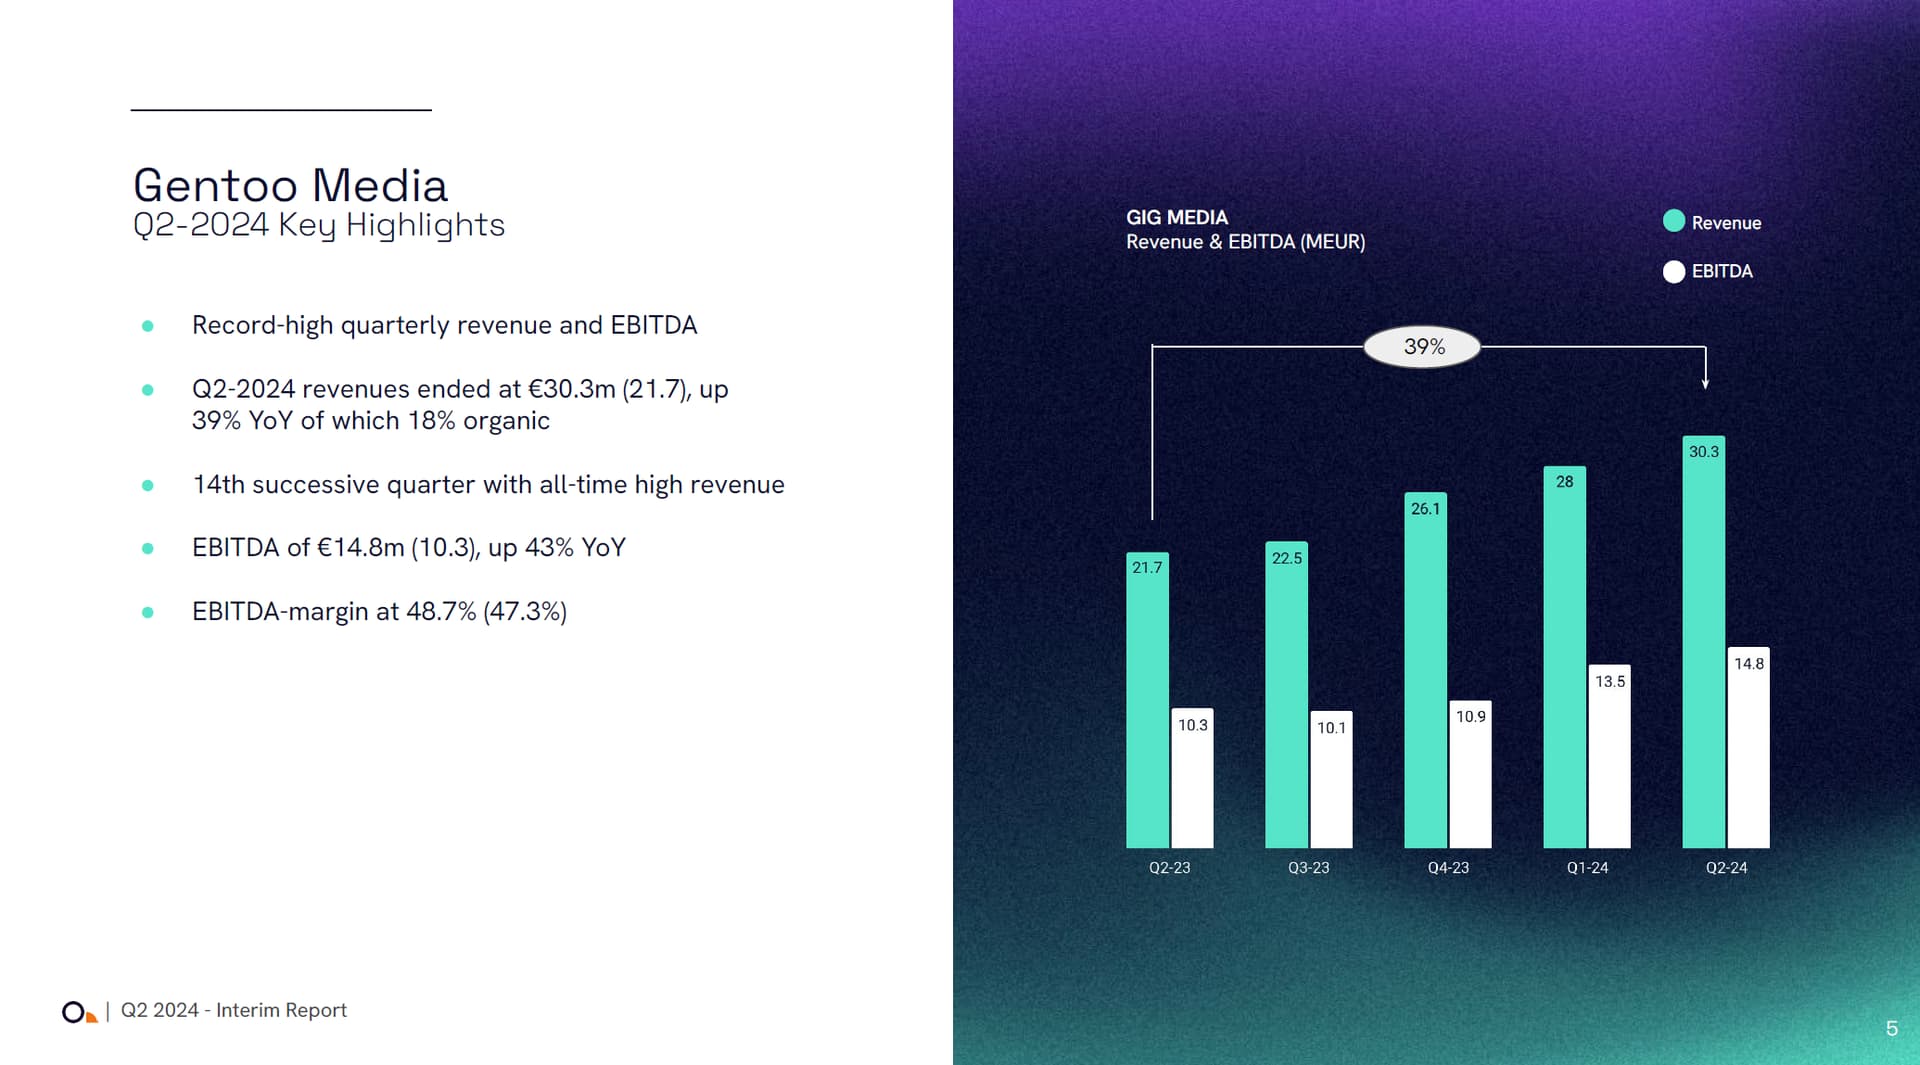
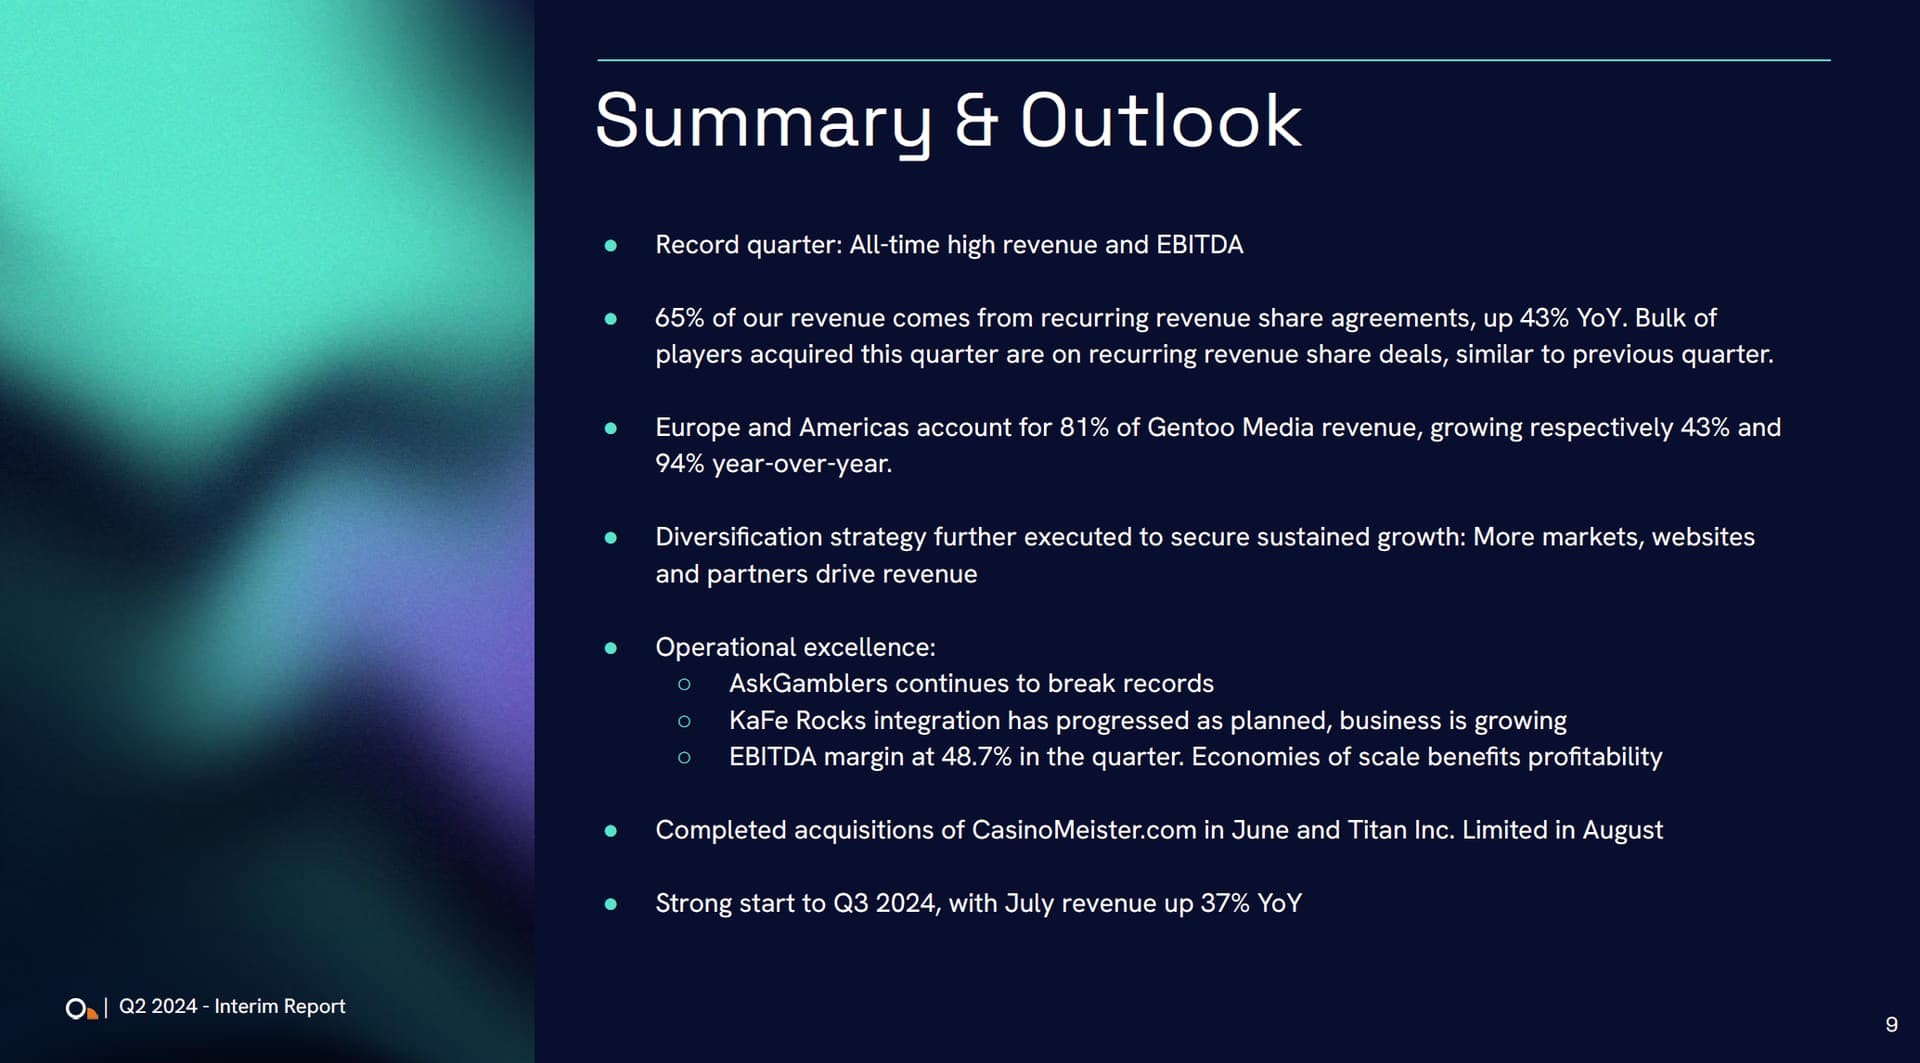
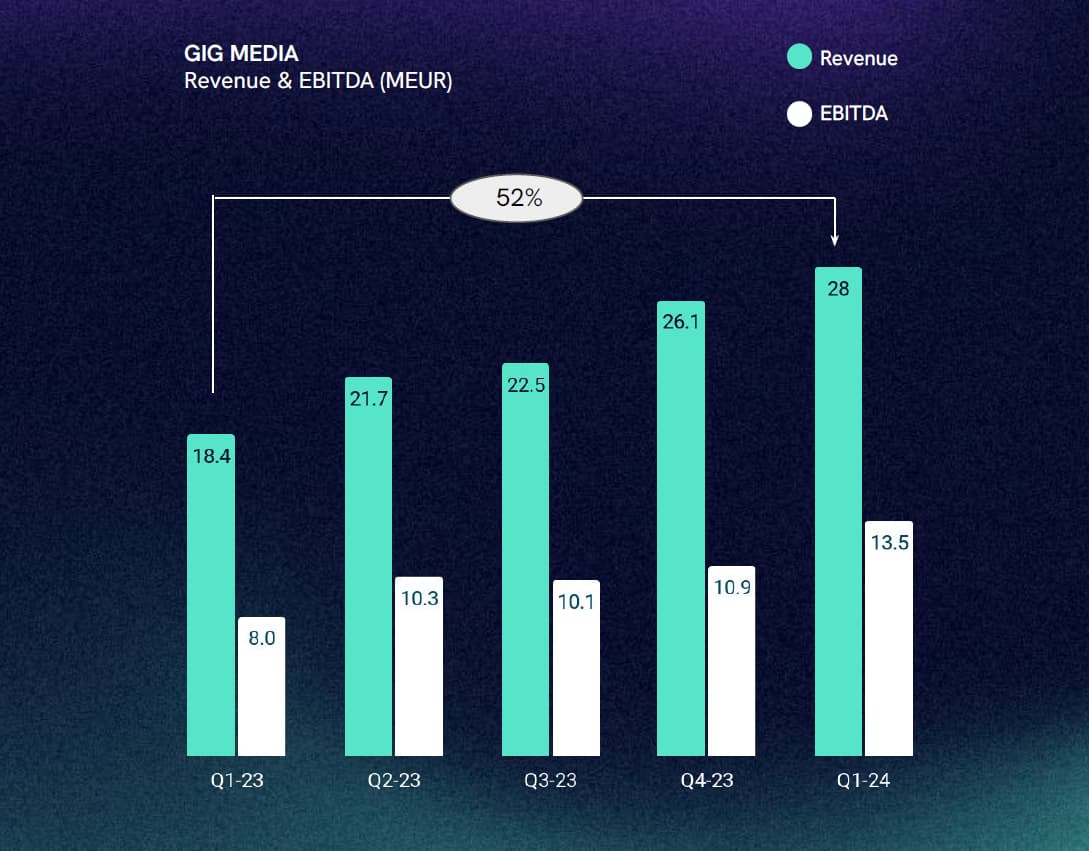
Media’s total revenue grew by 44% in 2023, of which 19% was organic. In Q1 reported this week, the corresponding figures were 52% and 21%. The number of new players (FTD, first time depositors), which acts as a leading indicator, grew by 13%.
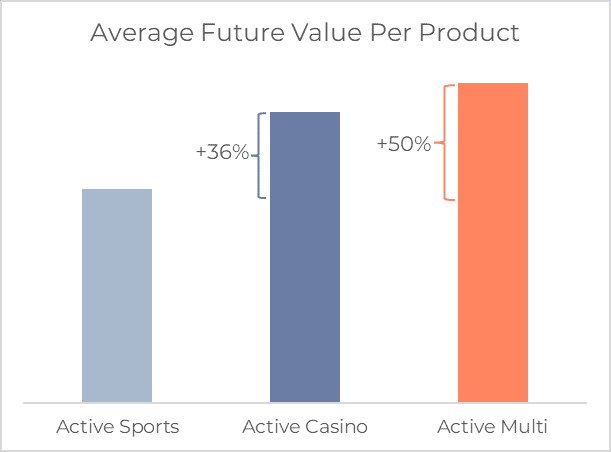
63% of Media’s revenue comes from revenue share, 10% on a cost per acquisition basis (i.e., a one-time fee), and 27% from other services. Revenue share is the most valuable of these because it is recurring revenue: whenever a player referred by GiG plays at an operator, a portion of the revenue is paid to GiG Media. GiG aims to further increase the share of revenue share. Operators pay GiG anywhere from 15% to 50% of the lifetime revenue brought in by the player.
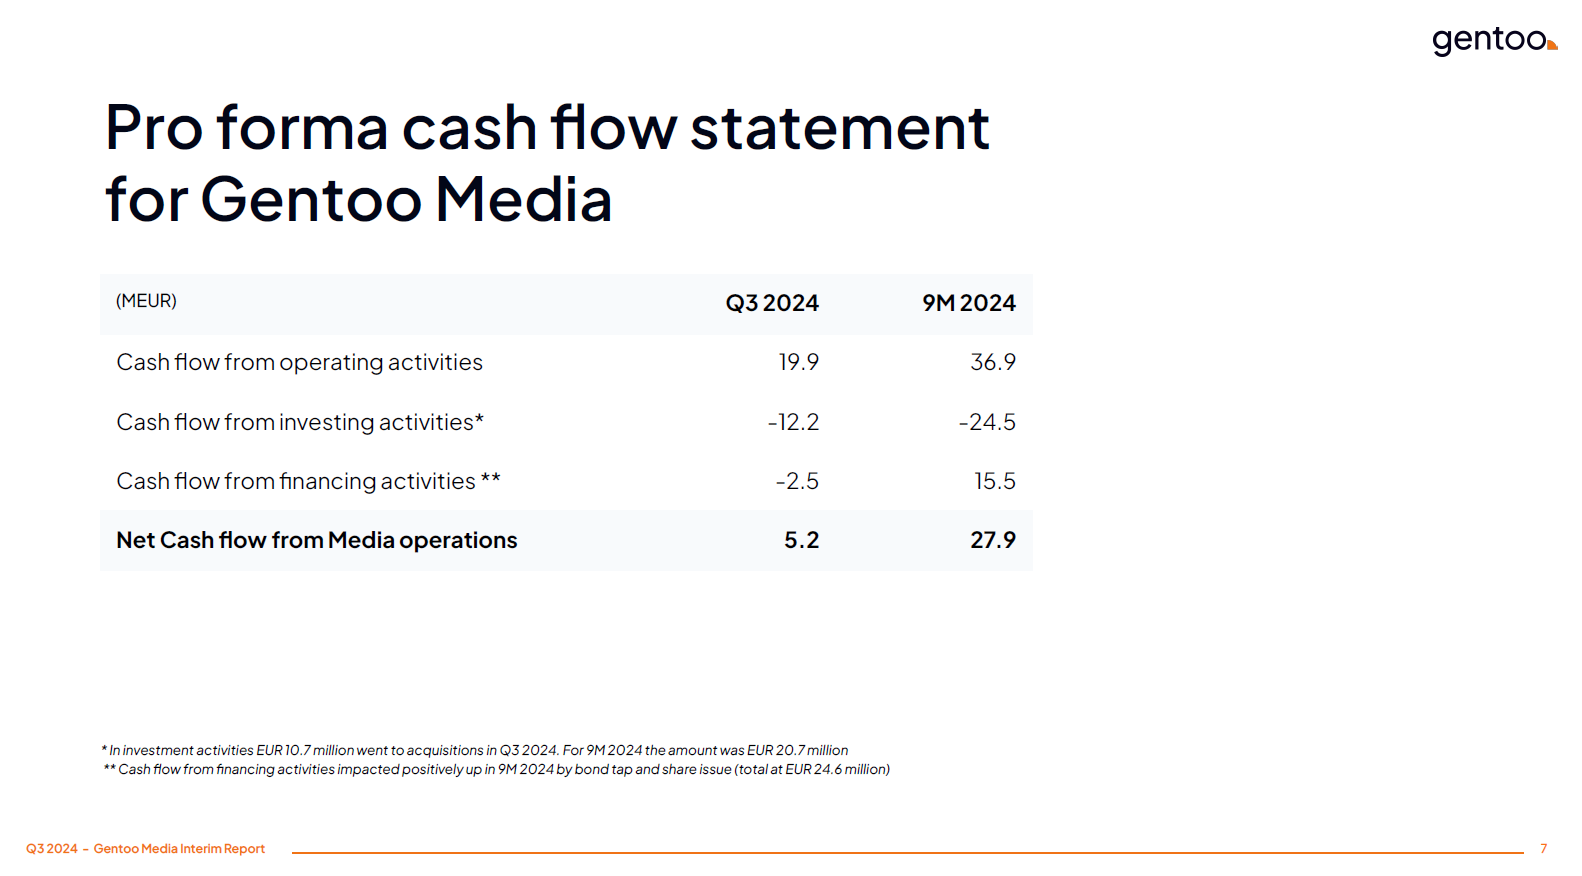
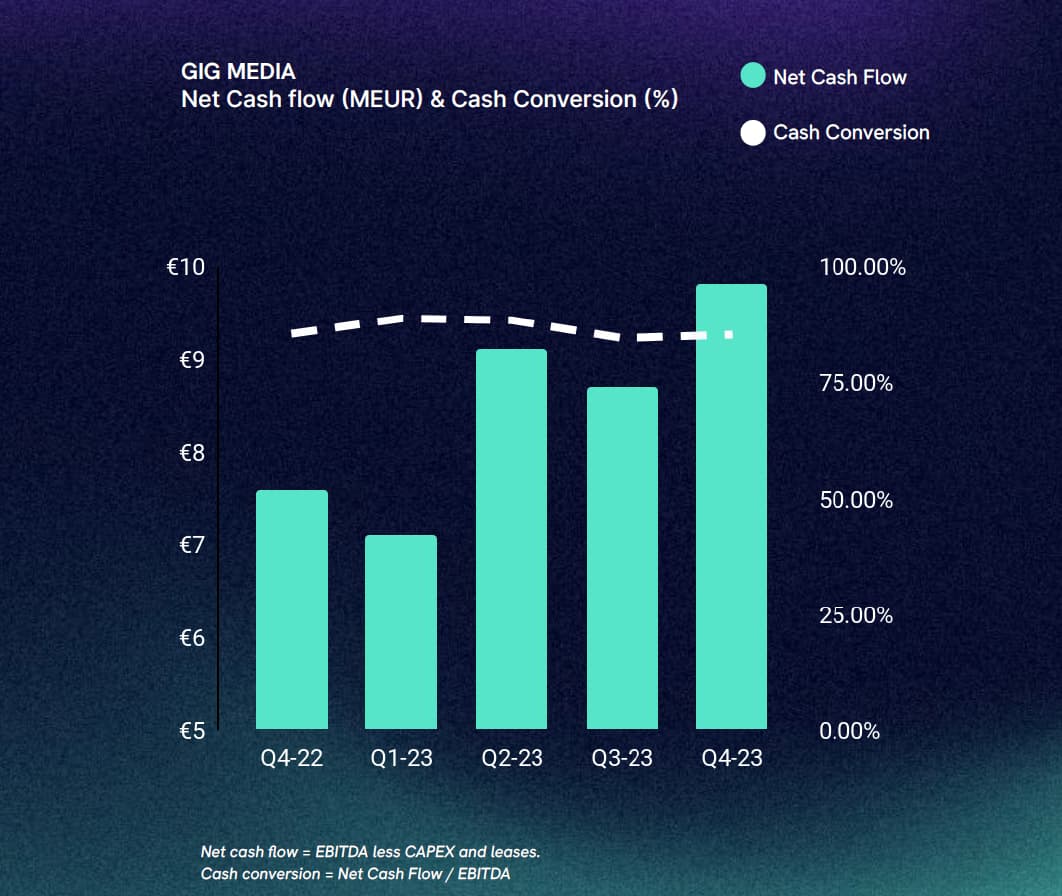
Last year, Media’s EBITDA was 45%, and EBITDA minus amortization of acquisitions was 40%. EBITDA converts at a high percentage into free cash flow. When looking at the figures for the entire group, it is also good to note where the cash flow generated by Media goes: towards (successful) acquisitions and the development of the platform side. The media business itself is therefore, at least for now, very profitable, with its cash flow being used for growth investments.
GiG Platform & Sportsbook: A potential SaaS growth company
GiG’s platform side offers a SaaS-based end-to-end platform for iGaming operators. The platform includes a user interface/website, player account management, back office, and related services, and it is available in over 30 regulated markets. GiG strengthened its overall offering by acquiring Sportnco’s sportsbook in 2022 and replacing its own sportsbook technology with Sportnco’s counterpart. There are about 450 employees on the platform side.
P&S is interesting for the same reasons as many B2B SaaS companies: revenue is recurring, switching costs for the customer are high, and the service provider’s margin is (presumably) high at a mature stage.
The platform takes about 2.5%-3% of the operators’ net gaming revenue, and the Sportsbook takes about 8-10%. GiG also offers the platform on a subscription billing model, at a monthly price of a few tens of thousands of euros.
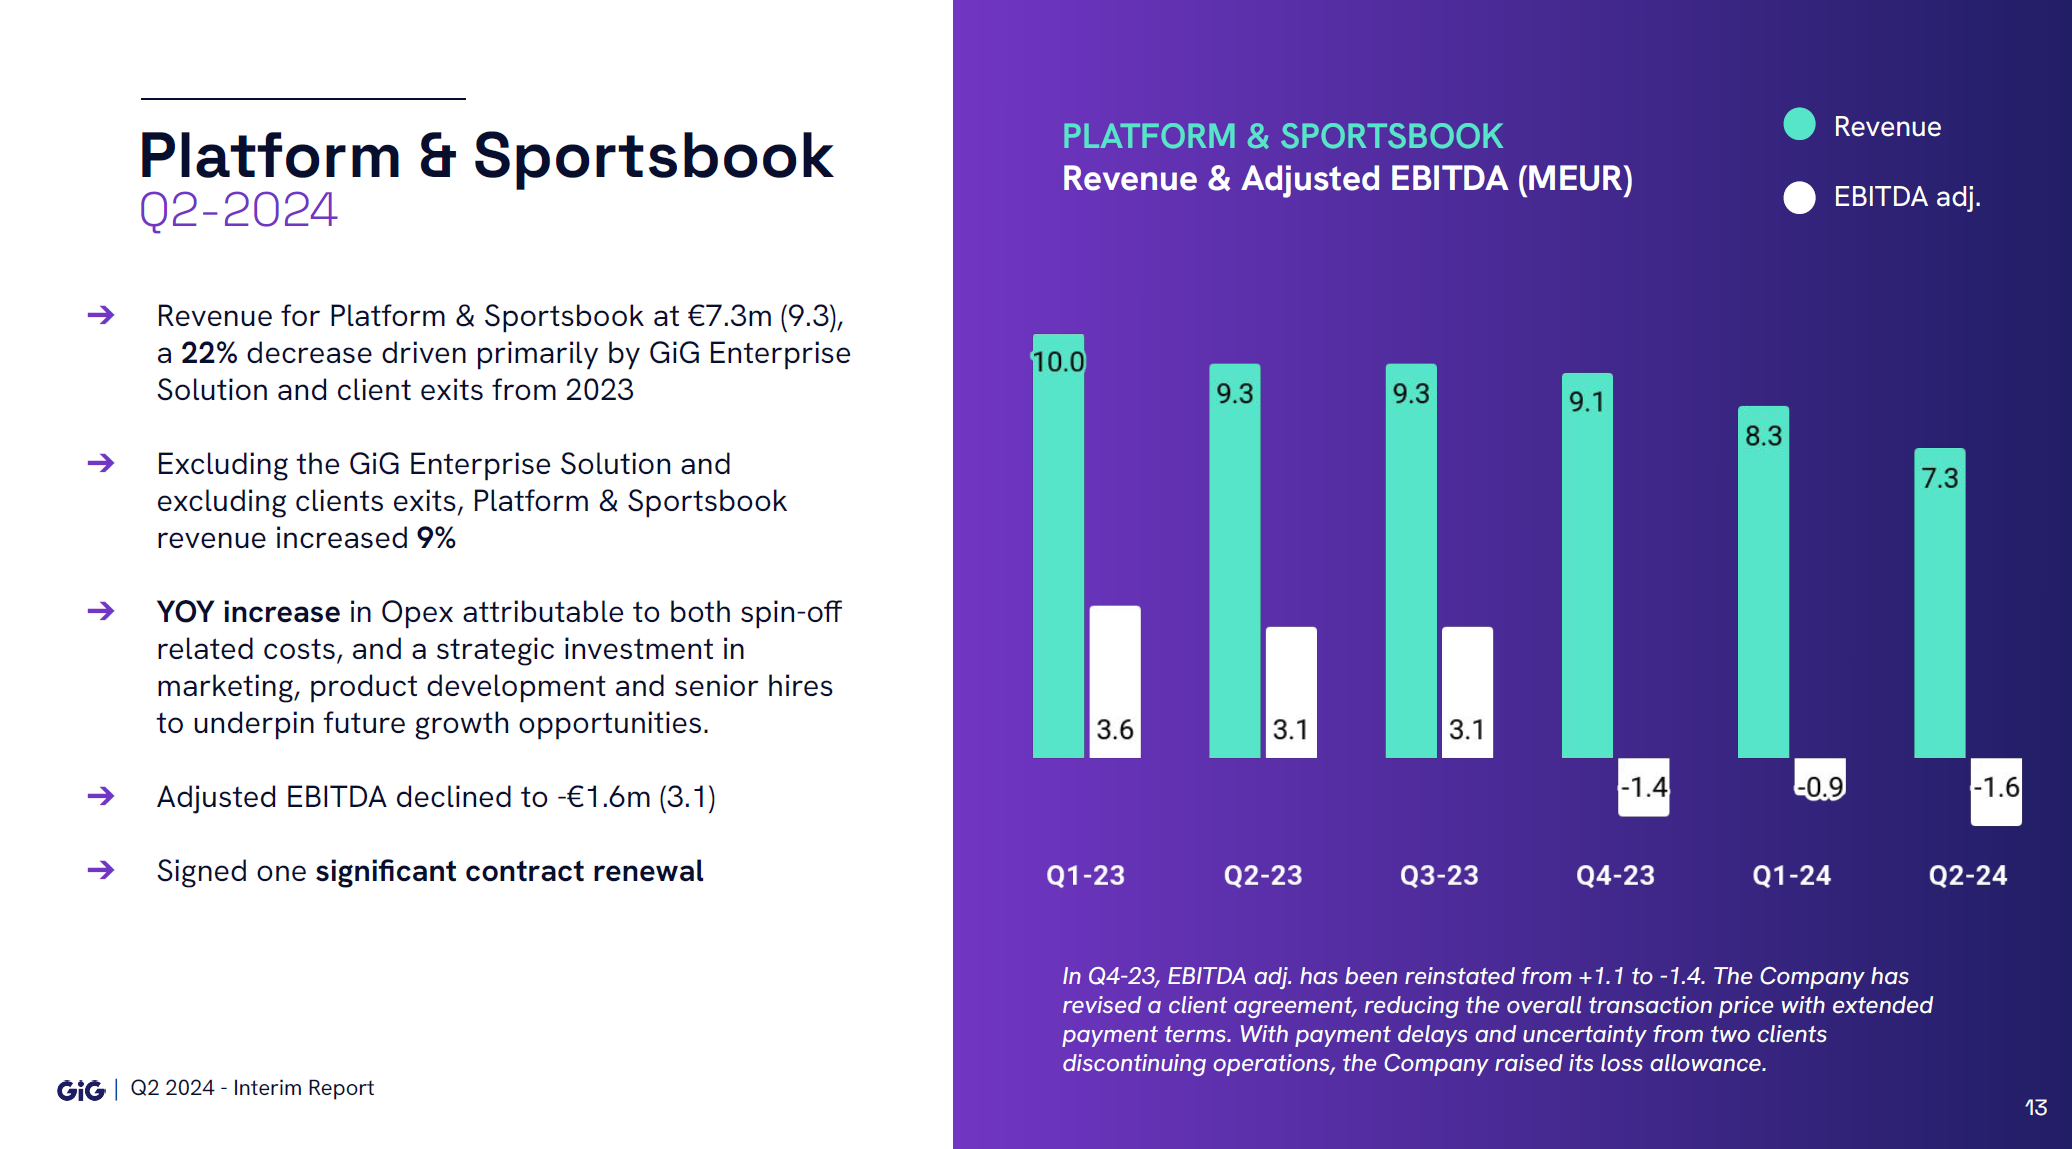
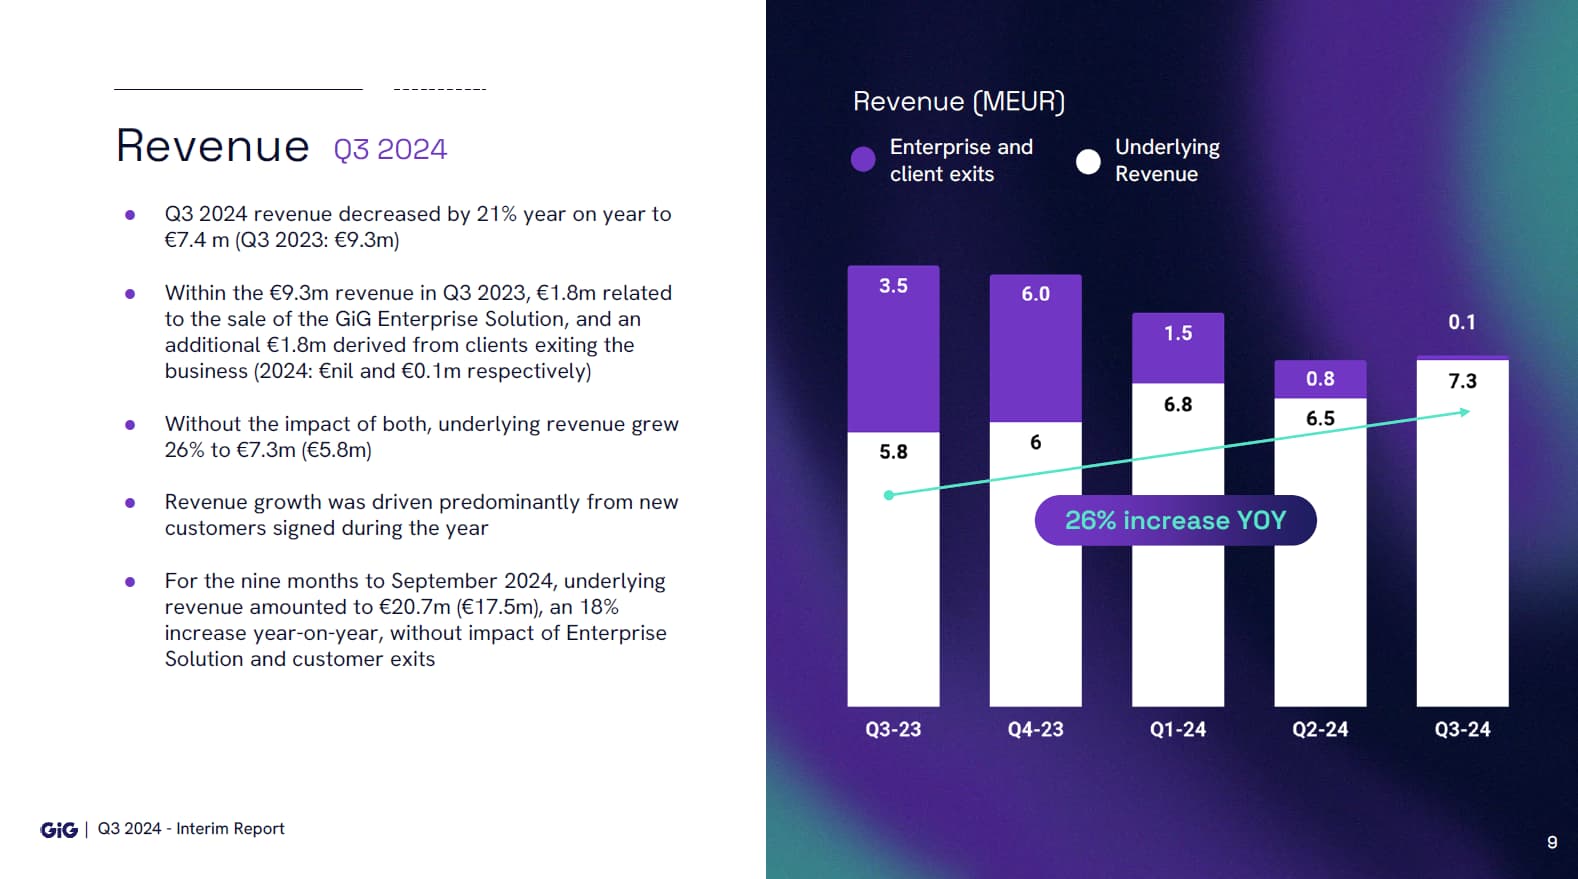
Platform & Sportsbook revenue grew by 34% in 2023, all of it organic. However, the chart below shows how growth has, at least temporarily, stalled. Q1 revenue was a disappointment to the market. Due to customer churn and the discontinuation of sales of the Enterprise product, revenue fell QoQ for the second consecutive quarter. Revenue from customers who stayed on the platform grew by 20% YoY.
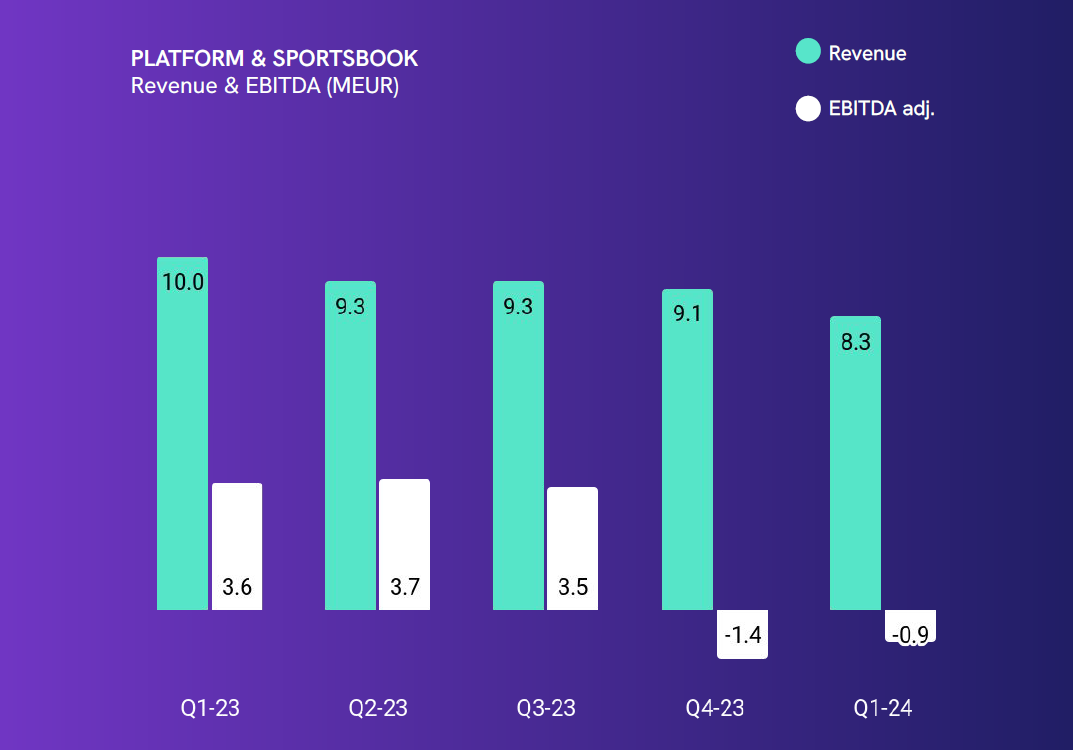
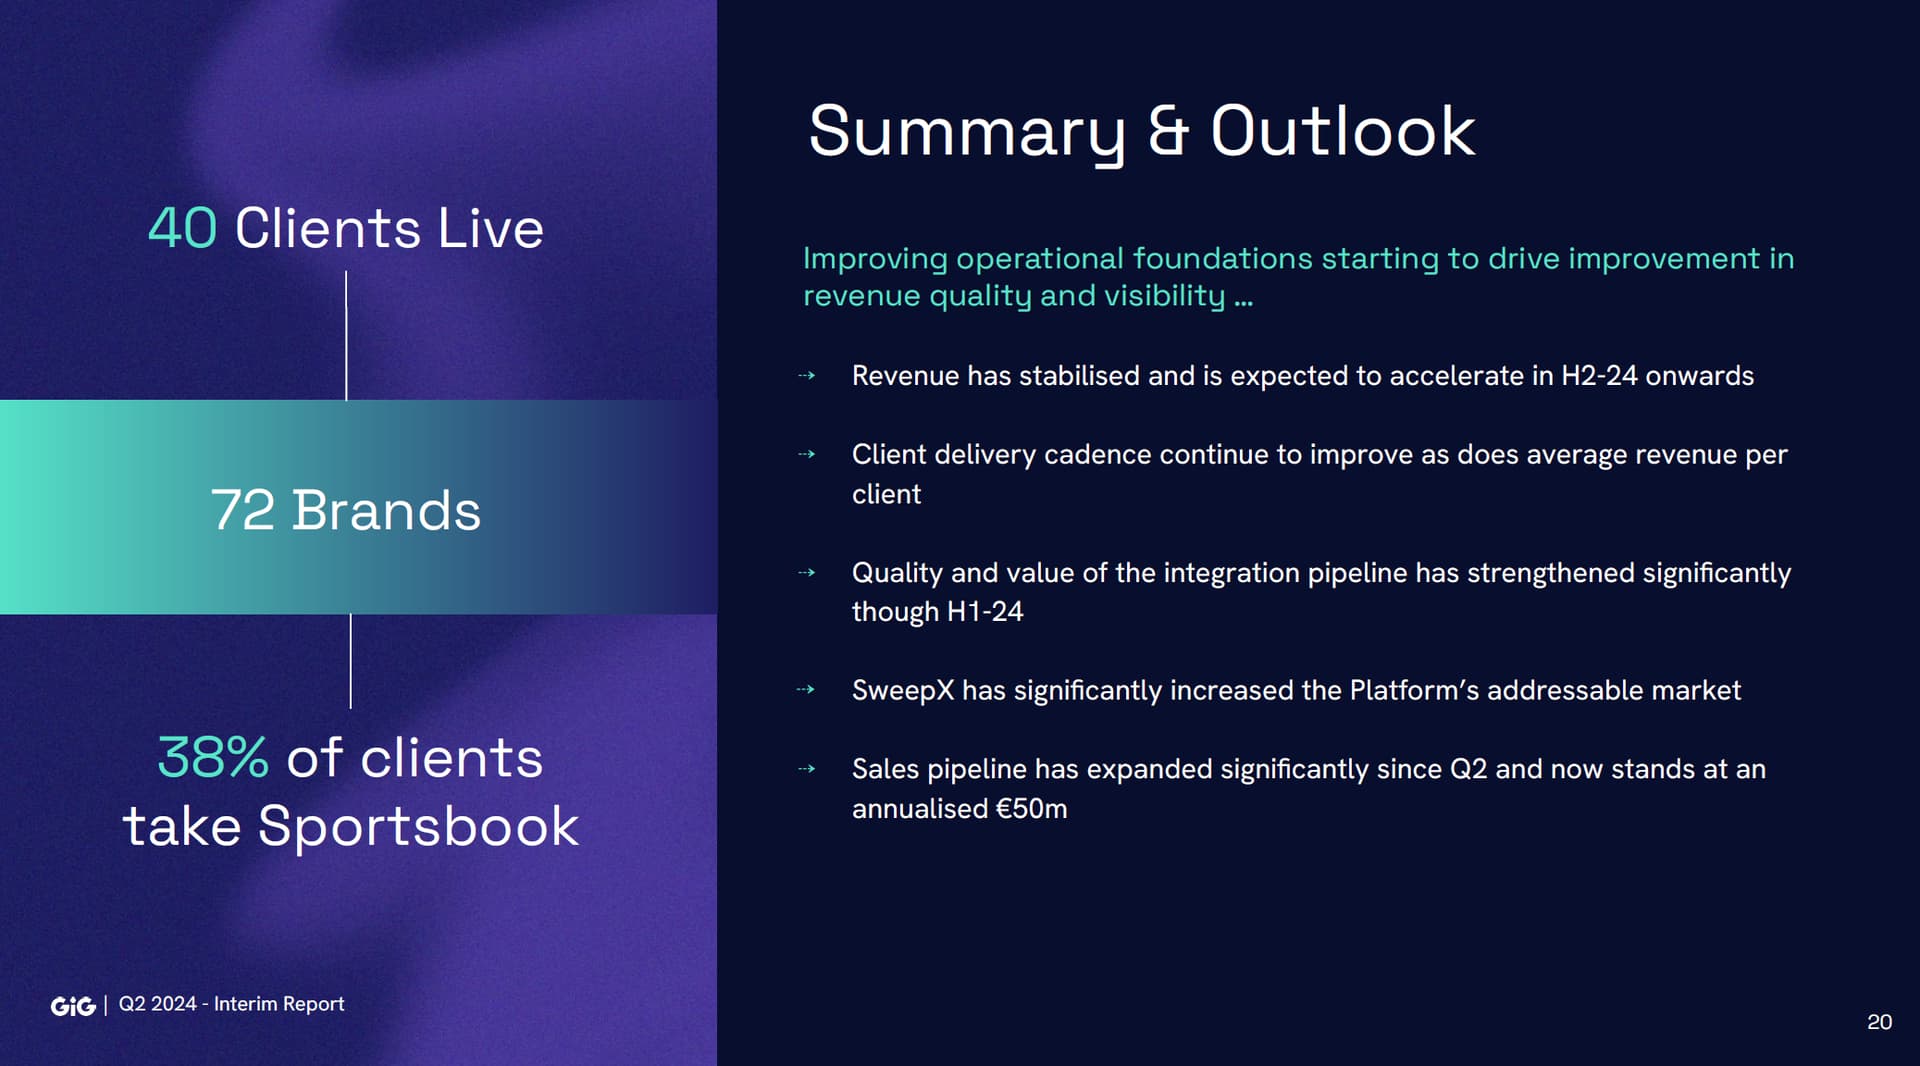
It should be noted, however, that the management of the platform side was revamped in late 2023 in preparation for the split, its product portfolio has been expanded, and the sales pipeline has more than doubled from a year ago.
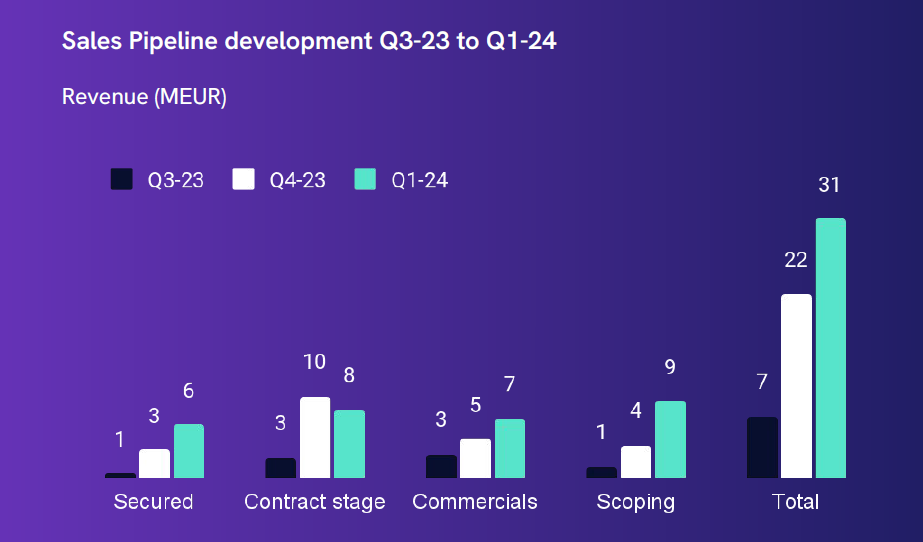
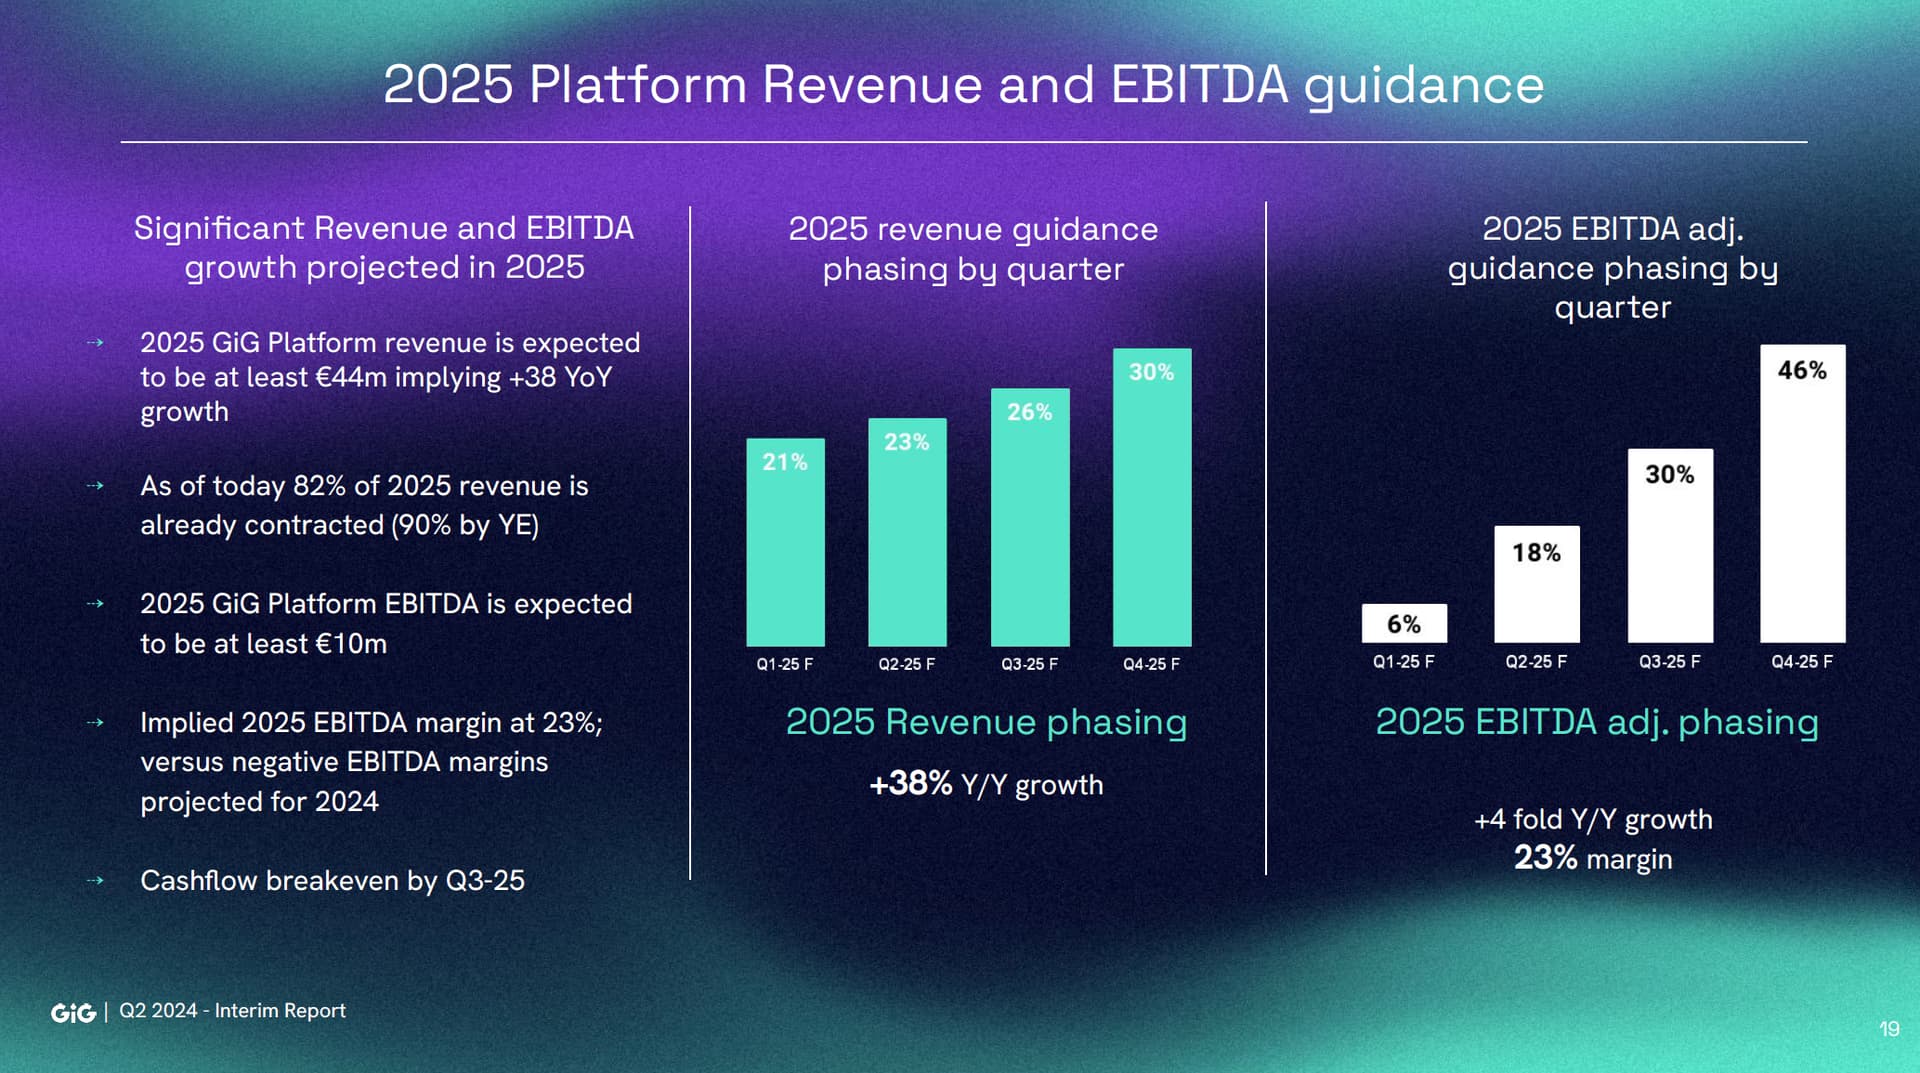
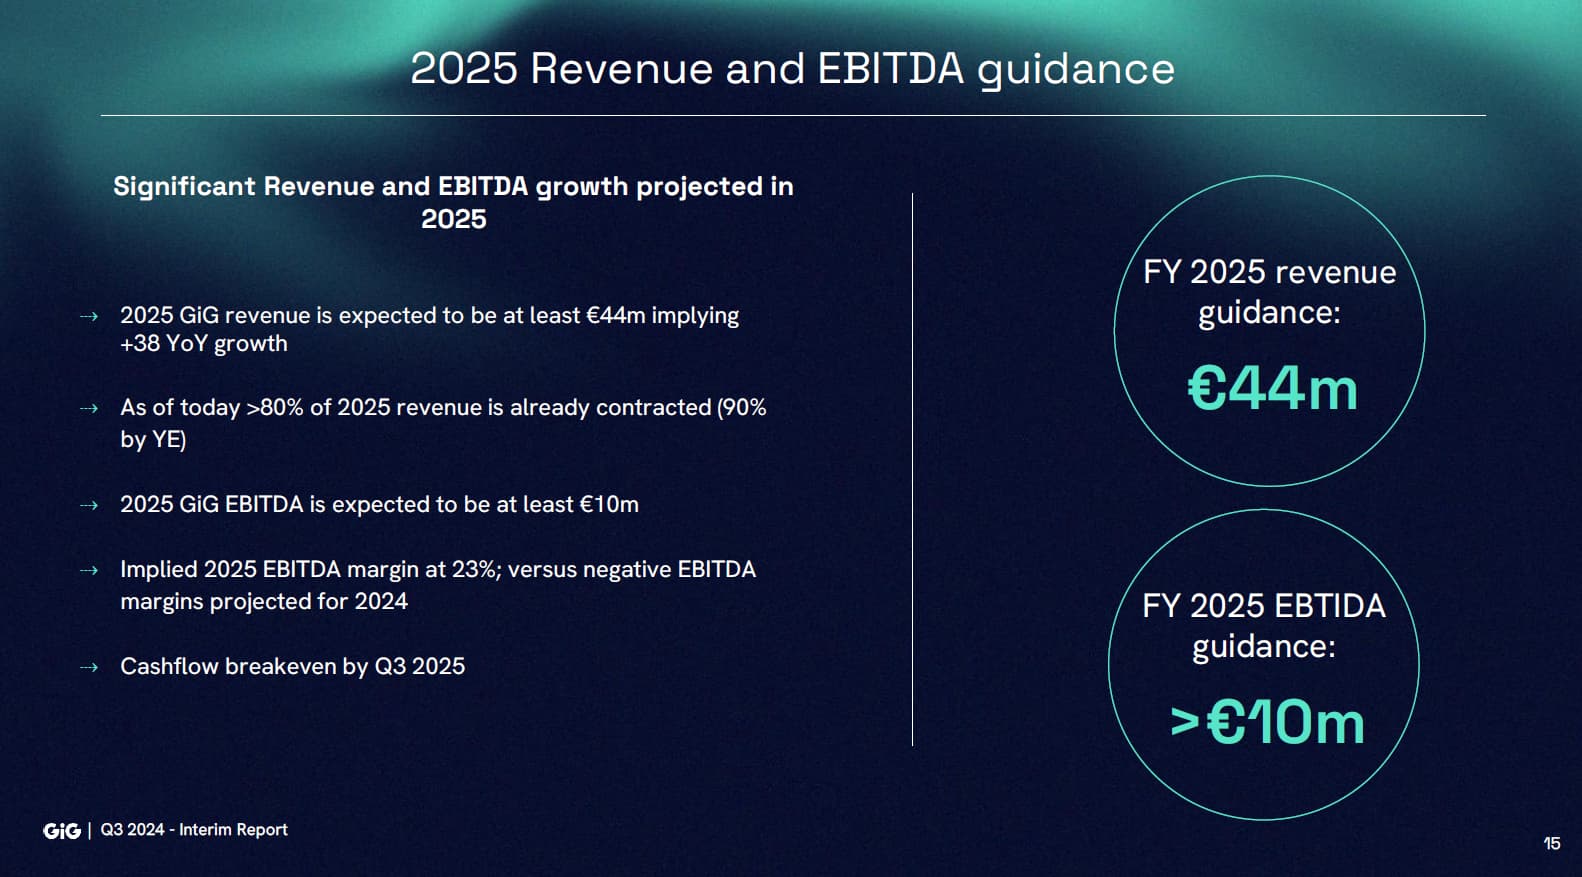
The company has high expectations, especially for the Sportsbook. The Sportsbook product has been adopted by 31% of existing customers, but 70% of customers in the pipeline are about to adopt the Sportsbook. This is significant because, as I mentioned above, every euro played in the Sportsbook brings GiG 3x the revenue compared to a euro played through the platform.Platform’s adj. EBITDA improved throughout 2023 and was 12% in Q4. Q1 took a step back due to growth and product investments. Also, the majority of GIG’s capitalized R&D expenses relate to the Platform & Sportsbook side, and the platform’s free cash flow is still clearly in the red. Therefore, do not swallow pure EBITDA figures raw.
Valuation
I have outlined EV 2024 scenarios on the back of a napkin below, using an EV/EBITDA multiple for Media and an EV/S multiple typical for high-growth SaaS companies for Platform.
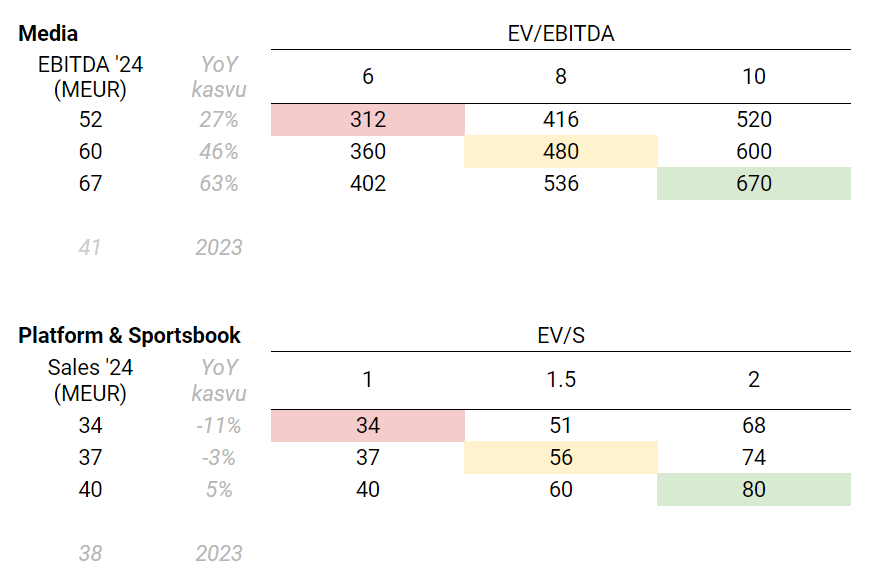
GIG’s EV is currently approx. 430 MEUR (share price 32 SEK), which includes both the Media and Platform sides.
Swedish brokerage houses’ mid-point/base case target prices and links to free analyses:
In the figures of the analyses, it is good to note that Red Eye and SEB forecast figures for both Media and Platform, while SEB and Carnegie forecast only for Media due to the upcoming split. Of the above, only Carnegie and ABG have updated their reports after the recent Q1.
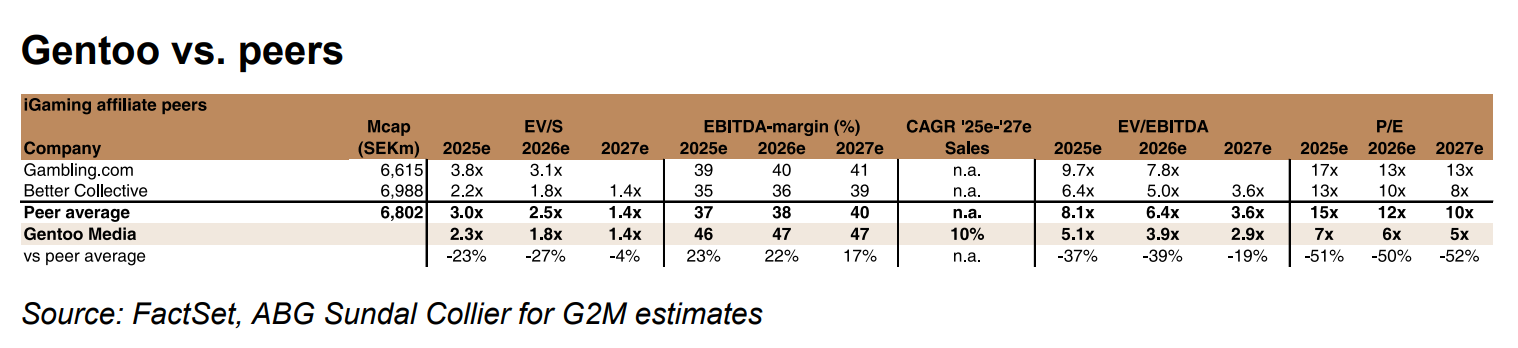
By Alex Feng here, there is also an insightful recent analysis of GIG’s investment case and valuation relative to peers, such as Better Collective, which is also followed on this forum (spoiler: the author sees GIG’s valuation as significantly more attractive than that of its peers). It is also good to note that the market, probably for many reasons, does not award very high multiples to companies like Media. In the scenarios above, I used relatively modest multiples, despite Media’s high growth rate and cash flow.
Owners
The ownership situation is interesting. Mateusz Juroszek’s family has been buying shares aggressively over the past year and now owns about 15% of the company.
Juroszek was the CEO of the sportsbook company STS, which Entain bought last year for 850 million euros. The family now reportedly has a fortune of two billion.
Last month, Juroszek commented to Bloomberg that:
- Plans to increase his ownership to 25-30% in the coming months
- Wants Media to double or triple its revenue over the next 2-3 years and list on Nasdaq
- Expects Media’s US revenue share to grow to 30% from the current 10% following the KaFe Rocks acquisition
- The Juroszek family is ready to continue financing GIG’s future acquisitions
In addition, it is worth noting that the Platform side’s relatively new CEO Richard Carter bought 200k shares in February (530 kEUR), and GIG’s CEO Jonas Warrer bought 270k shares in December (700 kEUR).
Juroszek and another board member also made small additions this week on the earnings dip.
Targets & Forecasts
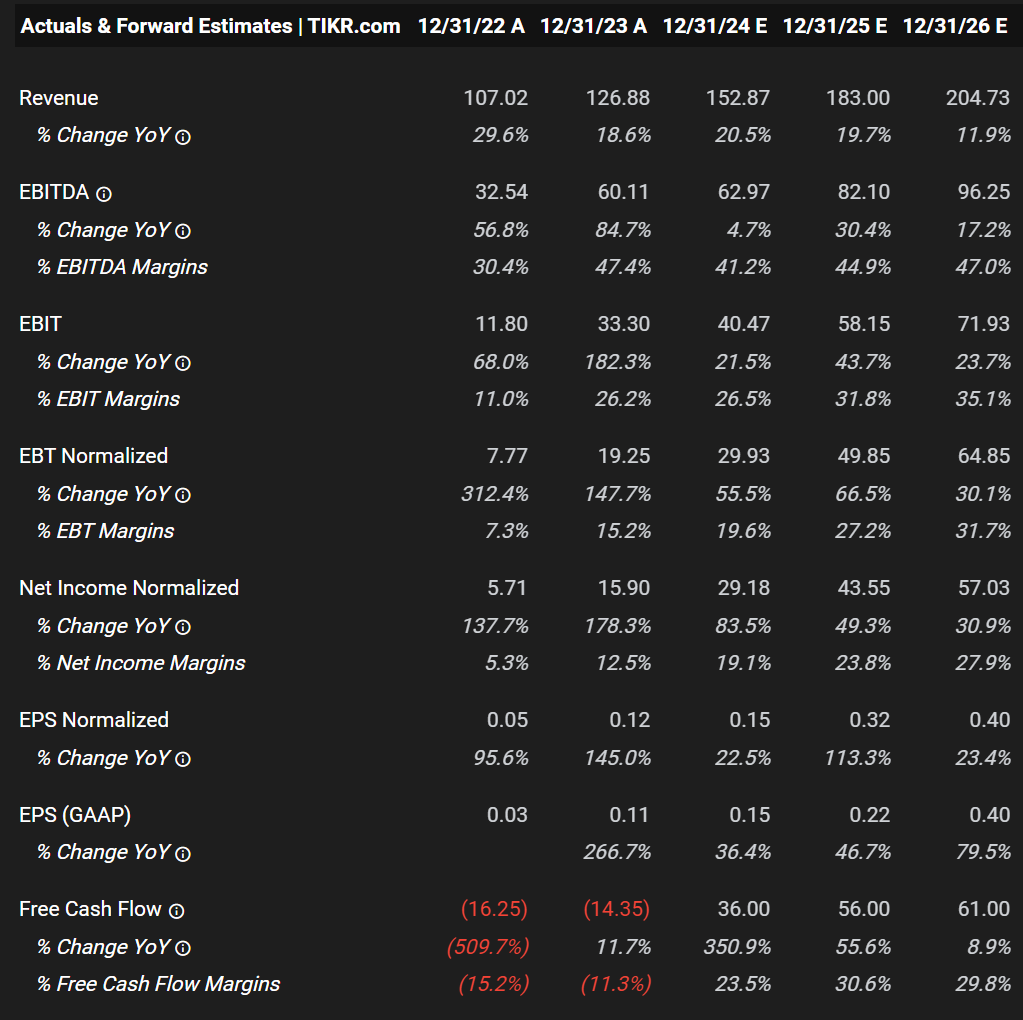
As the split approaches, GIG has not set long-term targets. However, from the figures mentioned by Juroszek, one can at least draw indicative conclusions about where the company is intended to be taken.
Analyses forecasts from Tikr - more detailed figures in the analysis links above.
To wrap it up, my own retail-investor-flavored estimates of the case’s catalysts and risks:
Catalysts
Short term:
- The split, likely happening in H2, will make the sum-of-the-parts value clearer to investors; Media is attractively valued based on cash flow and peers, P&S on SaaS metrics
- Good start to Q2: Media’s revenue grew by 19% organically in April
- Major sports events boost 2024 betting: Euro 2024, Copa America, Paris Olympics + the sports side is just being added to AskGamblers
- Platform side’s strong sales pipeline and Sportsbook’s cross-selling opportunities
- Media’s Kafe Rocks acquisition, will it reach AskGamblers-like striking distance?
Long term:
- iGaming tailwind: the industry is forecasted to continue growing by over 10% at least through this decade
Risks
Media:
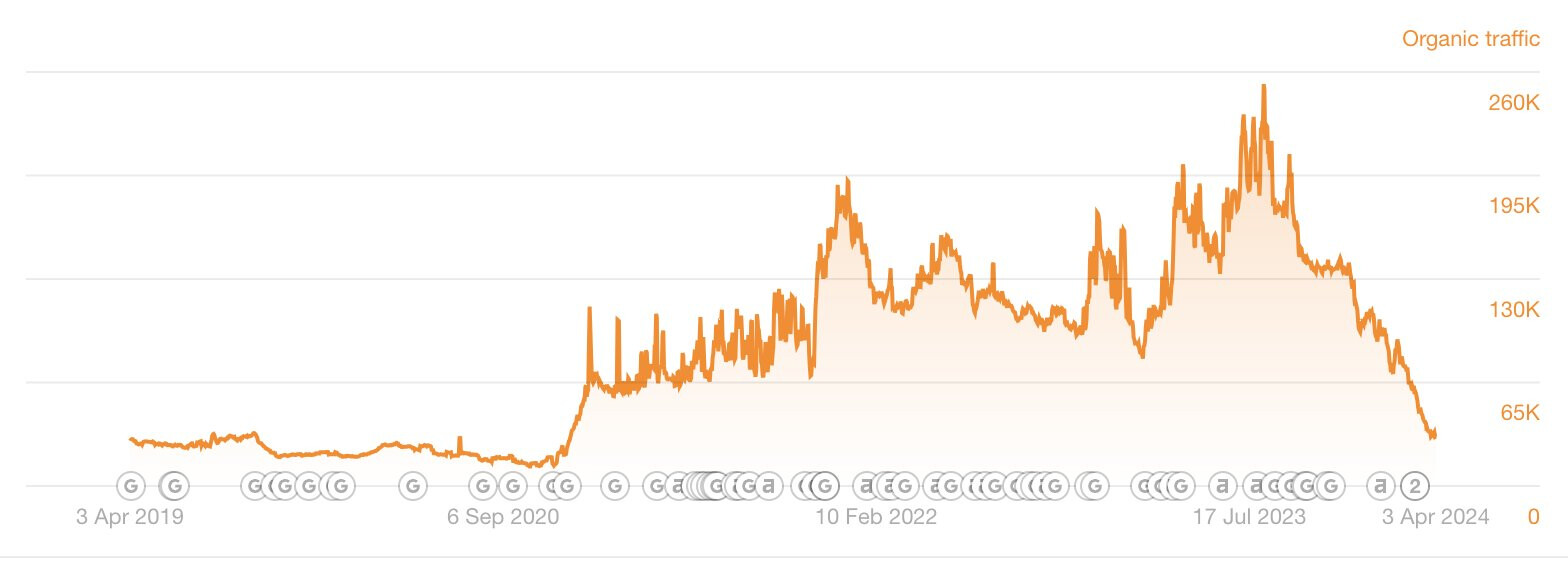
- Changes in Google’s search engine algorithms
- Risks related to acquisitions and financial leverage
- Are the excellent margins at a sustainable level/is competition increasing?
Platform & Sportsbook:
- Cash flow in the red/financing risk
- Fierce competition and operators’ own solutions; cf. Kambi’s challenges in recent years
- Competitiveness of the product portfolio still a question mark, especially in the eyes of larger clients
- Regulatory changes in key markets
If you got interested, the recent Q1/24 webcast nicely summarizes the situation of both Media and the platform side.
And a final disclaimer: I made a small entry into GIG at 27 SEK in spring 2023 and have been adding in the 30-34 SEK range in recent weeks. Currently about a 5% position in the portfolio. So we are still in the dating phase