Here are Ronin’s pre-report comments ahead of Etteplan’s earnings release on Wednesday.
The beginning of the year was exceptionally difficult for the company, as geopolitical uncertainties froze customer decision-making. We expect the demand situation in Q2 to have been better than in the beginning of the year, though it remained challenging and revenue likely declined slightly year-over-year. In terms of earnings, we expect the quarter to have been significantly better than the start of the year, which is also required by the guidance. However, we see a clear risk to the full-year guidance, considering the significant lag created after the start of the year. The most interesting aspect of the report will be the demand outlook for the remainder of the year and the sustainability of the guidance. With the Finnish economy picking up, we see the possibility that the outlook is improving, even though the geopolitical uncertainties that previously overshadowed the outlook are still present.
Roni interviewed Etteplan’s CEO Juha Näkki following the Q2 release
ETTEPLAN OYJ Half-year financial report August 5, 2026, at 1:00 p.m.
ETTEPLAN Q2 2026: First signs of a pick-up in demand amid uncertainty
Key points April–June 2026
Revenue of the Group decreased by 2.7 percent and was EUR 88.9 (4–6/2025: 91.4) million. At comparable exchange rates, revenue decreased by 3.2 percent.
Operating profit (EBITA) decreased by 9.0 percent and was EUR 5.5 (6.0) million, or 6.1 (6.6) percent of revenue.
Operating profit (EBIT) decreased by 4.4 percent and was EUR 4.2 (4.4) million, or 4.7 (4.8) percent of revenue.
The combined effect of non-recurring items on operating profit (EBITA) and operating profit (EBIT) in April–June was EUR -0.3 (-0.9) million.
Operating cash flow was EUR 3.7 (6.9) million.
Earnings per share (undiluted) were EUR 0.10 (0.10).
The share of revenue from AI-based service solutions developed by Etteplan was 6 (4) percent during the quarter.
Key points January–June 2026
Revenue of the Group decreased by 3.7 percent and was EUR 179.4 (1–6/2025: 186.3) million. At comparable exchange rates, revenue decreased by 4.3 percent.
Operating profit (EBITA) decreased by 22.3 percent and was EUR 9.2 (11.8) million, or 5.1 (6.3) percent of revenue.
Operating profit (EBIT) decreased by 25.5 percent and was EUR 6.4 (8.5) million, or 3.5 (4.6) percent of revenue.
The combined effect of non-recurring items on operating profit (EBITA) and operating profit (EBIT) in January–June was EUR -1.0 (-2.3) million.
Operating cash flow was EUR 7.8 (12.0) million.
Earnings per share (undiluted) were EUR 0.14 (0.19).
The share of revenue from AI-based service solutions developed by Etteplan was 6 (4) percent during the first half of the year.
Here is Roni’s company report on Etteplan following their Q2 results
Etteplan’s Q2 figures fell short of our forecasts, as the continued decline in revenue also led to weak profitability development. The company lowered the upper end of its guidance for the second half of the year, but in our view, even the lower bound of the updated range requires a very strong end to the year. There are visible signs of improvement in demand, and the trend was upward in Q2. However, for the guidance to be achievable, this improving trend must continue smoothly in our view. Driven by slightly improving prospects, we raise our target price to 8.00 euros (prev. 7.50 euros), but given the clear profit warning risk and a neutral valuation relative to this, we reiterate our reduce recommendation.
Roni has written a comprehensive report on Etteplan, which is available for everyone to read.
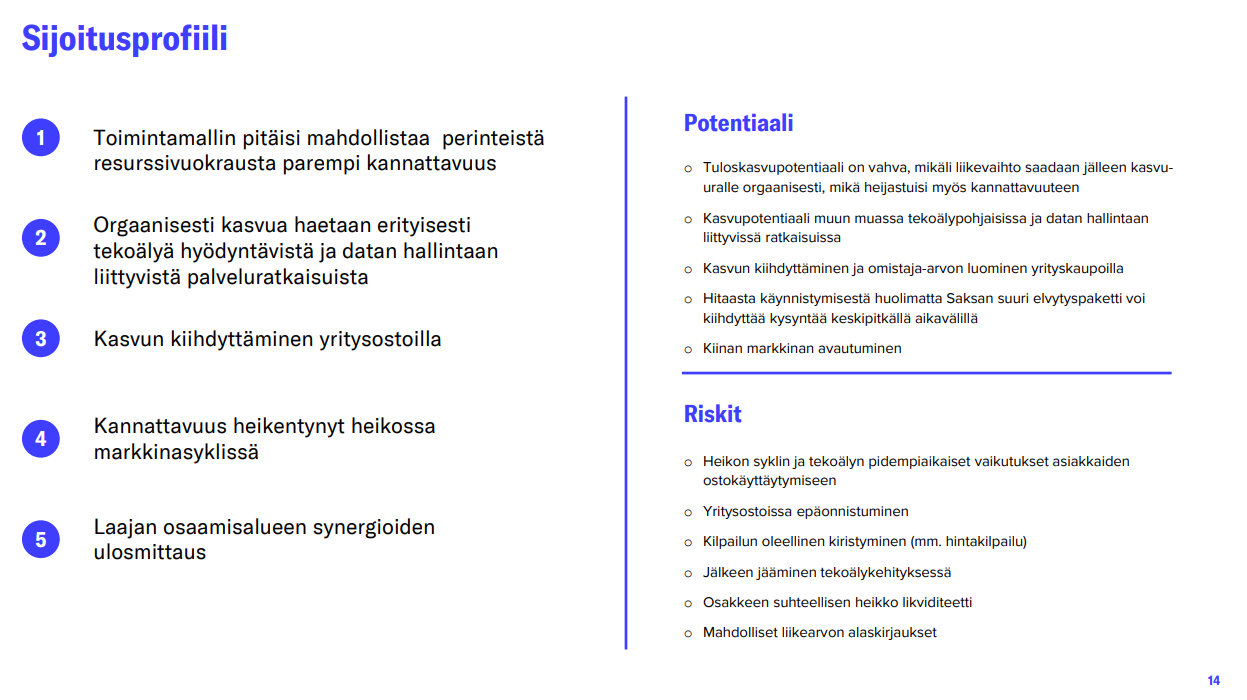
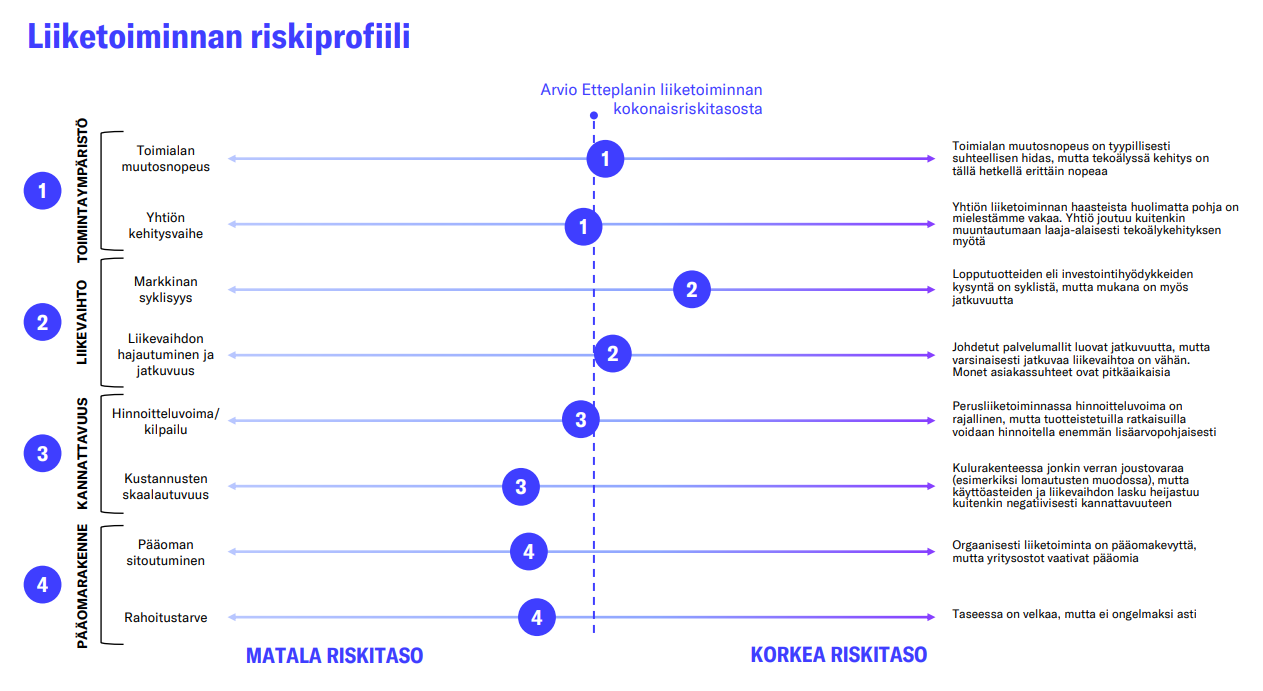
Etteplan has difficult years behind it. Now there are signs of improvement in the demand outlook, even though the situation remains challenging in certain customer industries. In the short term, we still see a risk of a profit warning if demand has not started to recover briskly after the summer. The valuation is moderate, but the slope of earnings growth and short-term risks keep us on the sidelines for now. We are revising our target price to 8.5 euros (prev. 8.0 euros) following minor positive forecast revisions, but we reiterate our reduce recommendation.
Quoted from the report:
Despite Etteplan’s challenges in recent years, its medium-term earnings growth potential is quite good. However, this is backed by a quite low starting level of earnings, as both revenue has declined clearly organically in recent years and profitability is at a subdued level. Nevertheless, the realization of earnings growth requires a change in the demand environment from the exceptionally difficult environment of recent years. In our view, however, forecast risks remain elevated. Based on our forecasts, earnings per share will grow at an average pace of about 7% per year in 2026–2029 (starting level 2025). For 2027–2029, our forecasts expect an annual growth of 12% (starting level 2026).
Alongside the extensive report, a video with @Roni_Peuranheimo was also filmed! In the video, I tried to ask whether there’s any turning back to the success of past years or how much of the weakness can be blamed on the difficult cycle.
On the other hand, we have seen lively developments in the Finnish economy, and if and when this starts to show in investment activity at some point, would it then be better to be on board with Etteplan than sitting in the stands? Of course, we will probably have to weather a profit warning during the end of the year first. Let’s stay tuned to see if one comes and, if so, how severe it will be.
Historical track record of profitable growth and value creation for shareholders has begun to fade into oblivion in recent years as a difficult cycle has battered Etteplan. Neither have multiple profit warnings improved investors’ perception of the company. Analyst Roni Peuranheimo discusses what conditions Etteplan has to adapt to a market changing with artificial intelligence and to return to historical profitability levels.
Topics:\n(00:00) Introduction\n(00:14) Are Etteplan’s best years behind it?\n(03:51) Is AI a threat or an opportunity?\n(06:46) Competition against global giants\n(08:51) Is there a return to historical profitability levels?\n(10:49) Short-term risks keep us cautious
Etteplan Oyj, Stock Exchange Release / Inside Information, September 16, 2026, at 12:00 noon
Etteplan issues a profit warning and lowers its guidance for 2026
Revenue is estimated to be EUR 355–365 million and operating profit (EBIT) EUR 16.5–20 million
In its half-year financial report published on August 5, 2026, Etteplan Oyj estimated that the Group’s revenue for 2026 would be EUR 360–375 million (2025: EUR 361.4 million) and operating profit (EBIT) EUR 19–22 million (2025: EUR 17.9 million).
Etteplan is lowering its previous estimate for revenue and operating profit for 2026 due to market demand and slower-than-expected business development. According to the new estimate, revenue is estimated to be EUR 355–365 million and operating profit (EBIT) EUR 16.5–20 million.
“After the summer, market demand has not developed as expected and there have been delays in the launch of projects. However, the market is currently developing positively and we expect demand to improve towards the end of the year. We see many opportunities for our service solutions and continue to invest in growth. However, this generates costs that partly affect our earnings development this year,” says Etteplan’s CEO Juha Näkki.
Etteplan’s interim report for January–September 2026 will be published on Thursday, October 29, 2026.
Here are Roni’s comments on Etteplan’s profit warning.
Etteplan announced on Wednesday that it is lowering its revenue and earnings guidance for the current year. The profit warning did not come as a surprise to us, as our own forecasts were already below the company’s previous guidance and around the midpoints of the new guidance. In our extensive report published in early September, we also highlighted a clear profit warning risk. Although the new guidance range still leaves room for quite different trajectories for the rest of the year, market demand is cautiously picking up, and the company will in any case achieve at least modest earnings growth in the remainder of the year compared to weak comparison periods. As a result of the profit warning, our forecasts will only be subject to minor fine-tuning.


 In the video, I tried to ask whether there’s any turning back to the success of past years or how much of the weakness can be blamed on the difficult cycle.