The result itself is out. Indeed, headwinds from customer hesitation, the krona weakened, some orders shifted out beyond the first quarter, etc.
Those things fluctuate. For some reason, the report doesn’t mention BPC’s market share, which has always been stated in previous reports as being approx. 90% “according to the Board’s estimate.” Who knows why it was left out…
This outcome is clearly not satisfactory, and we take it seriously. At the same time, the quarter should be viewed in the context of timing effects, prolonged sales cycles, currency headwinds and continued investments in the platform and organisation, not as a weakening of BPC’s long-term market relevance.
With small illiquid companies, sentiment on the stock exchange shifts quickly.
The company has 69 MSEK in cash, which is more than a year’s worth of revenue! 
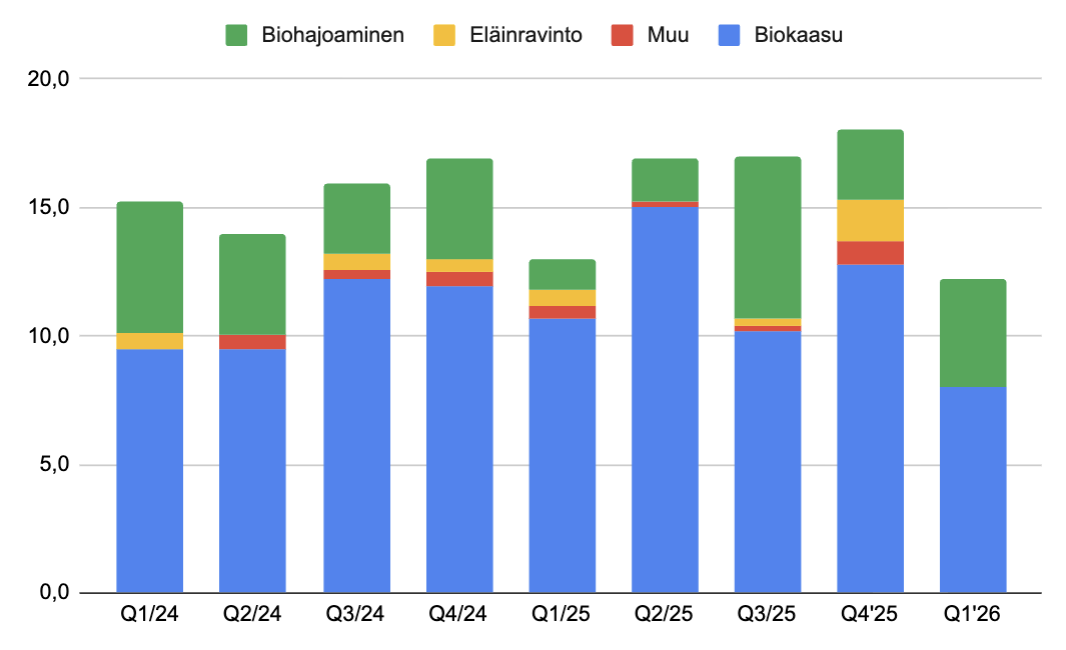
In the last quarter, all sales went to either the biogas or biodegradability segments.
The stock has taken a tumble. EV/S is now 2x, EV/EBIT 18x.
If one were to assume that a niche instrument company’s profitability would normally be 20%, the EV/EBIT would be 10x. Of course, the company aims to grow (already over 30 employees!), and therefore top-line growth must materialize to achieve such profitability.