Hello again! I thought I’d start a new thread for an interesting company that is listing on First North in Stockholm. Here’s a thread for those of us who are interested to dissect the company in terms of its numbers, goals, and presentation
Interesting in itself, if the idea is to make something other than gin.
If, on the other hand, they are making gin, it’s a bit difficult to see strong growth, as juniper berries are hand-picked from Finnish nature. I remember reading last year that it was difficult to find pickers, and I’m not at all surprised, it’s really tough work…
Juniper berries are still slow to ripen, taking three years, so not all berries on the juniper are suitable for production, only the ripe, dark blue ones.
It was apparently fully subscribed and slightly oversubscribed? In my portfolio, it seems I got everything I subscribed for (minimum was, if I recall correctly, 350 units?)
Here’s the press release translated into English with Google Translate, as I don’t speak Swedish.
"Arctic Blue Beverage’s new introduction on the Nasdaq First North Growth Market was subscribed for 109 percent and was thus oversubscribed. The share will start trading on May 12.
The Finnish company is a Nordic beverage company whose most famous products are Arctic Blue Gin, Arctic Blue Gin Navy Strength and the milk-free gin-based oat relic Arctic Blue Oat.
The offer comprises 1.87 million units at a subscription price of SEK 15 per unit. Each unit consists of three shares, two free warrants TO1 and two free warrants TO2. The subscription price thus corresponds to SEK 5 per share.
The company will receive SEK 28.0 million before issue costs and set-off of interest-free shareholder loans and will have almost 600 qualified shareholders. Following the offer, Arctic Blue Beverage has 17.12 million shares outstanding, which corresponds to a valuation of the company of SEK 85.6 million calculated on the subscription price."
The longer press release also mentions the figure 2.8x, but I didn’t fully understand what it refers to.
The internationally awarded Finnish beverage company Arctic Blue Beverages has signed a distribution agreement with the Swedish distributor Solera Sweden AB. Solera Sweden distributes Arctic Blue products throughout Sweden, and sales of Arctic Blue Gin and Arctic Blue Gin Navy Strength have already begun at Systembolaget.
The IPO results were announced yesterday, Thursday, and today a new distribution agreement in Sweden was published. Could the reasonable success of the IPO have influenced the sealing of this agreement?
Growth seems good, although the increase in revenue by approximately 80% is confusing, but the text section mentions a 174% Sales growth .
Listing costs made the result quite ugly, and I haven’t found the adjusted figures yet.
Something doesn’t quite add up. The text section of the report also mentions that revenue grew by 30% Q1>Q2, but according to the numbers, revenue decreased Q1>Q2 .
“Markets have opened after the pandemic and sales increase in the second quarter 2022 was 174% compared to the same period a year ago. Total sales revenue in the second quarter 2022 has increased by 30% compared to the first quarter in 2022. The good development is coming mainly from travel retail and domestic market. The sales to Asia-Pacific i.e. Japan still in some extent suffered from pandemic, but we are seeing some positive signals that we believe will turn into results during the 2nd year half 2022. In Australia we are making good progress with our distributor”
Or is the term “sales” intentionally used in the text section to mean that the company has other revenue besides product sales?
Edit. After reviewing the full report, it turned out that Q2 2021 revenue included 430 in “other operating income” and Q2 2022 had none, which explains the ambiguity.
Pure “Net sales” figures are therefore
H1 2021: 1883
H2 2022: 4515
An interesting company, though still quite early stage, and I don’t think the company has many resources to increase marketing efforts. However, growth has been quite good at the revenue level, even though the absolute figures are still small.
Revenue for Jan - Jun 2022 was SEK 5,861,000 (approx. €560k) vs SEK 2,935,000 (01-06/2021), but operating profit (EBITDA) for Jan - Jun 2022 was -SEK 20,659,000 vs -SEK 7,193,000 (01-06/2021).
The IPO was in May 2022, the result of which was SEK 28,000,000 before listing costs and repayment of shareholder loans. Other expenses increased quite sharply to -SEK 11,657,000, but these increased expenses are “one-off” costs related to "group restructuring (Swedish TopCo) and the IPO. It would therefore seem that the company did not receive a very significant sum from the offering into cash (at the end of June, the group had SEK 6,244,000 in cash, i.e., less than €600k). Of course, trade receivables have grown, and total receivables were SEK 10,483,000.
The company appears to employ only 8 people.
However, I need to monitor this if growth continues with the same slope and there are indications of improving profitability.
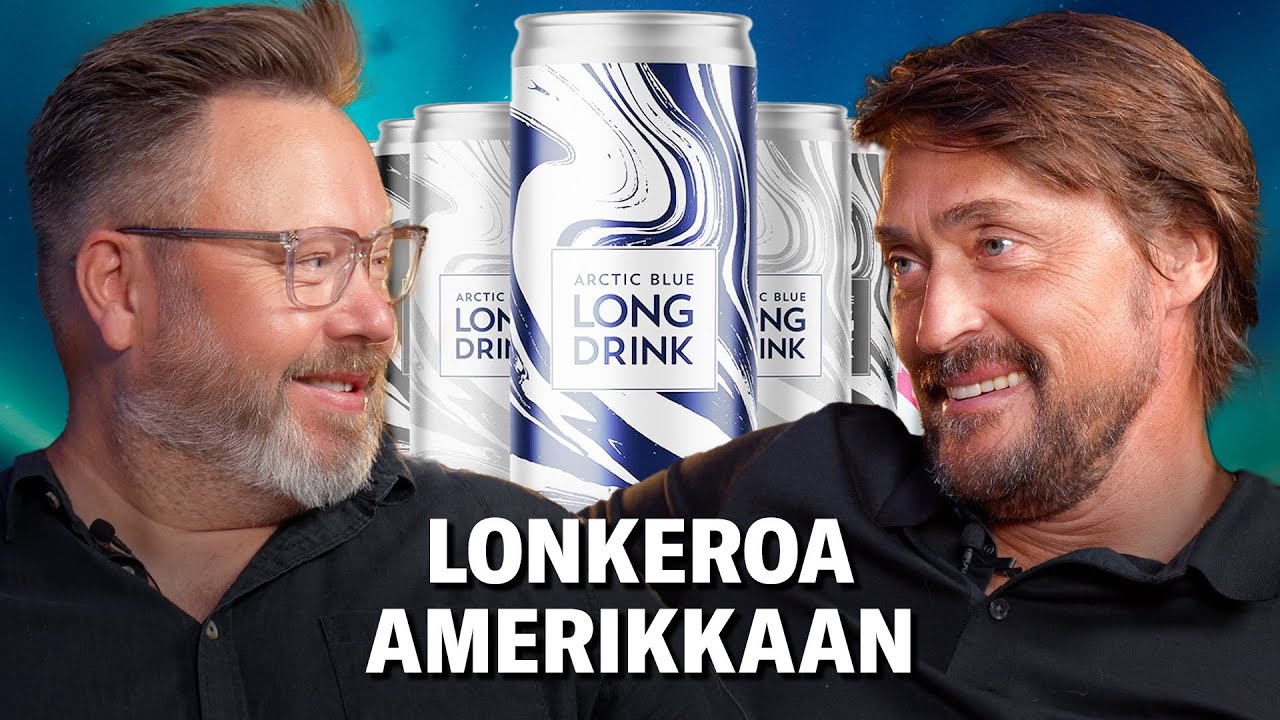
Here’s some interesting news about entering the US Long Drink market. Even Teemu Selänne has been brought in as an investor and to be involved. It’s well noted that the Finnish Long Drink Company has done the groundwork by introducing Long Drink to Americans, so they can somewhat stealthily leverage the competitor’s prior work.


 .