Sinch Ab - Sweden's fifth most shorted company

Greetings!

Over the summer, I’ve been following an interesting technology company from the wonderful world of the Swedish stock exchange. (1) Sinch AB has grown rapidly, mainly through aggressive acquisitions, and is currently one of the market leaders in cloud-based communication platforms. In short, they primarily offer businesses digital solutions and tools for transmitting messages to mobile phones as voice, video, and text message services. Founded in 2008, their customers range from the largest tech companies in the USA to 150,000 other business customers worldwide.

Revenue has grown by double and triple-digit percentages. Last year, revenue grew by +102% to approximately 16 billion SEK. The company has been profitable every year, and rolling EBITDA has grown steadily.

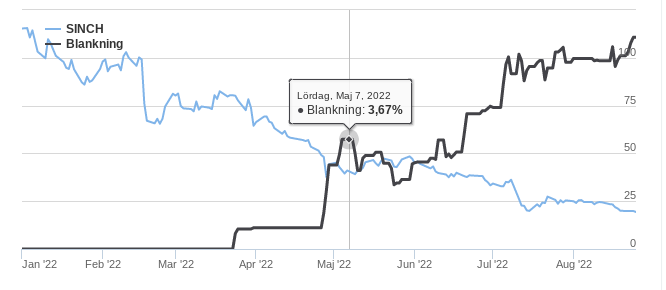
In addition to very strong growth, what makes this interesting is that short sellers have targeted the company. Currently, short sales account for 12.28 percent of the total share capital (2).

On July 11, short sellers published an anonymous report alleging problems with the company’s financial statements. (3) The uncertainty increased when Sinch AB later that night issued a statement announcing a reassessment of 162 million SEK in one-time expenses, which weakened the Q2 result. (9)

On July 21, Sinch and audit firm Deloitte jointly stated in the Q2 report that all claims made by the short sellers were misleading and their conclusions were completely incorrect. According to the company, the one-time reassessment of expenses was not related to the short sellers’ report. (4) (8).

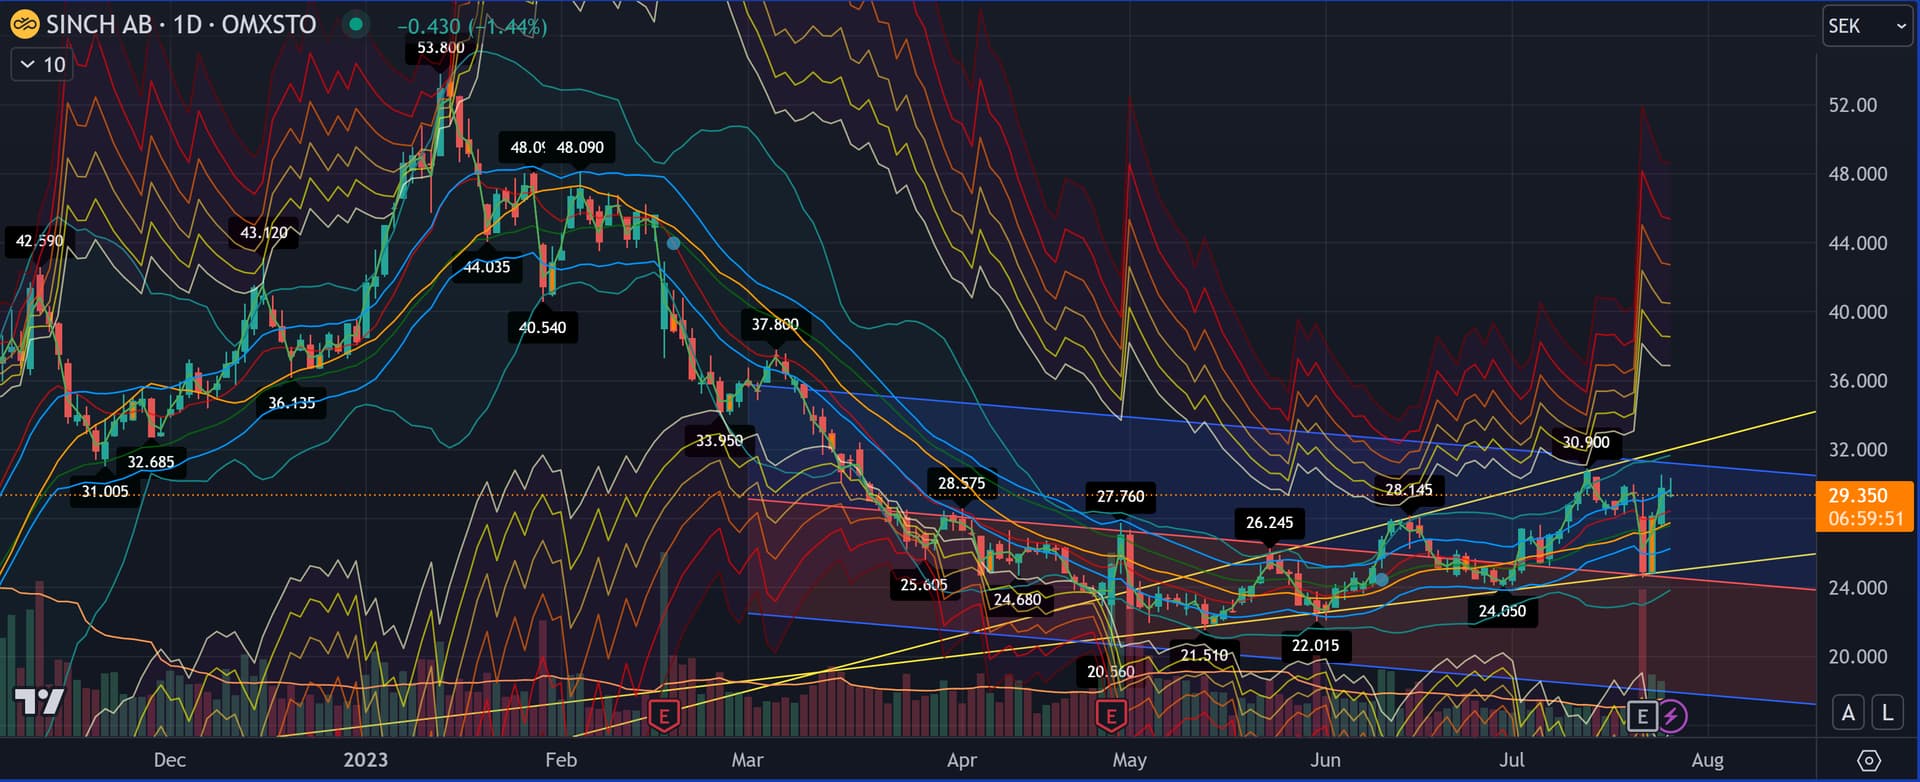
However, volatility and uncertainty have not subsided since July; instead, the share price has fluctuated wildly.

The company’s 15 largest shareholders own 69.6% of the company. They are primarily institutional and long-term owners. (5) Overall, Swedish and foreign institutions own 70% of the total share capital (6) p.27. Outside of institutions, short sellers own a significant portion of the company’s share capital.

From the shareholders’ perspective, the situation is now:

Total shares: 838,185,598
Top 15%: 576,239,058 (69.6%)
Others: 261,946,540 (30.4%)
Sold short: 102,929,191 (12.28%)

Currently, the company is valued at low multiples (7):

Market Cap: 16.7 billion SEK
Revenue: 16.2 billion SEK (2021) (2022e): 26 - 28 billion SEK
Net profit; 0.907 billion SEK (2021)
Share price: 20.00 SEK
EPS: 1.29 SEK (2021)

P/S: 1.03 (2021)
P/E: 15.5 (2021)

PS. This message is not an investment recommendation or any attempt at market manipulation. The purpose is to share an interesting, almost cinematic situation in the markets with the community. :smile:

Sources:

(1) Sinch (SINCH) osake | Nordnet

(2) https://www.fi.se/sv/vara-register/blankningsregistret/emittent/?id=549300UXY7QM6IDCGI12

(3) https://ningiresearch.com/2022/08/02/research-note-sinch-ab/

(4) https://investors.sinch.com/static-files/9e7d5a84-361b-413a-849d-d0c4c21c612d

(5) https://investors.sinch.com/the-share/shareholders

(6) https://investors.sinch.com/static-files/f47c13e5-2677-4b08-94c8-965fa487b5a9 (p.27)

(7) Sinch aktie - Dagens industri
(8) https://www.youtube.com/watch?v=18cE8CkHcz8

(9) https://investors.sinch.com/news-releases/news-release-details/reassessment-historical-cost-goods-sold-affect-sinchs-q2-2022

26 Likes

Currently, short selling covers 13.08 percent of the total share capital. (12.28%)

All short positions opened within 6 months and with excellent timing relative to market news.

A small rebellious spirit is starting to brew in the Swedish finance Twitter:

https://twitter.com/BillieBillion1/status/1562714124660125699

6 Likes

I looked into Sinch’s acquisitions from 2021 a bit more. A total of four companies were acquired: Inteliquent, MessageMedia, MessengerPeople & Pathwire. Cash used for acquisitions was SEK 20,773 million, borrowed capital was SEK 8,200 million, and own shares were SEK 6,916 million.

In total, approximately SEK 27,689 million of equity was used for acquisitions in 2021. Considering that the entire company’s market capitalization is currently SEK 15,054 million, the market views the acquisitions as worthless or even negative, even though the strategic position in the market has significantly improved through high-quality US companies like Inteliquent and Pathwire. Also, in terms of numbers, revenue and operating profit have significantly increased from the new acquisitions.

My own forecasts for this year:

Revenue (2022e): SEK 28,320 million
EBITDA (2022e): SEK 2,800 million

Time will tell whether the markets are right or wrong. As a fun fact, if Sinch had not made any acquisitions and kept all the money as cash, the company’s market capitalization would likely be at least 25% higher at the moment. :sweat_smile:

7 Likes

Here are some short comments I made earlier in another thread:

5 Likes

Organic growth was just commented on yesterday at the Carnegie Seminar.

Seriously, in the spring, Sinch’s largest customer received a 9% discount on prices for a year ahead. The customer had previously paid a high margin relative to their volume. This customer accounts for 5% of the total revenue, and the customer relationship has lasted over 6 years. The customer is reportedly one of the world’s largest tech companies.

Negotiations also agreed that Sinch could start offering its currently expanded product portfolio to the customer. Reportedly, this has already generated sales and added value for the customer. It remains to be seen whether the expanded offering can be pushed to a wider sector of customers. There is certainly potential when one company can provide everything needed comprehensively worldwide.

The CFO “let slip” that revenue will be around 30 bSEK in 2022. It should also be remembered that Q2 margins are affected by a one-off item of 162 mSEK, which directly lowers margins. Margins should currently be stable, and according to the CFO, at least before costs, they have also been passed on to customers.

Undeniably, the development of the messaging side has been weak in recent quarters. It remains to be seen whether this is temporary or more permanent. In Sinch’s case, it is not uncommon for growth to occur in cycles.

4 Likes

Flagging notification

Capital Group has been on a buying spree and has increased its ownership from 3.7 percent to 5.1 percent. The previous main owner, who significantly reduced their ownership in winter, spring, and summer (11.00% → 3.7%)

https://twitter.com/MF_Holdings/status/1569616273343975424/photo/1

5 Likes

Acquisitions and purchase prices in 2020-2022

MessengerPeople 511mSEK
ACL 655 mSEK
Wavy 1187 mSEK
SDI 2403 mSEK
Inteliquent 9500 mSEK
MessageMedia 12 653 mSEK
Pathwire 16 600 mSEK

In total, 43,509 mSEK were spent on acquisitions.

Sinch’s current market capitalization is 13,764 MSEK.

This means that the market believes the acquisitions should have been left undone. It seems incomprehensible that the current market capitalization is lower than the purchase price of Pathwire, which was acquired at the end of 2021.

How much higher would the market capitalization be now if the company had not made the acquisitions and had kept all the assets as cash?

Just a year ago in June, the company had 12,264 mSEK in cash alone, which is about the same as the current market capitalization.

The current market capitalization, relative to the predicted revenue for 2022, means that the price-to-sales (P/S) ratio is 0.46. At the same time, the trailing adj. EBITDA relative to the market capitalization is about 5-6 (2022e).

7 Likes

I’ve been following this Sinchi on the stock exchange forums as well. It seems that investors’ faith in the company has waned, but the numbers aren’t hopeless by any means.

It’s difficult to assess how such a large number of acquisitions can truly be integrated; the market apparently doesn’t think it’s very smoothly.

Definitely one to watch, and even if my message was a zero-post, let it be an encouragement for others to continue commenting on this company. The immediate need for additional financing seems small; it naturally depends on how sales have developed recently.

E: and those acquisitions were indeed made partly during the bubble era, so the “true values” of the purchases could very well be a fraction of the purchase prices - although for Sinchi, their value could still be reasonably good.

3 Likes

6 Likes

I have to praise the thread starter. This would have made for good business. In my opinion, it’s an ideal overreacted target where the numbers haven’t been that terrible. Exactly when everyone thinks negatively about the company, that’s when you should investigate more closely and consider the situation :slight_smile:

July – September 2022

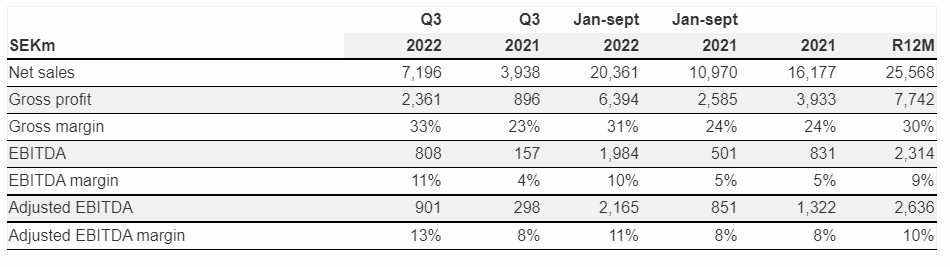
  • Net sales increased by 83 percent to SEK 7,196m (3,938).

  • Gross profit increased by 164 percent to SEK 2,361m (896).

  • EBITDA rose by 416 percent to SEK 808m (157).

  • Adjusted EBITDA1 increased by 202 percent to SEK 901m (298).

  • The loss after tax for the quarter amounted to SEK -4,765m (266) and was adversely affected by a non-cash impairment of goodwill of SEK -5,000m.

  • Basic earnings per share were SEK -5.69 (0.37) and diluted earnings per share were SEK -5.48 (0.36).

  • Cash flow from operating activities amounted to SEK 727m (-491)

3 Likes

https://www.globenewswire.com/NewsRoom/ReleaseNg/401420437

today announces that Will Conway, President for the Developer & Email Business Unit, has decided to leave the role as Business Unit President to pursue other opportunities. He will remain in a part-time strategic advisory role for Sinch during 2023.

1 Like

https://ml-eu.globenewswire.com/Resource/Download/69ad8e2c-1f1c-45f6-8077-f194e3897a5b

6 Likes

Am I right in understanding that Salesforce is about 200x the size of Sinch, so it’s nestling up against a big guy?

1 Like

Here’s the latest interim report: Interim report, January–June 2023 - Sinch AB

Looking at the background, I would have imagined encountering something terrible, but this doesn’t look bad at all. The turnaround is clearly progressing. The market offering seems to be on point, and this is certainly not a penny stock traveling from one share issue to another. If the company succeeds in its goals even roughly, the stock is cheap by any metric. Looking at the history, this probably involves some bitter investment experiences, but the timing to get on board now doesn’t seem like a bad idea at all.

4 Likes


Daily megaphone formed, predicting significant volatility for the price.

4 Likes

I only just read the interim report more closely now that the share price has drifted down to around 20 SEK. If I understood correctly, currencies provided a tailwind, without which there would have been roughly zero growth. Despite the results of the savings program, there was an increase in expenses. Based on the CEO’s comment, H2 looks challenging:

“Growth in Messaging has improved compared to Q1 but
remains unsatisfactory. We expect current market
conditions to prevail during the second part of the year with heightened cost-consciousness among our larger customers. Combined with changes in our business mix, this means that we may not see the same seasonal uplift that we’ve seen in previous years.”

I have bought back shares I sold earlier in the year and done some trading in the 22-27 SEK range, but I’m particularly concerned about future profitability, or how the company will navigate a potentially shrinking and/or unprofitable SMS business. Of course, these things are already reflected in the share price to some extent.

1 Like

logo

Interim report, January–September 2023

July–September 2023

  • Net sales increased by 1 percent to SEK 7,265m (7,196).
  • Gross profit increased by 3 percent to SEK 2,433m (2,361).
  • EBITDA rose by 5 percent to SEK 848m (808).
  • Adjusted EBITDA1 increased by 5 percent to SEK 943m (901).
  • Profit after tax for the quarter was SEK 46m (-4,765).
  • Basic earnings per share were SEK 0.05 (-5.69) and diluted earnings per share were SEK 0.05 (-5.69).
  • Cash flow from operating activities was SEK 862m (727).

January–September 2023

  • Net sales increased by 4 percent to SEK 21,213m (20,361).
  • Gross profit increased by 10 percent to SEK 7,015m (6,394).
  • EBITDA rose by 14 percent to SEK 2,256m (1,984).
  • Adjusted EBITDA1 increased by 22 percent to SEK 2,642m (2,165).
  • The loss after tax for the period was SEK -102m (-4,717).
  • Basic earnings per share were SEK -0.12 (-5.81) and diluted earnings per share were SEK -0.12 (-5.81).
  • Cash flow from operating activities was SEK 1,061m (1,535).
2 Likes

The Stockholm Stock Exchange is liking it, at least for now. +20% and turnover over 6M.

1 Like