21. HEIKKI KESKIVÄLI
This time, the interviewee is investment author and FinTwit personality Heikki Keskiväli, who is surely familiar to almost everyone following the Finnish investing scene even a little. I wanted to interview Heikki for many different reasons, but one of the main ones was his exceptional talent for condensing even the most complex topics into an understandable and engaging format.
In this context, I simply have to praise Heikki’s book “Tähtäimessä osakkeet” (“Stocks in Sight”)—it’s a book that offers immense value to beginners and seasoned veterans alike. I highly recommend picking up a copy for your bookshelf, as it’s a versatile and comprehensive work packed with essential insights in a concise format.
Personally, I consider Heikki one of the most important figures in Finland’s investing community, as he has educated tens of thousands of investors through his book and engaging Twitter account, among other channels. The way he communicates is also fantastic: he doesn’t boast, he doesn’t preach absolute “truths,” but instead provides solid foundational lessons and tools to help every investor move forward.
There are plenty of shouting headlines and needless noise in the world, but fortunately we have folks like Heikki who reliably help the rest of us investors make progress. 
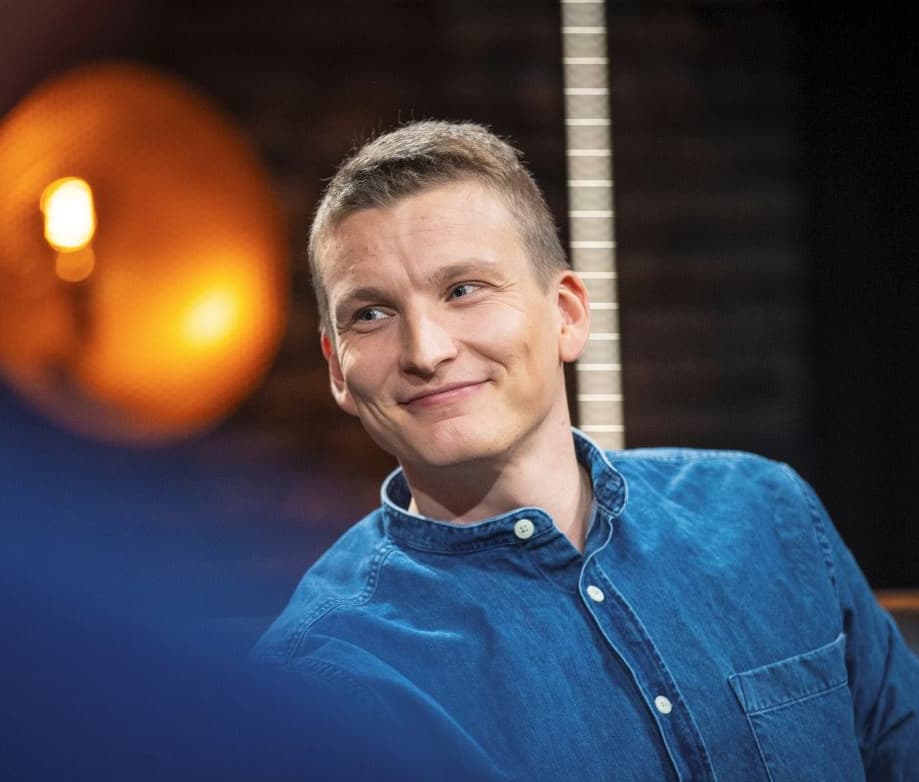
1. Tell us who you are in thirty words.
I am a 34-year-old father of two from Espoo (originally Lahti), passionately interested in a few things. First, reducing energy sector emissions by concretely advancing new production plants. Second, learning as much as possible about investing and sharing timeless lessons with anyone interested.
2. Tell us three things the forum members don’t know about you.
I’ve been cutting my own hair since my teenage years (saves time and money, and I don’t take appearances too seriously). I did visit a barber for my wedding, though—there are limits, after all.
I never, under any circumstances, start eating popcorn or candy before the movie begins.
I prefer renting my home because I don’t want to own stuff, things, or anything else that increases stress without bringing proportionate joy.
3. What are your interests and hobbies? You’re not allowed to mention anything related to investing.
I’ve played football since I was four years old and still actively play in the winter league, futsal, lower divisions, and 5v5. I also enjoy cooking, usually 3–5 times a week. I run a lot—typically 100–200 km per month—to stay healthy and fit well into the future.
4. What does a typical weekday look like for you?
Everyday life has changed drastically over the last few years, as we now have two kids in the family (2-year-old Arvi and 4-year-old Iiris). The kids wake up on weekdays around 5–6 a.m. A light breakfast for the kids, brewing instant coffee for myself, and going through Twitter and the markets. The kids head to daycare by eight, followed by the workday. After work, I research companies, earnings reports, the Twitter feed, markets, and different valuation methods on my home computer. I often have multiple investing projects underway at once (threads, columns, investor presentations), which I work on whenever there’s a free moment. In the evening, the kids are fed and put to bed, often followed by a run, cooking with my wife, and a relaxing dinner. After nine, I frequently watch football if matches are on, while simultaneously advancing various investing-related projects. Off to bed usually between 11 p.m. and midnight.
5. How would you briefly describe yourself as an investor?
I like numbers, but not decimals. Although I sift through a lot of data, I feel overly detailed analysis provides little added value in understanding the big picture and its key drivers. In other words, DCF models are strictly for the day job. The “precision bias” is real; adding decimals to models can lead to inflated confidence in their accuracy, which, looking far into the future, is naturally extremely unlikely. Accurate is not the same as precise.
I want to learn new things constantly and get to know as many promising companies as possible. I like to invest heavily in a handful of relatively unknown companies that I strive to understand distinctly better than the average investor. By default, I always focus first on the risks (often failing at it, too) and only then on the returns. Because of this, I think I’m viewed somewhat as a “bear,” even though over my 12+ years of investing history, I’ve been more excited than cautious. The last three years, during which I’ve commented on things publicly, have just happened to be quite exceptional.
I always try to say “no” as quickly as possible so I can focus my time on opportunities that deserve it. By default, every investment I make is for over five years, although rapidly changing circumstances or facts can shift my stance sooner.
6. Could you briefly share your investing history?
During the first six months of my investing journey (2010–2011), I lost half of my lifetime savings of 20,000 euros—over 10,000 euros. I didn’t know what I was doing, so I forced myself to study. Eventually, roughly three years later (2013), I broke even, and after that, the pace picked up. Methodically, I aimed to weed out one weakness at a time, and that work continues—it likely never ends.
For over a decade now, all surplus money from my salary has gone into investing, as has any extra free time—though that has been in very short supply lately (toddler life). Over 95% of our family’s net worth is in the stock portfolio. In my concentrated portfolio, blunders and successes have occurred at a steady pace, but luckily the profits from successes have grown faster than the losses from mistakes; over the first 12 full years, accounting for all investments ever made, the average annual return has been 15.5% (vs. MSCI All Country World Index 9.9% vs. OMXHGI 8.4%).
For those interested in the long version, I have to pitch that I’ve tried to package the entire story, along with the lessons learned along the way, into my 2020 book Tähtäimessä osakkeet.
7. You’ve read an enormous amount of investment literature and studied investing extensively. Did writing an investment book change you as an investor in any way, given that you had to/were able to leverage and condense everything you learned between two covers?
Whether it’s writing columns, tweet threads, or a book, each forces you to pause and dwell on different concepts. Sometimes I get swept away by a stream of trivial information for days without learning or understanding anything new and broadening. It’s frustrating and a bad habit that I strive to shake off by any means possible.
Writing forces you to simplify, find examples, and truly dig into the subject. The greatest sense of accomplishment often comes from truly grasping simple concepts. It’s easy to build more complex maneuvers on top of them if you feel the need or if it’s beneficial. Pausing—in investing just as in life—broadens your horizons and requires even more deliberate effort in today’s world.
I am also currently working on an online stock-picking course hopefully launching by Midsummer, which has once again been a great way to force myself to pause and focus on what’s important.
8. What does your portfolio look like at the moment? How do you think about the portfolio as a whole, for example in terms of diversification?
Personally, I don’t care for diversification, though I understand it suits many people.
I want to spend so much time understanding the companies I own that owning just a few percent would feel frustrating. If a position doubled or halved, I’d barely notice. Instead, I really want to feel both the successes and the failures in my own skin.
The goal is always to keep the number of holdings under ten. My portfolio is public on Shareville, and right now the top 5 holdings make up 60% of my portfolio in total:
- Vontier 13.6%
- Keysight Technologies 13.1%
- Harrow Health 12.9%
- Berkshire Hathaway 11.1%
- Revenio Group 9.7%
9. You were educated at Aalto and studied at UC Berkeley, UW-Madison, and Stanford, as well as IMD. What have been the most important takeaways from your studies regarding investing? Has your investing helped in your day job, and vice versa?
I am glad for those experiences and fortunate to have had such educational opportunities. Abroad, what really sank in was how modest Finns are and how limited their self-belief can be—students abroad seem to possess an entirely different level of confidence, even though there’s no difference in capabilities compared to Finns. However, one rarely grows into an investor in a classroom. My academic background is in energy technology, so it provided fewer direct tools for the investing path compared to, say, purely commercial fields. On the other hand, evaluating power plant investments shares many similarities with traditional investing, so in that sense, it certainly helped. That said, schools rarely teach views that deviate from the mainstream, which at worst can be harmful to an ambitious stock picker. The efficient market hypothesis school of thought is a prime example.
In my day job, I’ve had the chance to examine the accounting of publicly listed companies, which was tremendously useful for investing in the early years. My investing hobby, in turn, supported my day job, creating a fantastic positive feedback loop for someone in their twenties. Later on, strategy entered the picture; understanding that is also a crucial part of succeeding as an investor.
Finding the angle that fits you best is one of the most important things in investing, because few learn without motivation. And if you don’t learn new things, the market has a habit of punishing you harshly.
10. Following macroeconomic trends can provide an edge in investing. What macroeconomic factors do you follow the most to inform your investing directly or indirectly?
I find tracking macro interesting, but I don’t feel I gain a significant edge over other investors from it. The bigger divergence from the mainstream comes from time perspective: while many focus on a month or a quarter, I look at multi-decade trends and try to identify the risks when reaching various extremes. Between rare extremes, there’s a lot of low-signal noise that I try not to bother my head with.
For example, employment, credit spreads, and profit margins are great metrics for capturing major shifts, but I truly look at the big picture “from very far away.”
11. What is your stock-picking process step by step? Do you have any distinct habits that others rarely use in their stock-picking processes?
This is an enormous question; one could easily talk about it for over an hour. On the Inderes podcast, it took four  (“How you look for new companies” at 3:19:55)
Briefly put, whenever I come across a previously unfamiliar company, I do a quick 15-minute overview of how the company makes its money and whether I have an appetite to dig deeper. Then I gradually move on to historical numbers, annual reports, and quarterly earnings calls. At each stage of learning, the toolkit contains a handful of key filters—subconsciously, probably dozens. With each filter, some companies are discarded. The long-list (interesting) has a few hundred companies, the short-list (closely monitored) has a few dozen, and the portfolio (holdings) has fewer than ten.
Deviating from the mainstream, I rely as little as possible on the opinions of others; often the companies I like are quite unknown to most, so getting opinions would be difficult anyway. It’s essential to form your own opinion before asking others—far too many people (out of laziness or other reasons) do the exact opposite, asking others before forming their own view.
I strongly believe in the “truffle pig tactic”: if I root through hundreds of companies even on a surface level, I am likely to find better investments for my portfolio than an investor staring solely at the Finnish OMXH25 index companies. Of course, if your return target is lower, you can get by with less effort.
12. Selling processes aren’t discussed enough. What is your process for selling stocks? Do you put as much effort into it as buying?
I spend considerably more time and effort on buying than on selling. The goal, after all, is to buy so “well” that selling is needed far less often.
Over the past couple of years, I’ve sold for a few different reasons. The most obvious is when the valuation reaches an intolerable level, e.g., P/S or EV/GP above 10+. That’s when I start trimming gradually if the valuation continues to rise without corresponding business progress. That’s what I did in Cerence’s case, for instance. At the same time, I failed miserably at executing the same thing with Semler Scientific, so there is still room for improvement in consistency.
A few years ago, I recognized my shortcomings in analyzing IBM and sold my shares. So, I learned something new, realized my mistake, and sold everything at once. Same story with my bleak adventures with Polar Power and Socket Mobile. Then occasionally, risks already identified at the time of purchase happen to materialize, warranting a reaction. That happened, for example, in the case of Semler Scientific.
13. Tell us in thirty words per company what you think of them right now.
-Berkshire Hathaway
I’ve always considered it a better alternative to diversifying via a US index fund. The company has a truly unique way of financing operations (“float”) cheaper than most, and management’s capital allocation skills via acquisitions and buybacks are top-notch.
-Fortum
Unfortunately, I cannot comment within the bounds of the law. However, I write a lot about topics that can be applied to the company if one wishes.
-QT
A fantastic Finnish tech success story; we could use more of these. Given my skill set—or lack thereof—it’s difficult to evaluate long-term demand and the true competitive moat. Personally, I’d like a greater margin of safety, even though it has dropped significantly from the peaks.
14. I see you as a well-rounded, sophisticated investor. What are your weaknesses as an investor, and how do you plan to improve them?
Thank you, but I’ve been quite inventive in finding unsophisticated ways to lose money or miss out on returns. The most important thing is to approach it with a learning mindset and improve the process after every mistake. Mistakes are valuable investments. There are many weaknesses, but here are a few:
Conviction is a double-edged sword. I spend a lot of time and effort building conviction, so when failures occur, I dwell on my thoughts for too long and don’t change my mind fast enough. Conviction has often been very useful, but finding the balance is hard. Optimizing position sizing and continually wading through counterarguments plays an important role amid uncertainty.
Likewise, I am truly bad at betting heavily on high-probability outcomes. I often put the same amount of capital to work in highly risky ideas as in safe ones. For instance, the Berkshire Hathaway position during the COVID crash at a P/B of 0.9 ($180) was such an absolute setup on a silver platter that I should have loaded up several times harder. It was practically certain that Uncle Warren himself would buy back shares at similar levels. Yet, I treated the opportunity like one offered by some risky small cap. Room for growth, and in the next similar situation, my potential development will truly be tested.
Sometimes I can focus purely on learning new things, but occasionally the urge to “do something” takes over, resulting in useless activity in the market. Rarely, if ever, has this activity been good for the big picture.
15. I think investor psychology should be talked about more, so I’ll ask: how do you practice psychological skills and mindsets in investing?
Good point. As Yogi Berra said: “Baseball is 90 percent mental. The other half is physical.” The same applies to investing.
Perhaps the most important thing is to pause and honestly dissect your own investment decisions and the key motives behind them. It’s worth reviewing both successes and failures, because it’s not always obvious whether a good outcome was driven by a sound investment process. Either way, you can learn from both good and bad outcomes.
Then, in the traditional way, it’s always worth learning from people smarter than yourself, which is why I like to read a lot on the topic. Howard Marks’s The Most Important Thing Illuminated is one of my favorites on this subject, as is Robert Cialdini’s Influence.
16. If you could pick four forum members to give you private tutoring in investing, who would you choose, why, and what would you want them to teach you?
I’m sorry, but I’m not an active enough forum user to answer this fairly. Based on my small sample, I could certainly learn a great deal from many people. The crowd here has truly diverse expertise.
17. Why do you visit the Inderes Forum, and what is the most important thread here for you?
Ultimately, I consume investment forums quite sparingly, purely due to the limited free time in my current life situation. However, I always end up returning to company-specific threads whenever something major and unexpected happens. It’s always nice to drop by to see the general mood and the community’s interpretation of the news. I can then reflect these against the opinions I had previously formed myself.
18. Do you have specific euro-denominated goals for investing, or any other kinds of goals?
At this stage, I consider myself and my family wealthy enough—our net worth, accumulated through salaried work and investing, is in the hundreds of thousands, not millions. Life lacks nothing that increases happiness that should or could be bought with money. For the love of the game, however, I personally strive for an average annual return of over 15%, which must be achieved taking into account every investment decision ever made. So, no “cherry-picking” across different portfolios or time periods—every investment ever made is included in the calculations (anything else is, in my view, a bit pretentious and pointless). After the horrific stumbles of the early years, I’m on pace with that after the first 12 years, but the learning must continue, and I very much want to keep it going. Maintaining that target will be tough, but attempting it is certainly fun.
19. It is very hard for a Rookie to learn even the basics of investing. What kind of things should someone in the Rookie’s shoes focus on?
It’s good to follow your own curiosity; that’s when motivation stays highest. Someone might get the biggest “kick” out of building a discounted cash flow model, while someone else gets it from researching the origin stories of famous companies. Both offer valuable lessons for an investor, and if you start in the “wrong place,” at worst your interest dies in the starting blocks and the lessons are never learned. So there’s no single correct answer—it depends on the individual, who knows themselves best.
For me, the most rewarding place to start is studying market bubbles, the events that led to them, and the similarities between them. Likewise, the best investor letters (Francois Rochon, Nick Sleep, Howard Marks, Warren Buffett) have been among the most interesting starting points for me, even though they already require an understanding of the basics. From there, one can draw lessons on different valuation levels and valuation methods.
20. What would you especially like to thank the forum members for?
All of your enthusiasm for investing is a primary motivation for me to create investment-related content, so I owe you a great deal. This “@Sijoittaja-alokas interviews” is also a fantastic format that has given a lot to me, and surely to others as well!
A big thank you to everyone for maintaining Finland’s best investing community and actively spreading the gospel of investing!
Thanks, Hessu, for the great answers!
I spend around 35 hours a week in one way or another on investing stuff, and I encounter so much noise and borderline useless info that it almost makes my head spin. Luckily, there are people like @Marianne_Palmu and Heikki who know how to extract the most essential points from massive amounts of data and break them down into an understandable format for us regular folks. Pretty impressive stuff when you think about it.
Nothing more to add, really. Thanks to the readers and have a great weekend!