121. Markku Kurtti
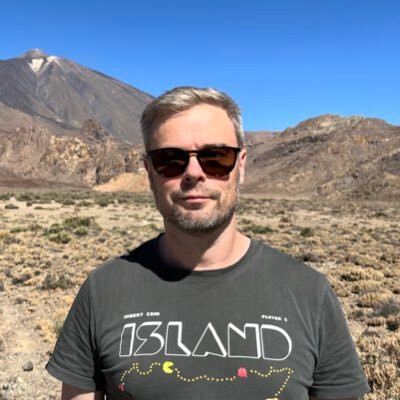
Markku Kurtti is an investor equipped with an engineer’s precision and an understanding of finance, combining data-driven analysis with strategic investing. His investment journey has spanned from the dot-com bubble’s boom-and-bust frenzy to building a systematically structured, relatively diversified portfolio.
Markku is quite an analytical and thorough guy who brings genuine knowledge, solid arguments, and real research to everything he writes. His views are grounded in deep research, and he shares his insights on his investment blog, Outcast Beta. This very high-quality and sophisticated blog offers data-backed perspectives that challenge traditional investing dogmas to some degree.
As an investor, he is realistic and analytically consistent in his risk awareness—an investor shaped through hard-earned lessons, striving to understand the deep structures of investing and their impact on long-term returns.
We could definitely use more level-headed people like Markku in this scene. 
1. Tell us who you are in fifty words.
I am an electrical engineer with an M.Sc. (Tech.) who has spent his career developing cellular data communication chips, witnessing both Nokia’s incredible rise to the top and its fall back among mere mortals. I am also a father of two elementary school-aged children. Ever since childhood, I have enjoyed making sense of the world through mathematics, which led me first toward engineering studies and later toward the investment world.
2. Tell us three things few people in public know about you.
I have managed to ride my stock portfolio through an over 90% drawdown in the aftermath of the dot-com bubble, I have significantly underweighted high-valuation US equities relative to the rest of the world over the past 10-year period, and I directly own shares in only one company: Berkshire Hathaway Inc.
3. What interests and hobbies do you have besides investing?
In my youth, I played volleyball actively, which I have now picked up again later in life. I enjoy downhill skiing, try to hit the gym with varying degrees of success, and participate in my kids’ activities as a chauffeur and assistant coach.
4. What does a typical weekday look like for you?
In the morning, wake up and feed the kids, then head off to work. The commute is just over a kilometer, so it’s a pleasant bike ride in the summer and a walk in the winter. After work, the agenda usually includes cooking and mostly the children’s hobbies. In the evenings, whenever possible, I try to make progress on my current research project for my Outcast Beta investment blog. Following investing-related discussions on X is also part of my daily routine.
5. What kind of an investor are you?
As an investor, I am fairly risk-averse. For example, I have never been 100% in equities, but typically somewhere between 60% and 90%. I don’t have so-called alpha—that is, outperformance driven by skill that deviates from market returns or other known sources of return. Consequently, I strive to exploit known sources of return, or so-called betas. The most important beta is diversified market return. The fact that I don’t possess alpha also means I don’t have stock-picking skill. Therefore, I don’t pick individual stocks either, but invest practically solely through ETFs and mutual funds.
6. What is your investment history like?
I made my first stock investments as a student during the tech frenzy of 1998 and 1999. I understood nothing about stocks other than that they could only go up. And up they went, rapidly. The key was to participate in every IPO and scrape together every penny possible on a student budget. Fortunately, it was possible to take out student loans. On Fridays, we drank fancy imported beers on virtual profits and debated whether it would take weeks or an entire year for Stonesoft to multiply. Great times; we were on top of the world and felt invincible. Then happened what wasn’t in our scenario analysis: stocks began to go down. At first, every dip was a buying opportunity, but eventually, it wasn’t anymore. Tech stocks were battered into the ground, and I humbly sold, likely right at the bottom of the bear market. I don’t know the exact number, but it was around -90%.
A hangover followed the party, and I lost my appetite for stocks for a long time. It was precisely this hangover that was the worst part of the episode: In the end, I didn’t lose a massive amount of absolute markkas or euros in the tech crash, even though the percentages were ugly, but I lost a lot of future returns because, hungover, I couldn’t bring myself to buy cheap stocks during the bear market, even though I was already working and earning new money.
However, I managed to buy my first home, so my capital wasn’t sitting completely idle in a bank account. A few years later, I started getting interested in stocks again, but this time I decided to study the subject before placing orders. I read a few classic books in the field, such as Burton Malkiel’s “A Random Walk Down Wall Street.” I had bought a few single stocks, but decided to transition entirely to index investing in 2008, right before the financial crisis. During the financial crisis, I learned that even index investing is not risk-free, as globally diversified indexes all plummeted down hand in hand.
I became fascinated by investing and the theory behind it, eventually ending up investing in factor-tilted products, such as value-weighted ETFs. This didn’t play out like the textbooks taught, either. The value factor has underperformed growth practically throughout the post-financial crisis era. Still, I became so interested in investment theory that I took a 21-month study leave and completed a Master’s degree in Finance.
7. What is your portfolio like? How have you approached its allocation, e.g., diversification?
My portfolio consists almost entirely of ETFs and index funds acquired over the years. So the portfolio is well-diversified geographically (though the US is still underweighted). However, ETF investing doesn’t necessarily mean purely passive investing. The portfolio deviates from the global market portfolio in terms of both geographic weighting and factor tilts, including, for instance, small caps as well as value and momentum-style equities. And then there’s that one single stock, Berkshire Hathaway, which can also be thought of as a zero-fee, leveraged, actively managed US fund. I fear inflation, so I have overweighted energy and mining companies, real estate (REITs), and gold miners. Over the long term (5–10 years), the correlation of all of these to the broader stock market approaches or even falls below zero, meaning they are also excellent diversifiers. I have also invested in US Treasury Inflation-Protected Securities (TIPS ETFs). And I do hold one genuinely active fund: PYN Elite, which invests in Vietnam. As a frontier market, Vietnam’s correlation with Western markets is far from perfect, once again offering diversification benefits, plus its valuation seems attractive.
8. Which company’s stock did you last buy for your portfolio, and what was your investment thesis?
As mentioned, I only own one single stock, BRK-B, which I bought, if I recall correctly, in early 2016. Back then, being underweighted in the US started making me nervous, and hopping on Warren’s train at the then-low P/B multiple felt psychologically easier than buying the broad US index. If we look at what I’ve added to my portfolio in ETF form over the past year or two, it has mainly been small-cap value companies and also real estate funds, i.e., REIT ETFs. The low relative valuation of small value stocks in both Europe and the US has made them attractive buys. I bought REIT ETFs when valuations came down following interest rate hikes and I wanted more diversification in my portfolio. In the short term, REIT ETFs tend to behave like equities, but in the long run, like direct real estate holdings. So, as a long-term investor, I view it as investing in globally diversified real estate without the dread of a tenant calling me on a Saturday night.
9. What does your stock-picking process normally look like, step by step?
I don’t pick individual stocks, but my ETF selection process always starts with the question: what would best complement my current portfolio by offering either additional diversification or an attractive expected return? Ideally, both. Additionally, I try to reflect, study, and model how different asset classes provide diversification over the long term rather than the short term, and how they have historically protected against the worst risks, such as inflation.
10. You are an engineer and hold a Master’s degree in Finance. Have you been able to leverage your engineering background in your investing? Does a finance degree provide a significant edge in investing?
In my work as an engineer, I am used to designing various tests that yield large amounts of statistical data. Data analysis has developed a certain intuition in me that helps spot phenomena behind the numbers and smell out when something is off. This is also useful in investing and in understanding markets. Studying finance helps you understand how the market and asset pricing work. Most importantly, it has helped me run various tests on empirical data and helped me understand risk. However, neither degree has granted the ability to generate true alpha. I believe that true outperformance stems more from innate talent, coupled with the commitment and sheer work ethic fueled by passion, rather than from earning degrees.
11. What are the four most important valuation metrics for you? Justify your choices.
I don’t pick stocks, so I haven’t developed a large toolkit of valuation multiples that I use. Because I view my investments top-down, typically at the ETF level, I prefer to think of valuation multiples in generalized terms. I don’t care too much which specific metric a value ETF uses, but I believe it is better to use multiple valuation metrics. Diversification is a good thing for signals (like valuation multiples) too. Relying on a single valuation multiple that performed best historically can lead to overemphasizing historical randomness in stock selection. Using multiple valuation metrics reduces this risk.
In the big picture, all decisions made based on valuation multiples lead to exposure to the value factor. More essential than an individual metric may be considering other factors simultaneously—such as sector alongside valuation—making valuation multiples more comparable across stocks. I like simple metrics, although even they can exhibit significant differences, like the commonly used P/B and P/E multiples. P/B, or rather B/P, can be thought of as a “pure” value metric, whereas P/E, or earnings yield E/P, is a kind of hybrid measure of the value factor and the profitability factor (“profitability at a reasonable price”): E/P = B/P x E/B.
12. What are your five most important sources of information in investing? Justify your choices.
I like to test how different asset classes or strategies have performed historically. That’s why my most important sources are data repositories such as Kenneth French’s Data Library and Robert Shiller’s Data. I also enjoy reading quantitative investing papers, for example from AQR, along with the accessible and often witty writings of its founder Cliff Asness. Furthermore, I discover many interesting finance professionals, discussions, and articles on X, or so-called FinTwit.
13. You run the website: https://outcastbeta.com/ Could you tell us about it? Why did you start it, and what added value can an investor gain from it for their own investing?
For years, I have conducted various data-driven studies related to stock investing. A few years ago, I began writing threads about my research on Twitter. That worked for a while, but Twitter threads proved too restrictive a format, and effectively the posts disappeared into the digital ether a few days after publication. I wanted to start documenting my research more thoroughly, which is why I founded the blog. The posts on my blog are quite theoretical, which limits their appeal to a broader audience. But the conclusions (if one believes in them) can, in my view, be useful even to an ordinary investor. Many of the articles I have written revolve around portfolio diversification and how diversification is, in practice, even more important and beneficial than is commonly thought.
14. How do you view exploiting systematic risks and behavioral factors in practice when building an investment strategy, and what tools would you recommend for assessing them?
You are likely referring to utilizing different factor premiums in investing. Factor returns can indeed be explained either by systematic risk associated with the factor (which leads to a risk premium) or alternatively by behavioral biases of the investing masses (for example, people’s tendency to extrapolate recent earnings growth far into the future, leading to overpaying for growth stocks). The most common factors utilized are size (small vs. large), value (cheap vs. expensive), momentum (past winners vs. past losers), or profitability (robust vs. weak profitability). There are many factors, but most of them are variants of these fundamental ones. The basic idea is that these factors are uncorrelated with overall market returns, so adding them to a portfolio improves diversification.
However, factor investing involves practical hurdles. Academic studies use so-called Long-Short (L/S) portfolios—meaning, for instance, the value factor is captured by going long cheap stocks and shorting (borrowing and selling) expensive stocks. The goal is to make factor returns independent of market direction, capturing the spread between cheap and expensive stocks net of costs. Yet regular investors typically don’t short; they only buy cheap stocks, leaving them with only roughly half of the factor premium. Furthermore, this so-called long-only factor investing does not offer the same diversification benefits as long-short strategies. In practice, almost all factor ETFs are implemented in a long-only fashion. Thus, retail factor investing is very different from that of institutional investors (e.g., hedge funds) and academic studies. Personally, I prefer allocating only to a select few prominent factors and doing so through ETFs, which isn’t the most optimal way, but certainly the easiest. And of course, it’s entirely possible that not all factors will perform in the future as they have in the past. The best example of this is value investing post-financial crisis.
15. Do you think geometric returns are underestimated among investors, and how would you recommend utilizing them in long-term investment strategies?
I have indeed written a lot about geometric returns and how using them in analysis can change conclusions regarding things like the benefits of diversification. In itself, I don’t think geometric returns are underappreciated by investors, because virtually all investors measure their success through compound annual growth rates (CAGR). The issue I often highlight relates more to the discrepancy between academia and practical investors. In academic research, returns are almost without exception measured using arithmetic returns (simple averages), which is often appropriate and justified, but can sometimes lead to conclusions that clash with practical reality.
For example, if a portfolio returns -50% in year one and +50% in year two, the arithmetic average return is 0%. But measured by a real-world investor, the geometric return is 0.5 * 1.5 = 0.75, resulting in an annualized return of -13.4%. In practice, the geometric mean (the metric used by real investors) is always lower than the arithmetic mean (the metric used by academics). This drag is due to the so-called volatility drag (portfolio volatility reduces compound growth, i.e., the geometric return). The widely known benefits of diversification originate from academic research and are therefore based on arithmetic returns. If we run those same analyses using geometric returns, we reach the conclusion that diversification doesn’t merely reduce risk; it also increases compound returns. Diversification is therefore far more beneficial than is generally believed and taught.
By the way, you often hear that risk isn’t volatility, but the permanent loss of capital. Well, in the world of compounding returns, volatility leads (in the form of volatility drag), in expectation over the long term, to the permanent loss of capital.
16. You truly write a lot of high-quality investing content. How useful do you find writing things down for your own investing and learning process?
Personally, I’ve noticed that writing blog posts helps my learning tremendously. A large portion of my blog posts cover topics I didn’t know much about when I started writing, but I studied the matter and simultaneously documented the learning process and findings on the blog. When you write something down for others to read, you are forced to aim for a much deeper understanding than you might otherwise bother to pursue. Almost every time, once I start writing, I realize I don’t actually understand the subject after all. That’s when you have to go back to the drawing board and research further. Primarily, my writings serve as tools for my own learning. That’s also why they might be overly detailed for a large share of readers.
17. How do you manage your emotions in investing, for instance, to avoid falling victim to FOMO and the like?
I feel that accumulating experience and knowledge helps in managing emotions when investing. Due to my temperament, I think I’m able to keep my emotions in check better than many other investors, but I’m certainly not immune to them. I definitely remember a few sleepless nights during the financial crisis, and FOMO has crept into my mind on occasion as well. Nowadays, I strive to make investment decisions based on data I have reviewed and my own quantitative tests. That helps combat things like FOMO. Having your own framework to lean on—such as valuations and what the empirical data indicates—makes it easier to avoid falling into emotion-driven traps.
18. Why do you invest? Do you have specific euro-denominated or percentage targets for your investing?
I don’t have any strict euro-denominated or percentage targets. I invest for both rainy days and sunny days. I don’t have a goal to retire at a specific age, but more broadly, I pursue the freedom and optionality that wealth brings—the ability to choose what to do with one’s life. I’ve already exercised that freedom, for example, by taking 21 months of study leave. Making a decision like that is much easier when you aren’t completely dependent on a paycheck. By default, I don’t aim for total financial independence, but increasing independence and freedom, absolutely.
19. If you had to pick two articles from your site for the Rookie to utilize in their investing journey and/or mindset, which would you choose and why?
I would choose the articles A voting machine or a weighing machine? and How much skill a concentrated stock picker needs to beat a diversified benchmark?
The point of the first article is to demonstrate how the stock market’s ‘voting machine’ nature remains dominant even over very long investment horizons. Valuation swings account for the overwhelming majority of return variance even across periods spanning a decade or decades. This doesn’t mean fundamentals don’t matter. Fundamentals are vital because they determine the expected return, but the influence of randomness does not vanish no matter how much we extend the investment horizon.
The second article aims to show how volatility drag eats away at the geometric expected return of an under-diversified portfolio, and how returns across different investment styles have diverged historically. This implies that through diversification, one can achieve higher returns. An investor who fails to diversify properly starts at a disadvantage compared to a broad index and requires skill or luck just to break even. It is also entirely possible to possess genuine stock-picking skill (alpha) and still lose out to the benchmark return with a concentrated portfolio, because volatility drag erodes your returns or because your chosen investment style lags the broader market.
20. What would you like to thank the Finnish investing community for?
Finland has a wealth of interesting and useful investing content and discussion. Just as globally, Finland has a knowledgeable FinTwit. I’ve followed discussion boards since the dot-com bubble era and the legendary AP arena. Nowadays, the torch is carried by platforms like Inderes and Sijoitustieto. In particular, investing-related YouTube and podcast offerings provide plenty of high-quality Finnish-language material. My thanks go to everyone who takes part in the conversation and creates content for us investors. Thank you also to Investor Rookie for this interview.
Thank you for the excellent answers, Markku!
This was truly a refreshingly unique interviewee whose blog is well worth following:
Genuinely top-tier material.
And of course, Markku is well worth following on X too:
In my view, Markku Kurtti is a must-follow because he delivers different, deeply useful insights in such a high-quality and content-rich manner.
Have a great weekend!