United Bankers - Real Asset Manager

An article from UB about the sustainability of data centers, as these are projects spanning decades.

“Data center projects are investments of an exceptional scale, with impacts extending for decades. Therefore, their development is a strategic choice linked to the development of the municipality and society as a whole.”

Risto Siilasmaa also touched on the subject from a strategic perspective on LinkedIn. Data centers consume a massive amount of electricity, which is not produced in infinite supply even in Finland. We must carefully consider which projects truly create value and strengthen security here in Europe.

"That is why we should favor investments that:
• bring long-term tax revenue
• create significant employment
• strengthen the security of Finland and Europe

Not all data centers meet these criteria.
Especially in a situation where vast amounts of electricity are consumed, but the value and decision-making power flow out of Finland."

2 Likes

Really good interview with UB on AMWatch (paywall).

Below are the most important highlights:

“Our primary aim is to double our AUM to EUR 10bn by 2028. This isn’t a target we will be able to reach without making acquisitions, so we are looking for acquisition targets both in Finland and overseas,” Ojanperä says at the company’s office in Helsinki.

“The ideal acquisition target would be an international company with an AUM of around EUR 0.5–1bn,” Ojanperä says and adds:

Companies in the Nordic countries – particularly in Sweden – are on United Bankers’ radar, though firms in German-speaking countries may also be of interest, according to Ojanperä.

“The target company does not necessarily need to be an asset or wealth manager; it could also be a niche alternative manager in forestry or real estate, a distributor with strong sales know-how and a solid team, or a consultancy with expertise in a specific field,” Ojanperä explains.

The fact that the AUM target won’t be reached without M&A is nothing new, but specifying the targets this precisely hasn’t been done publicly before. Of course, with those same specs (+ cultural fit), practically every asset manager in Helsinki would like to find something to buy :smiley:

“Fourton, whose funds we acquired, has an AUM of EUR 150m, and that kind of size is easy to digest. However, if one acquires a company from overseas, it is very difficult to buy a company with such a small AUM and then run it from Finland.”

Good to remember that international M&A is a difficult game in this business.

“Our product portfolio is already in good shape, but I believe we can still expand it somewhat with new offerings. Outside Finland, we are focusing on growth in German-speaking countries and the DACH region, in France, the Netherlands and Belgium alongside the Nordics – where we have offices in Helsinki and Stockholm,” says Ojanperä.

The product offering could still use a bit of expansion; I think this refers to closed-end PE funds, which I’m still expecting by the end of the year.

1 Like

A quite significant deal from UB to kick off the weekend. @Sauli_Vilen will have something to chew on over the weekend.

10 Likes

Indeed, UB made a fairly decent-sized deal by acquiring Fondita! Here is my morning comment :page_facing_up:

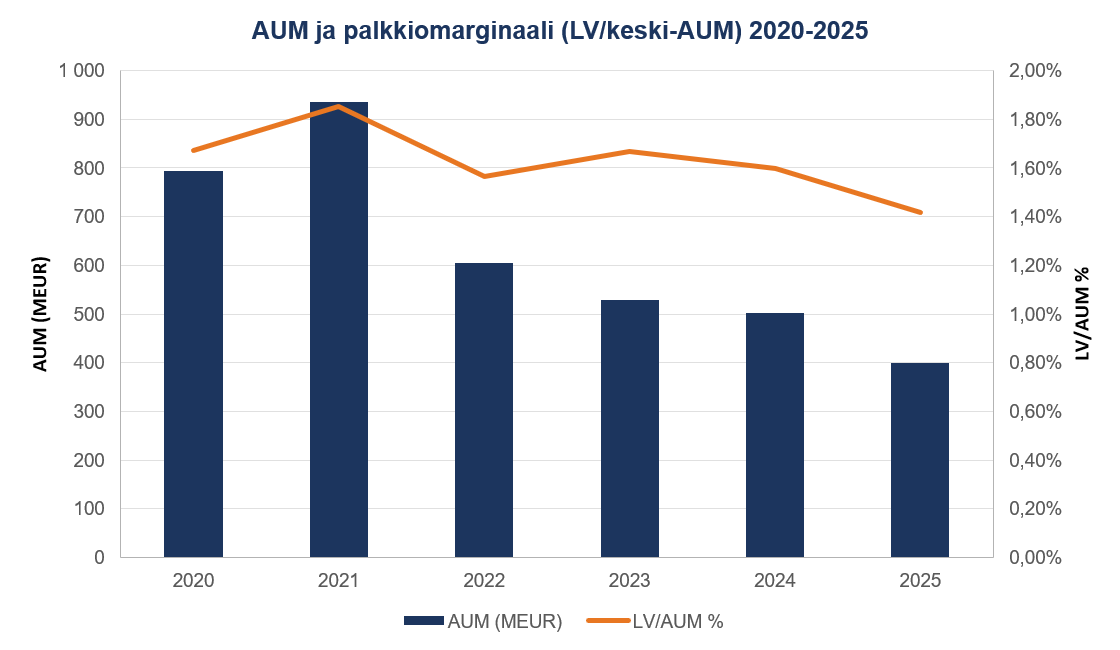
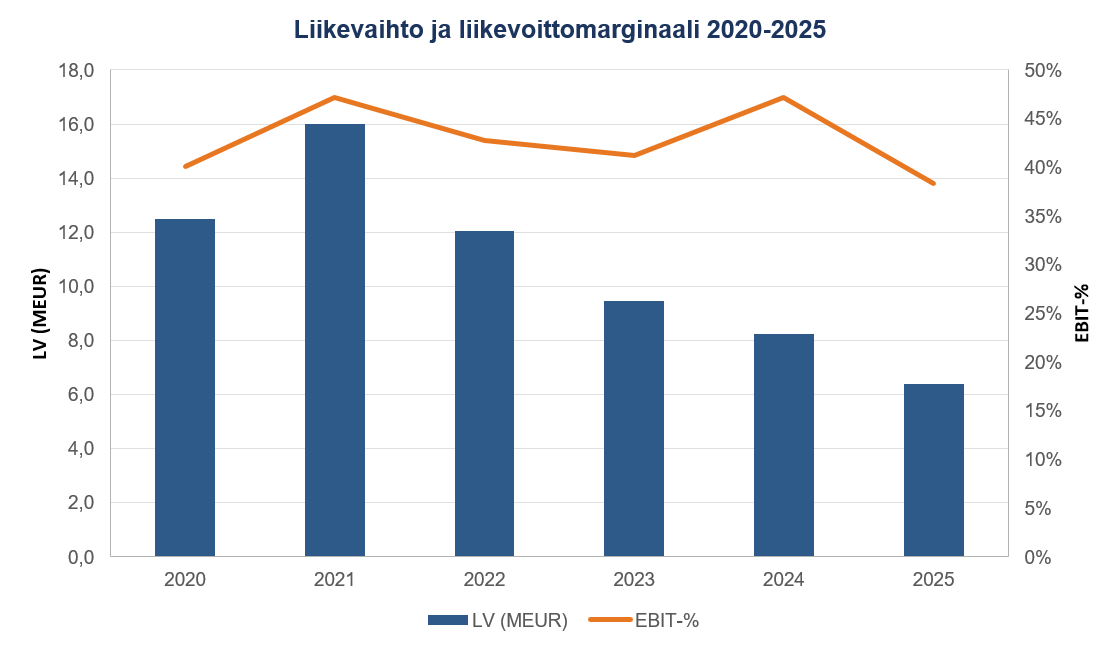
Fondita’s AUM (Assets Under Management) has dropped significantly in recent years. The reason is the decline in small-cap stocks, which has been reflected in the weak performance of the funds. This, in turn, has led to substantial net redemptions and valuation decreases. The fee margin has held up reasonably well and remains good. :down_right_arrow:

Naturally, when AUM decreases, revenue and profit also decline. The company is, of course, still very profitable, but it’s telling that in 2021 they made more operating profit than they currently make in revenue. Fondita hardly charges any performance fees, meaning the fees are essentially entirely recurring. :chart_decreasing:

In my opinion, this is a clear bet from UB on small-cap stocks and active portfolio management. If UB manages to reverse that AUM decline, the deal will easily create significant value, as the 2025 EV/EBIT is only ~4.6x. Based on 2026 figures, we are likely in the 6-8x range. In the best-case scenario, UB is buying Fondita right at the trough for small caps, and just the reversal of this trend will push AUM into brisk growth in the coming years. :bar_chart:

Was it a good deal? As I told Kauppalehti, it’s “okay.” UB didn’t strictly need Fondita, but at that price, the expected values are certainly in place. :slot_machine:

Here is my KL comment as well: https://www.kauppalehti.fi/uutiset/a/c51a3bb4-cb07-4317-b930-5bd2e54b4c67

11 Likes

In my opinion, the UB share price is starting to show signs of a bubble :bubbles: Almost a 50 percent increase in a year + dividend. Based on Inderes’ forecasts, the P/E for the current year is already over 21 and will remain high, above the 17 level next year as well. It’s hard to justify buying the stock at premium multiples when no significant/new growth drivers have emerged… Was it the acquisition of smaller boutiques that started this upward trend? Note: over the last month, the stock has been traded at around a thousand shares daily, which means a trading volume of about twenty thousand euros. Has low liquidity been driving this upward after all?:eyes:

6 Likes

Here is the pre-earnings report from Sale as UB prepares to release its results on Thursday, August 20th :slight_smile:

We are raising our target price for UB to 21.0 euros (prev. 19.0 EUR) in line with our increased earnings forecasts. At the same time, we are lowering our recommendation to sell (prev. reduce) as the stock’s valuation has detached from its fundamentals.

1 Like

Personally, I haven’t been able to come up with any rational reason for this stock price rally. The company’s H1 has been, at best, mediocre, with new sales remaining sluggish. Sure, performance fees are pouring in thanks to the stellar performance of UB Metsä, but that doesn’t justify a nearly €100 million jump in market capitalization. An excellent opportunity for UB shareholders to take profits!

9 Likes

Sale I will be hosting the UB earnings live stream, which starts at 8:50 :smiling_face_with_sunglasses:

2 Likes

Salo had UB’s CEO John Ojanperä in the hot seat :slight_smile:

Topics:

00:00 Introduction
00:04 Current status/Check-in
01:22 Fondita
02:49 Integration
04:50 International acquisitions
06:43 Fee distribution
08:44 Alternatives
10:10 Asset management sales
12:30 Market situation
14:37 International sales

1 Like

Sale has published a new company report on United Bankers :slight_smile:

Despite missing estimates, the H1 report was largely in line with our expectations, and we have only made minor downward adjustments to our forecasts. We still expect the company to show strong earnings growth in the coming years, and overall, the company’s outlook is good. However, the stock has already priced this in quite aggressively, and the valuation is high by all metrics.

United Bankers’ CEO John Ojanperä was there to talk about their company, United Bankers, as an investment. :slight_smile:

2 Likes