Owen Smith, head of audiobooks at Spotify, said the company had secured partnerships with both Bonnier and Storytel’s publishing companies.
Hmm, so Storytel has sold some rights to Spotify, and when you combine this with the CFO’s purchases yesterday (0.8 million SEK) after Spotify’s announcement, could there be something positive behind this, or am I just on hopium?
One would think that some announcement would have been made about this by now?
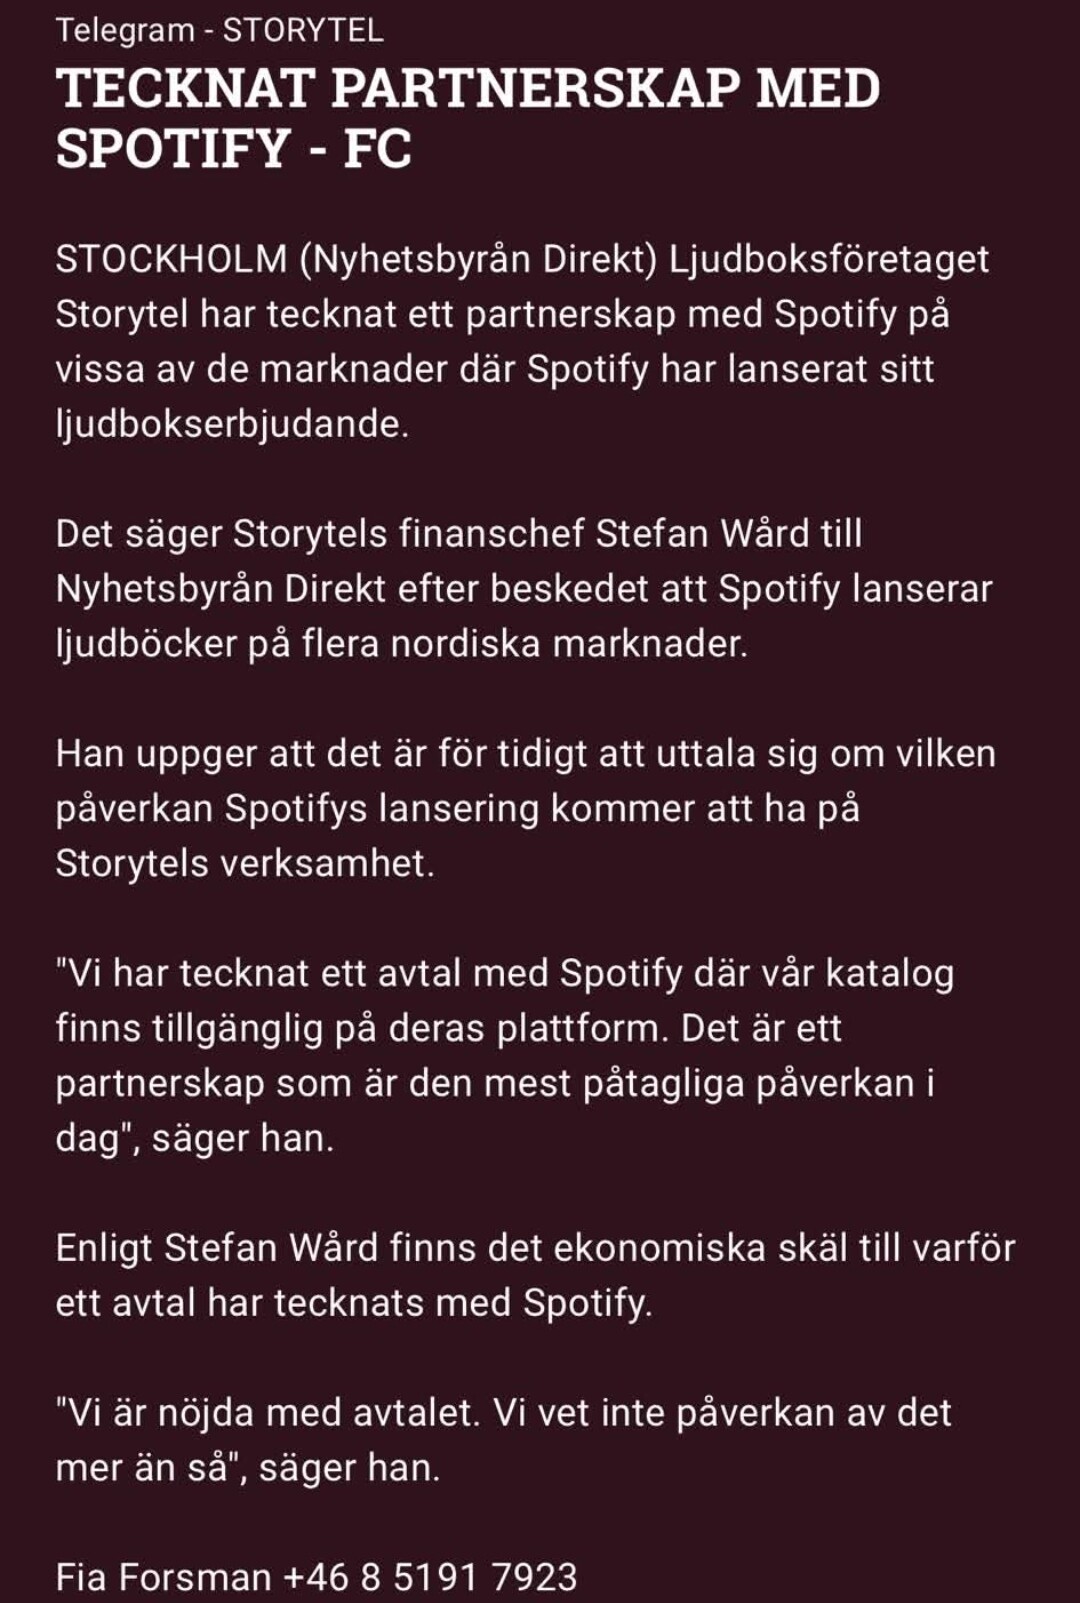
(edit) No, it actually means that Spotify has made some agreements with Storytel Books and StorySide, which are Storytel’s publishing companies.
So, some agreement has been made regarding Storytel’s selection on economic grounds, but they cannot predict what Spotify’s entry into the market will lead to.
“Storytel Group entered 2026 with clear momentum, supported by robust subscriber growth, continued margin expansion, and strong cash flow generation”, says Bodil Eriksson Torp, CEO Storytel Group.
Q1 Highlights
Net sales amounted to SEK 979m (953) for the period.
Net sales growth of 7.9% in constant exchange rates (CER).
Streaming net sales growth of 7.4% at CER. External Publishing net sales growth of 9.2% at CER.
Adjusted EBITDA margin of 17.0% (14.1%), driven by improved profitability in both business areas.
Operating profit increased 61% from SEK 55m to 88m.
Net profit amounted to SEK 86m (19), with basic and diluted EPS of SEK 1.06 (0.20).
Net debt amounted to SEK -220m (116), reflecting strong cash flow generation.
New segment structure improving transparency into our international growth engine.
Paying subscribers amounted to 2.74m (2.53), with net additions of +72k in the period, on track to exceed 3m in 2027.
Nordic paying subscribers amounted to 1.34m (1.28), with net additions of +11k in the period.
Europe paying subscribers amounted to 1.06m (0.94), surpassing 1m for the first time, driven by Poland and the Netherlands.
Group ARPU (SEK/month) amounted to SEK 113 (120), decreased by 5.5%, with FX accounting for 85% of the decline.
Outlook 2026
Adjusted EBITDA guidance of at least SEK 870m for 2026.
“A strong quarter in which our subscriber base grew by 80,000 paying subscribers – the largest increase since 2023. This, together with a continued increase in the adjusted EBITDA margin on a rolling twelve-month basis and net sales growth of 16.5% at constant exchange rates, enables us to confirm our full-year guidance,” says Bodil Eriksson Torp, CEO of Storytel Group.
Third quarter 2026 ● Net sales amounted to SEK 1,179m (1,013).
● Net sales growth of 16.5% at constant exchange rates (CER), of which 11.7% organic.
● Publishing external net sales increased by 53.8% CER, of which 26.6% organic.
● Gross margin amounted to 45.3% (45.4%).
● Adjusted EBITDA margin amounted to 22.7% (22.9%).
● Operating profit increased 16% to 176m (152).
● Net profit amounted to 151m (138), with earnings per share of SEK 1.83 (1.69) after dilution.
● Paying subscribers increased by 80k (64k) during the quarter to 2.83m (2.63), up 7.6% YoY.
● ARPU (SEK/month) amounted to 119.6 (118.1).
● Buyback of B shares of up to 300m initiated in August.
January–September 2026
● Net sales amounted to SEK 3,229m (2,925).
● Net sales growth of 12.4% CER, of which 10.1% organic.
● Gross margin amounted to 45.6% (45.0%).
● Adjusted EBITDA margin amounted to 19.8% (18.0%).
● Operating profit increased 32% to 382m (289).
● Net profit amounted to 338m (204), with earnings per share of SEK 4.07 (2.43) after dilution.
● Paying subscribers increased by 163k during the period.
● Net debt amounted to −132m (23), corresponding to −0.15x adjusted EBITDA (R12M).
Outlook 2026
Full-year 2026 adjusted EBITDA guidance of SEK 900m is confirmed.
The buzz around the company has quieted down, but quietly behind the scenes, it keeps chugging along in the right direction. For several years now, they’ve been improving the bottom line with moderate growth instead of following the previous strategy that prioritized global expansion, and the results have been quite sweet for shareholders. The share price has quintupled from late 2023 levels.
It seems Spotify’s entry into the market hasn’t been able to eat away at Storytel’s user base. Instead, they are reporting the strongest subscriber growth since 2023.
My own thoughts are a bit mixed. The company is performing well and showing no signs of weakness, but I wonder how long profitability can continue to expand without returning to a more ambitious growth trajectory? In terms of growth, this quarter was already a bit closer to what you’d expect from a growth company, but even that came mostly from the publishing side of the business.