A brief introduction to you.
Sifter researches and analyzes listed companies around the world. We do this work for the Sifter fund, Sifterfund.com
The fund is 100% invested in quality companies worldwide, in all market conditions (Long only)
Focused portfolio, 30 companies (we research approx. 100 companies annually)
Our investment style is quality investing
We strongly believe in fundamental company analysis
Why are we here in the forum?
Inderes asked us to share our analyses with the community. We hope you get ideas and thoughts from these to support your own analysis work. We do not provide investment advice. Everyone should draw their own conclusions.
It would be great to get your feedback and views on these companies and analyses.
If these reports are useful, we will occasionally add a new case for you to read and evaluate.
We also aim to answer your questions within reasonable limits; let’s see how it goes.
Many thanks again to Sifter for allowing us to distribute your analysis through Inderes’ channels. Our intention is indeed that, at regular intervals, Sifter will release one case for discussion in the service with Finnish key points and then the full analysis report in English.
We started with Costco, and you can read more about it through the link below.
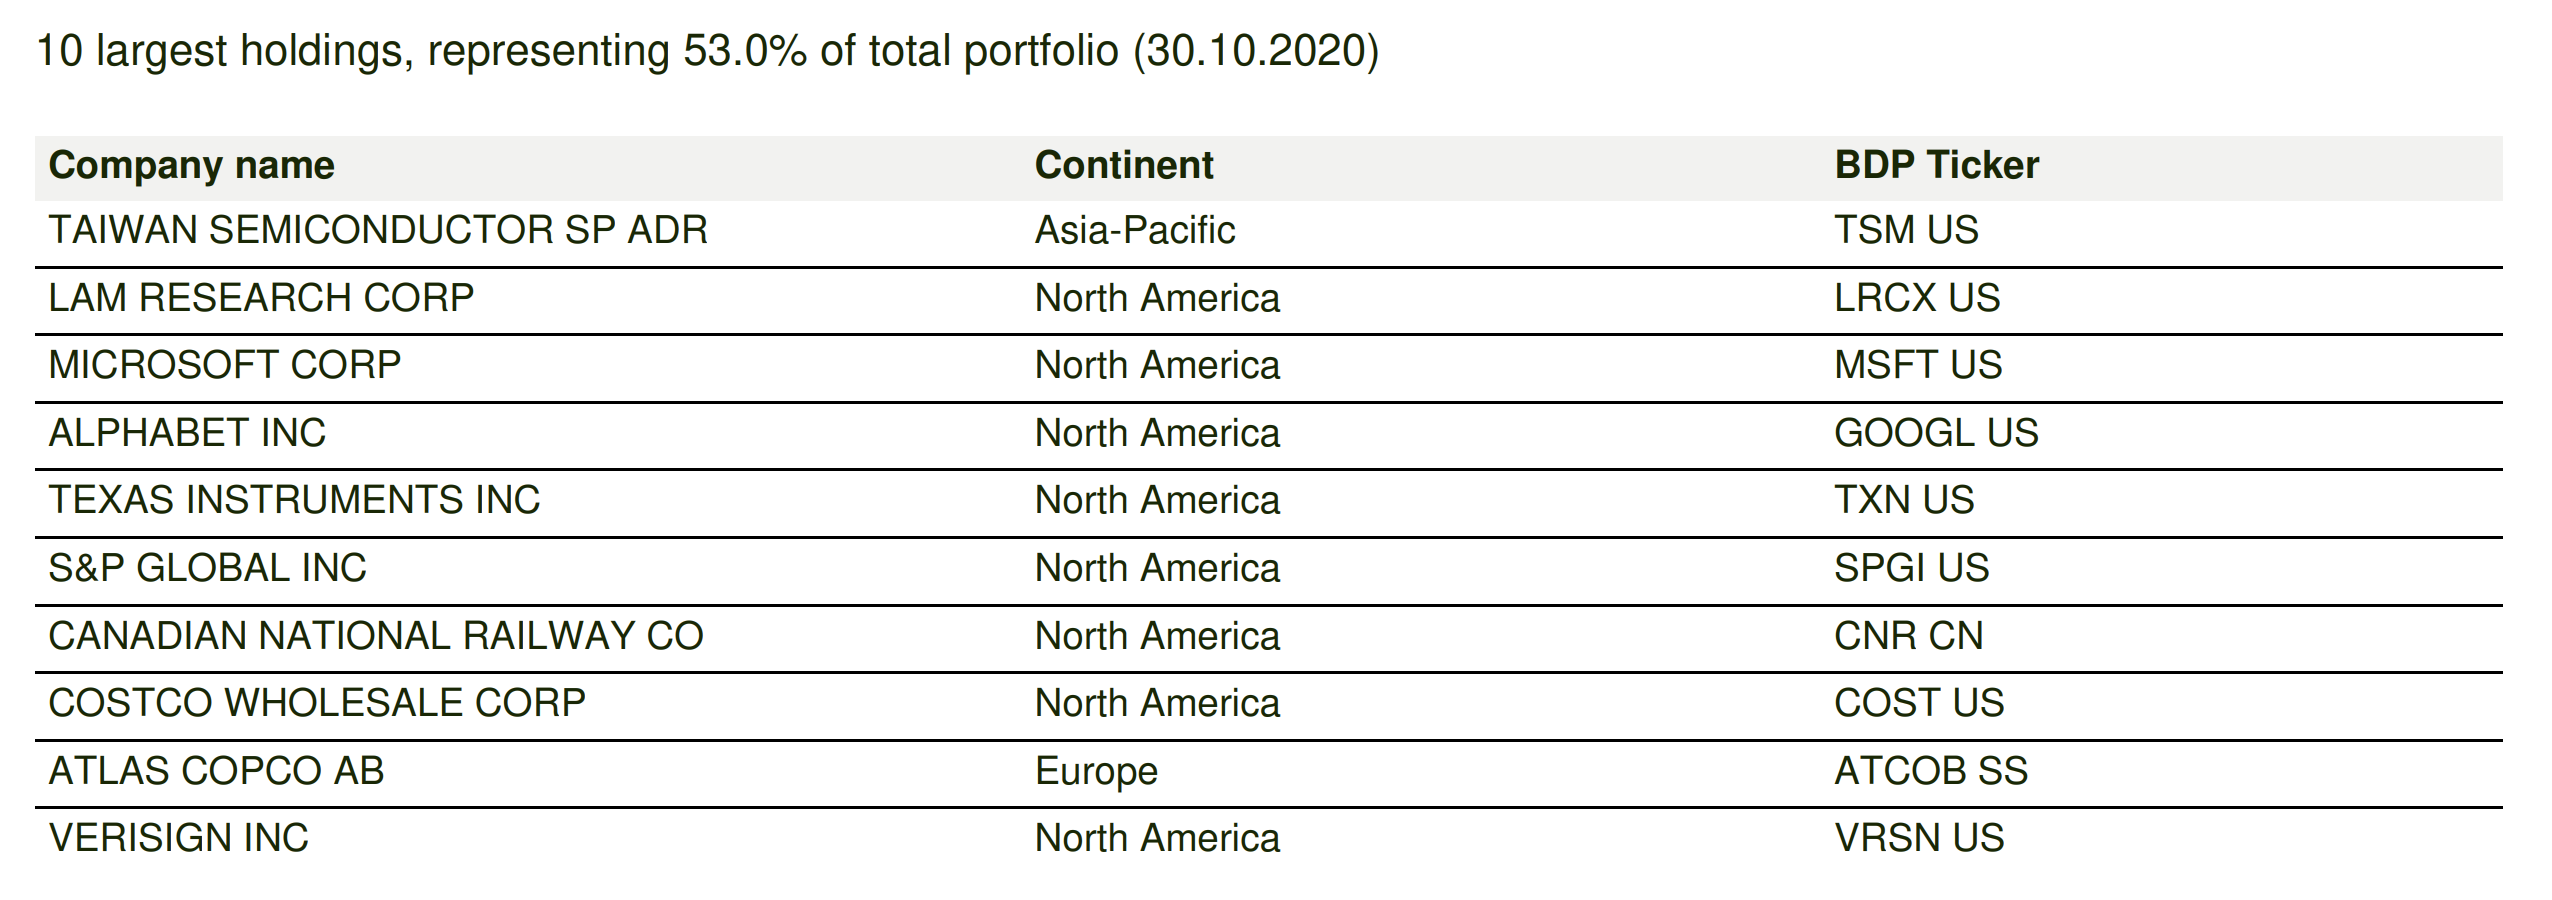
Sifter’s portfolio also appears to include Taiwan Semiconductor, Microsoft, Alphabet, and Atlas Copco, among others. Through this, you can suggest which companies you would particularly like to read an analysis about.
Hey, I watched the video. How do you at Sifter define it? My own experience is that it’s called a value stock when it can’t be justified by growth or balance sheet figures, but it would be nice to own the company. And as a clarifying question, once you’ve chosen a value stock, how do you know when the company loses that title?
Microsoft! An interesting company, and yesterday, while watching a Sijoituskoulu Harvia episode, it occurred to me that it’s easy to get involved with tech giants, even though understanding them is complex, and now cloud services are involved.
You mentioned Air Liquide. We were investors in it for a long time (5 years), but we divested from the company, if I recall correctly, in November 2019. The reason for the sale was based on the justifications below:
Sifter motivation to sell Air Liquide (in November 2019)
Air Liquide has never been one of our strongest companies in terms of competitive advantages and the company has for a long time posted ROIC numbers less than 10%.
In addition, the company has been indebted since the Airgas acquisition in 2016 with a net debt to EBITDA ratio of 3x.
The products the company sells are very commodity-like as these mostly consist of industrial gases.
The redeeming factor for Air Liquide has been the fixed pipeline network to customers’ facilities, but this potential has mostly been tapped and the company has expanded more into disposable industrial gas bottles in which the competition is intense between Air Liquide, Linde Group, Praxair and others.
The future revenue mix will be more geared towards this exposed element in which product differentiation and customer captivity is hard to come by.
This year, Air Liquide has risen 12.5%, which is a few percentage points better than Sifter’s portfolio. We no longer follow the company.
I don’t quite grasp your question, but as a recap, Sifter’s investment philosophy is: 1) Based on historical figures, the company must already have a track record of making money, and 2) the earning model and competitive advantages must be understandable and strong enough for us to believe that the company’s money-making will grow in the future. Therefore, we can pay a bit more for some companies if their future 5-year earnings encourage us to buy them. Thus, balance sheet value, etc., is not a basis for our purchasing.
Hi T3r00,
You can find the fund’s top 10 investments here
While we believe in openness and transparent operations, we don’t disclose the names and weights of all 30 companies in the fund.
However, our website does provide information about many of the companies we’ve invested in and why.
Santeri
Hi Iltsu,
Microsoft has been one of Sifter’s longest-standing investments. It has been added to and reduced at times. Its weighting is now approximately 6% of the fund’s value.
You are right that the importance of cloud services over the years has brought a lot more to consider, as Amazon, Microsoft, and Alphabet have all invested in this business.
Now it seems that all cloud service providers are growing rapidly, but for us, the biggest question is to understand whether any of these service providers can differentiate themselves with this service, or whether it will become a commodity, i.e., the sale of capacity, which, with oversupply, turns into price competition.
The greatest thing about these big tech giants is their ability to innovate new services, which create new businesses worth billions; this is rarely seen in industrial players.
I’m currently reading through Sifter’s report on iRobot, and I have a couple of points regarding Terra (the robotic lawnmower, not yet widely available). Here in the Nordic markets, Husqvarna sells similar models under its own name, not Gardena, as mentioned in the report. Another, more important point concerns area learning: with competitors, installing boundary wires almost requires a professional with their equipment, which isn’t well-suited for e-commerce. iRobot’s “Terra” version, on the other hand, only needs a few easily installed beacons to find its way back to the charging station. This could be an interesting competitive advantage. How much does it tolerate, or rather, how much does it learn to avoid bushes and other obstacles in the area to be mowed? Finnish yards are rarely football fields (a generalization). For those using boundary wires, obstacles are sectioned off with separate wires, for example, around bushes. The overall impression from the report is that iRobot has good future prospects and a lot of market still left, and perhaps these Terras and others are then additional potential options.
Sifter is dropping new analysis to brighten up the holidays. If I recall correctly, Atlas Copco has been called the jewel of the Stockholm stock exchange at some point.
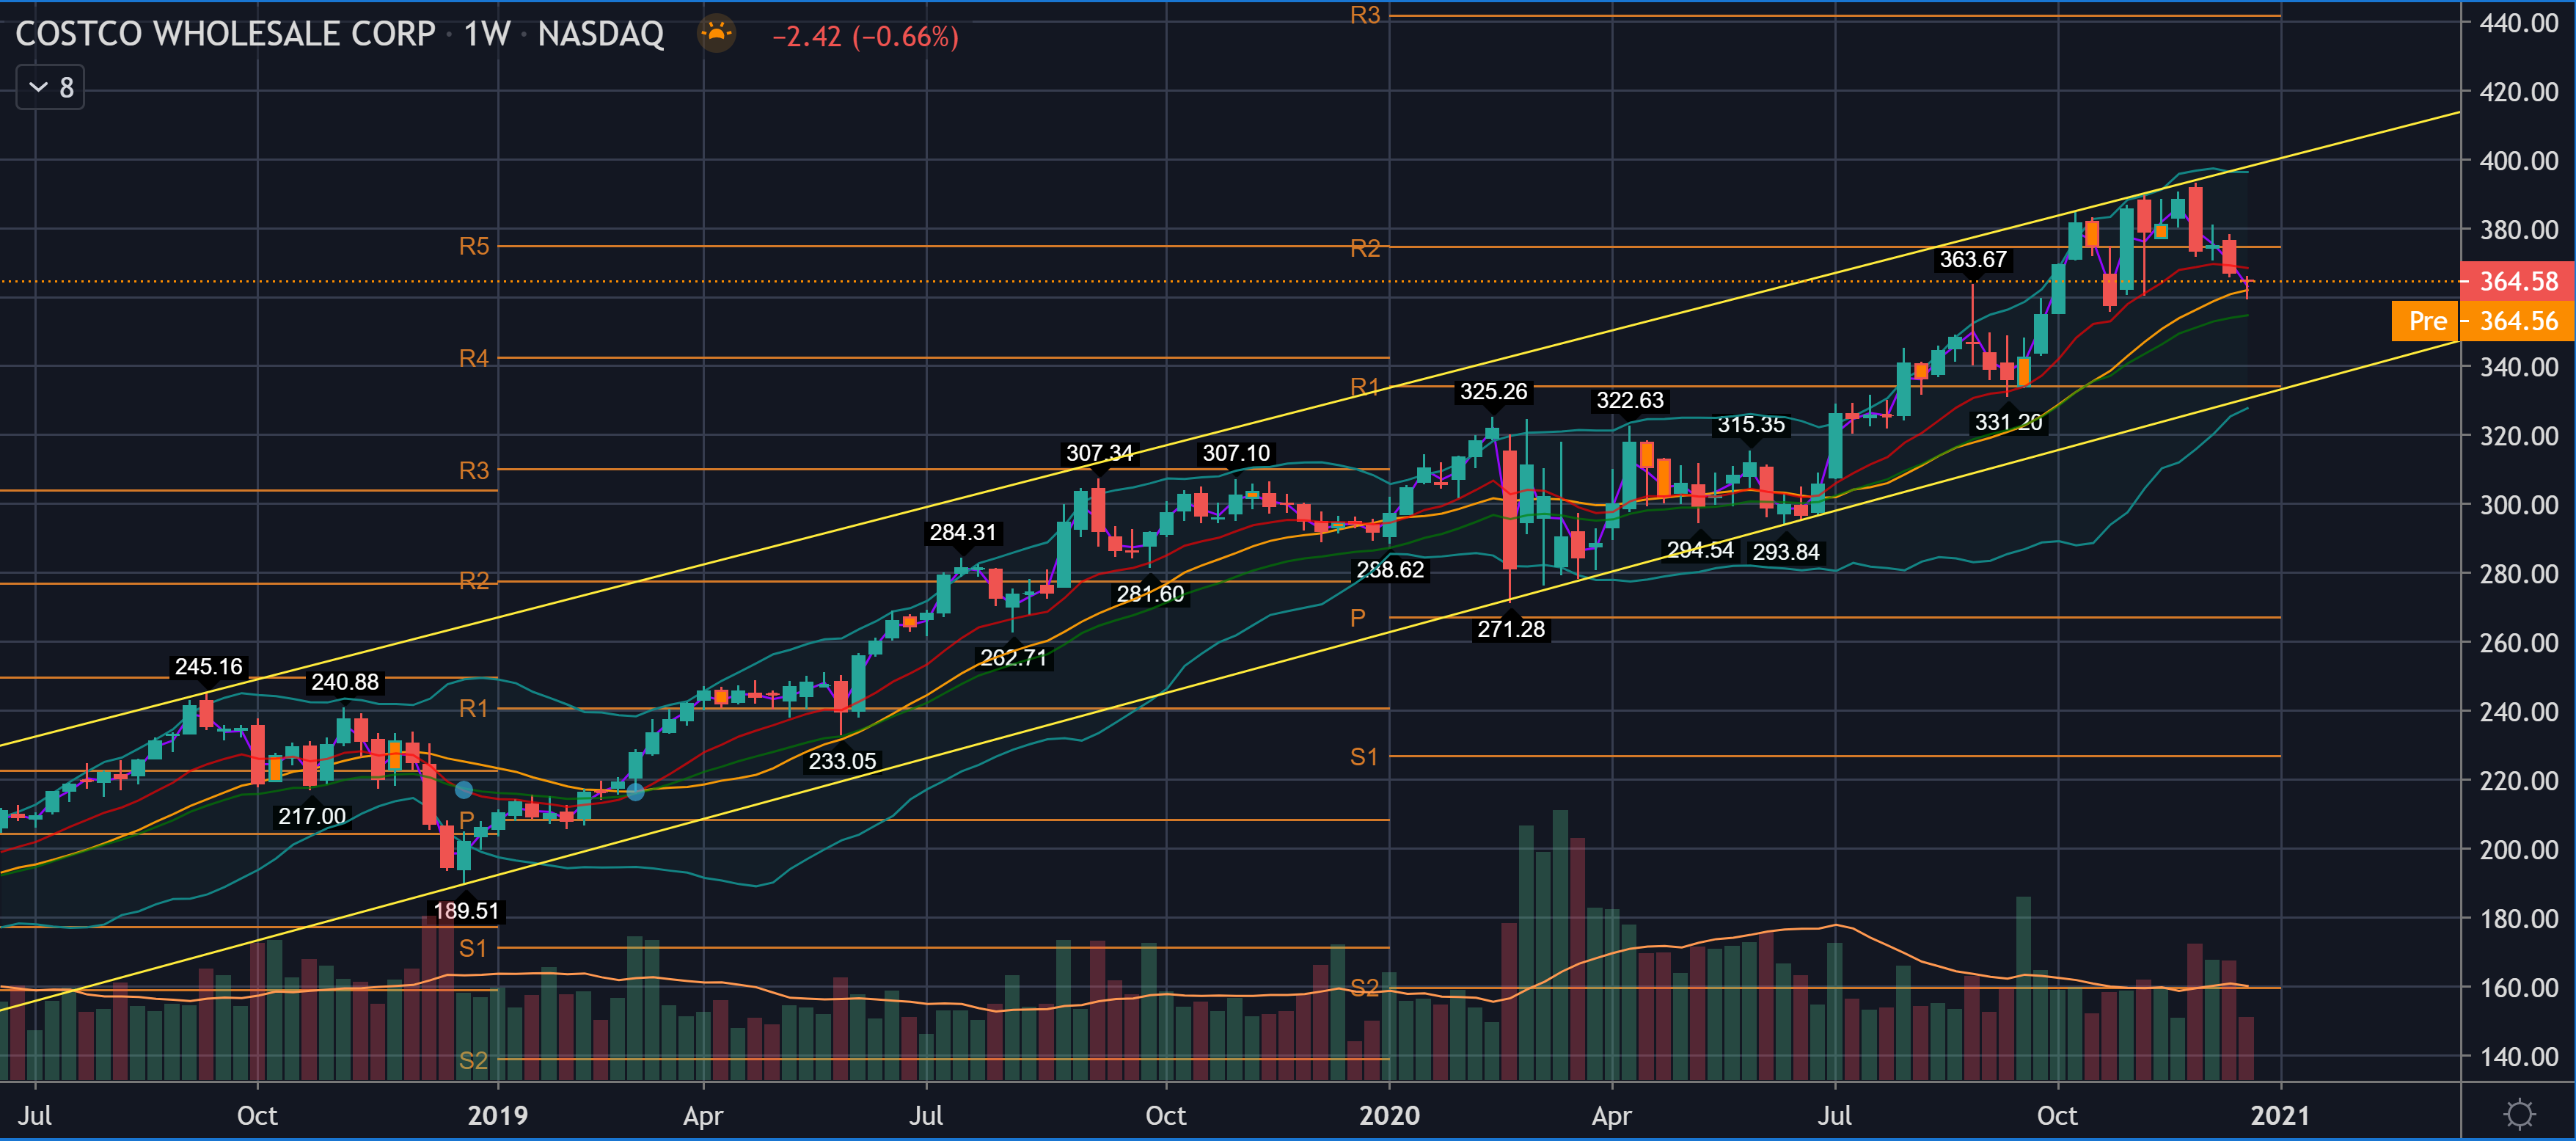
From a technical analysis perspective, COST is in a long upward channel and has started moving towards its lower edge. A meeting point would occur at 345-350, depending on the speed of the decline.
The earnings result was good, but wasn’t the growth in membership numbers sufficient for the market?
"
Membership fee income came in at $860.9 million, up $57 million or 7.1%. Ex FX, it would have been up $54 million or 6.7%. During the quarter, we opened eight new units. In terms of renewal rates, our U.S. and Canada renewal rate as of the end of Q1 ‘21 was 90.9%. That compares to a quarter ago of 91%. And worldwide, it was 88.4%, which was the same as it was a quarter ago. Now the U.S.
and Canada’s rate of 90.9%, compared to the 91%, this 0.1% decline was primarily a result of what we believe to be the deferred renewals in Canada due to the pandemic. For example, traffic or frequency in our Canada warehouses in Q1 came in at a minus 1.3%, compared to a plus 7.6% figure in the United States. By the way, the U.S. renewal rate was the same at both quarters’ end.
"
Hi T3r00,
Here’s the analysis link for the train company. This was done in 2018 and the document has not been updated. We do a quarterly “health check” for the company. I’ll post the next health check here.
 It would be interesting to read Sifter’s view on S&P Global!

 If I recall correctly, Atlas Copco has been called the jewel of the Stockholm stock exchange at some point.