True, the report itself is absolutely terrible reading, but then again, so were the forecasts. 5- was quite alright.
1 Like
According to Dagens Industri, the corrections relate to the amount of SBB’s loan obligations. SBB had retroactively corrected the total value of its short-maturity loans to 14.5 billion crowns, whereas the company originally reported the figure as 11.4 billion. The correction was based on a reclassification of long-maturity loans as short-maturity loans.
Individual numerical errors in interim reports are not uncommon for listed companies, but companies usually communicate corrections transparently through separate stock exchange releases. According to DI, the Stockholm Stock Exchange and the Swedish Financial Supervisory Authority have declined to comment on the case or any potential sanctions SBB might face.
2 Likes
S&P has also downgraded the rating to actual junk status, CCC+. This was the third downgrade within consecutive calendar months, and apart from the first one, the cuts have been quite steep. The main reason is a failure in liquidity management; interest-bearing debts maturing over the next 12 months clearly exceed available sources of liquidity.
EDIT: This indeed came to mind because the DI article also mentioned that the company had not updated the rating change on its investor pages, even though a week had already passed. However, it is now there today:
4 Likes
The CFO is leaving and SBB’s share price is tanking. Not a strong signal for the future.
A financial journalist from Dagens Industri simply commented “aktien är slut” (the stock is finished). Briefly summarizing the DI video — anything left for the shareholder after the creditors have taken their share is a bonus. And if anything is left, one should be pleasantly surprised.
Back on May 11, @DayTraderXL linked a screenshot where the CFO dumped their shares. Now they are following suit.
1 Like
I’ve been wondering if the CFO’s departure is part of the new CEO’s “house cleaning.” After all, he was the CFO of Castellum before SBB, so he knows real estate finance and so on extremely well. This is just speculation, of course, as I wipe the sweat off my brow and stare at the falling share price.
Hemsö received 1bn SEK / €84m in financing. I wonder if they’ll buy SBB’s properties in Finland.
Edit. Or in Sweden. And they would still have time to close the deals by Sept 15 or the end of September to get them into this quarter.
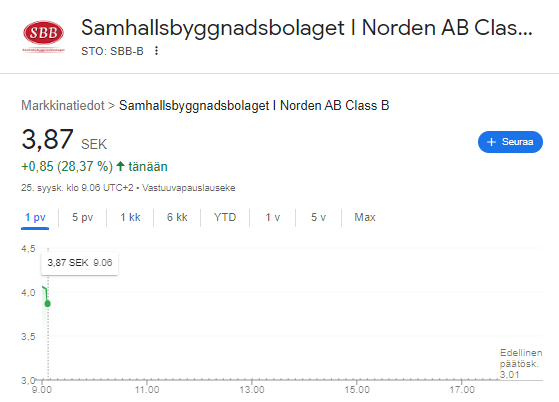
At least the market has reacted positively to the news, and maybe my own faith in the company is starting to slowly return as well. Although I still think there’s a risk that the Swedish Central Bank might raise interest rates a bit. This, of course, wouldn’t be good for SBB.
The repayment of the internal loan is practically sufficient to cover the bond maturing in 2024. In itself, I don’t understand why there is such a celebration on the stock exchange. Liquidity remains shaky, and further measures are needed to prevent the company from reaching an impasse. In fact, credit metrics might even weaken slightly following this maneuver: ICR, because the subsidiary’s income is removed from the income statement, and LTV, because properties are removed from the balance sheet…
The proposed IPO of the Residential division or bringing in co-investors should, for its part, help significantly, but the market is currently so frozen that there don’t seem to be the prerequisites for it. I don’t know how much this new reporting structure will actually improve access to bank financing as management suggests, but if that is the case, it would be a great thing and, in my opinion, positive in itself.
The bond market is closed to the company, and what the company needs most urgently is some form of equity financing so that banks would be more comfortable with financing the company.
2 Likes
The company’s CEO has been buying both B and D shares. What do you think, is there light at the end of the tunnel or is this a completely hopeless case?
Paywall.
1 Like
There is no paywall. And blah blah blah, just to meet the character limit.
1 Like
Hi and greetings from Sweden!
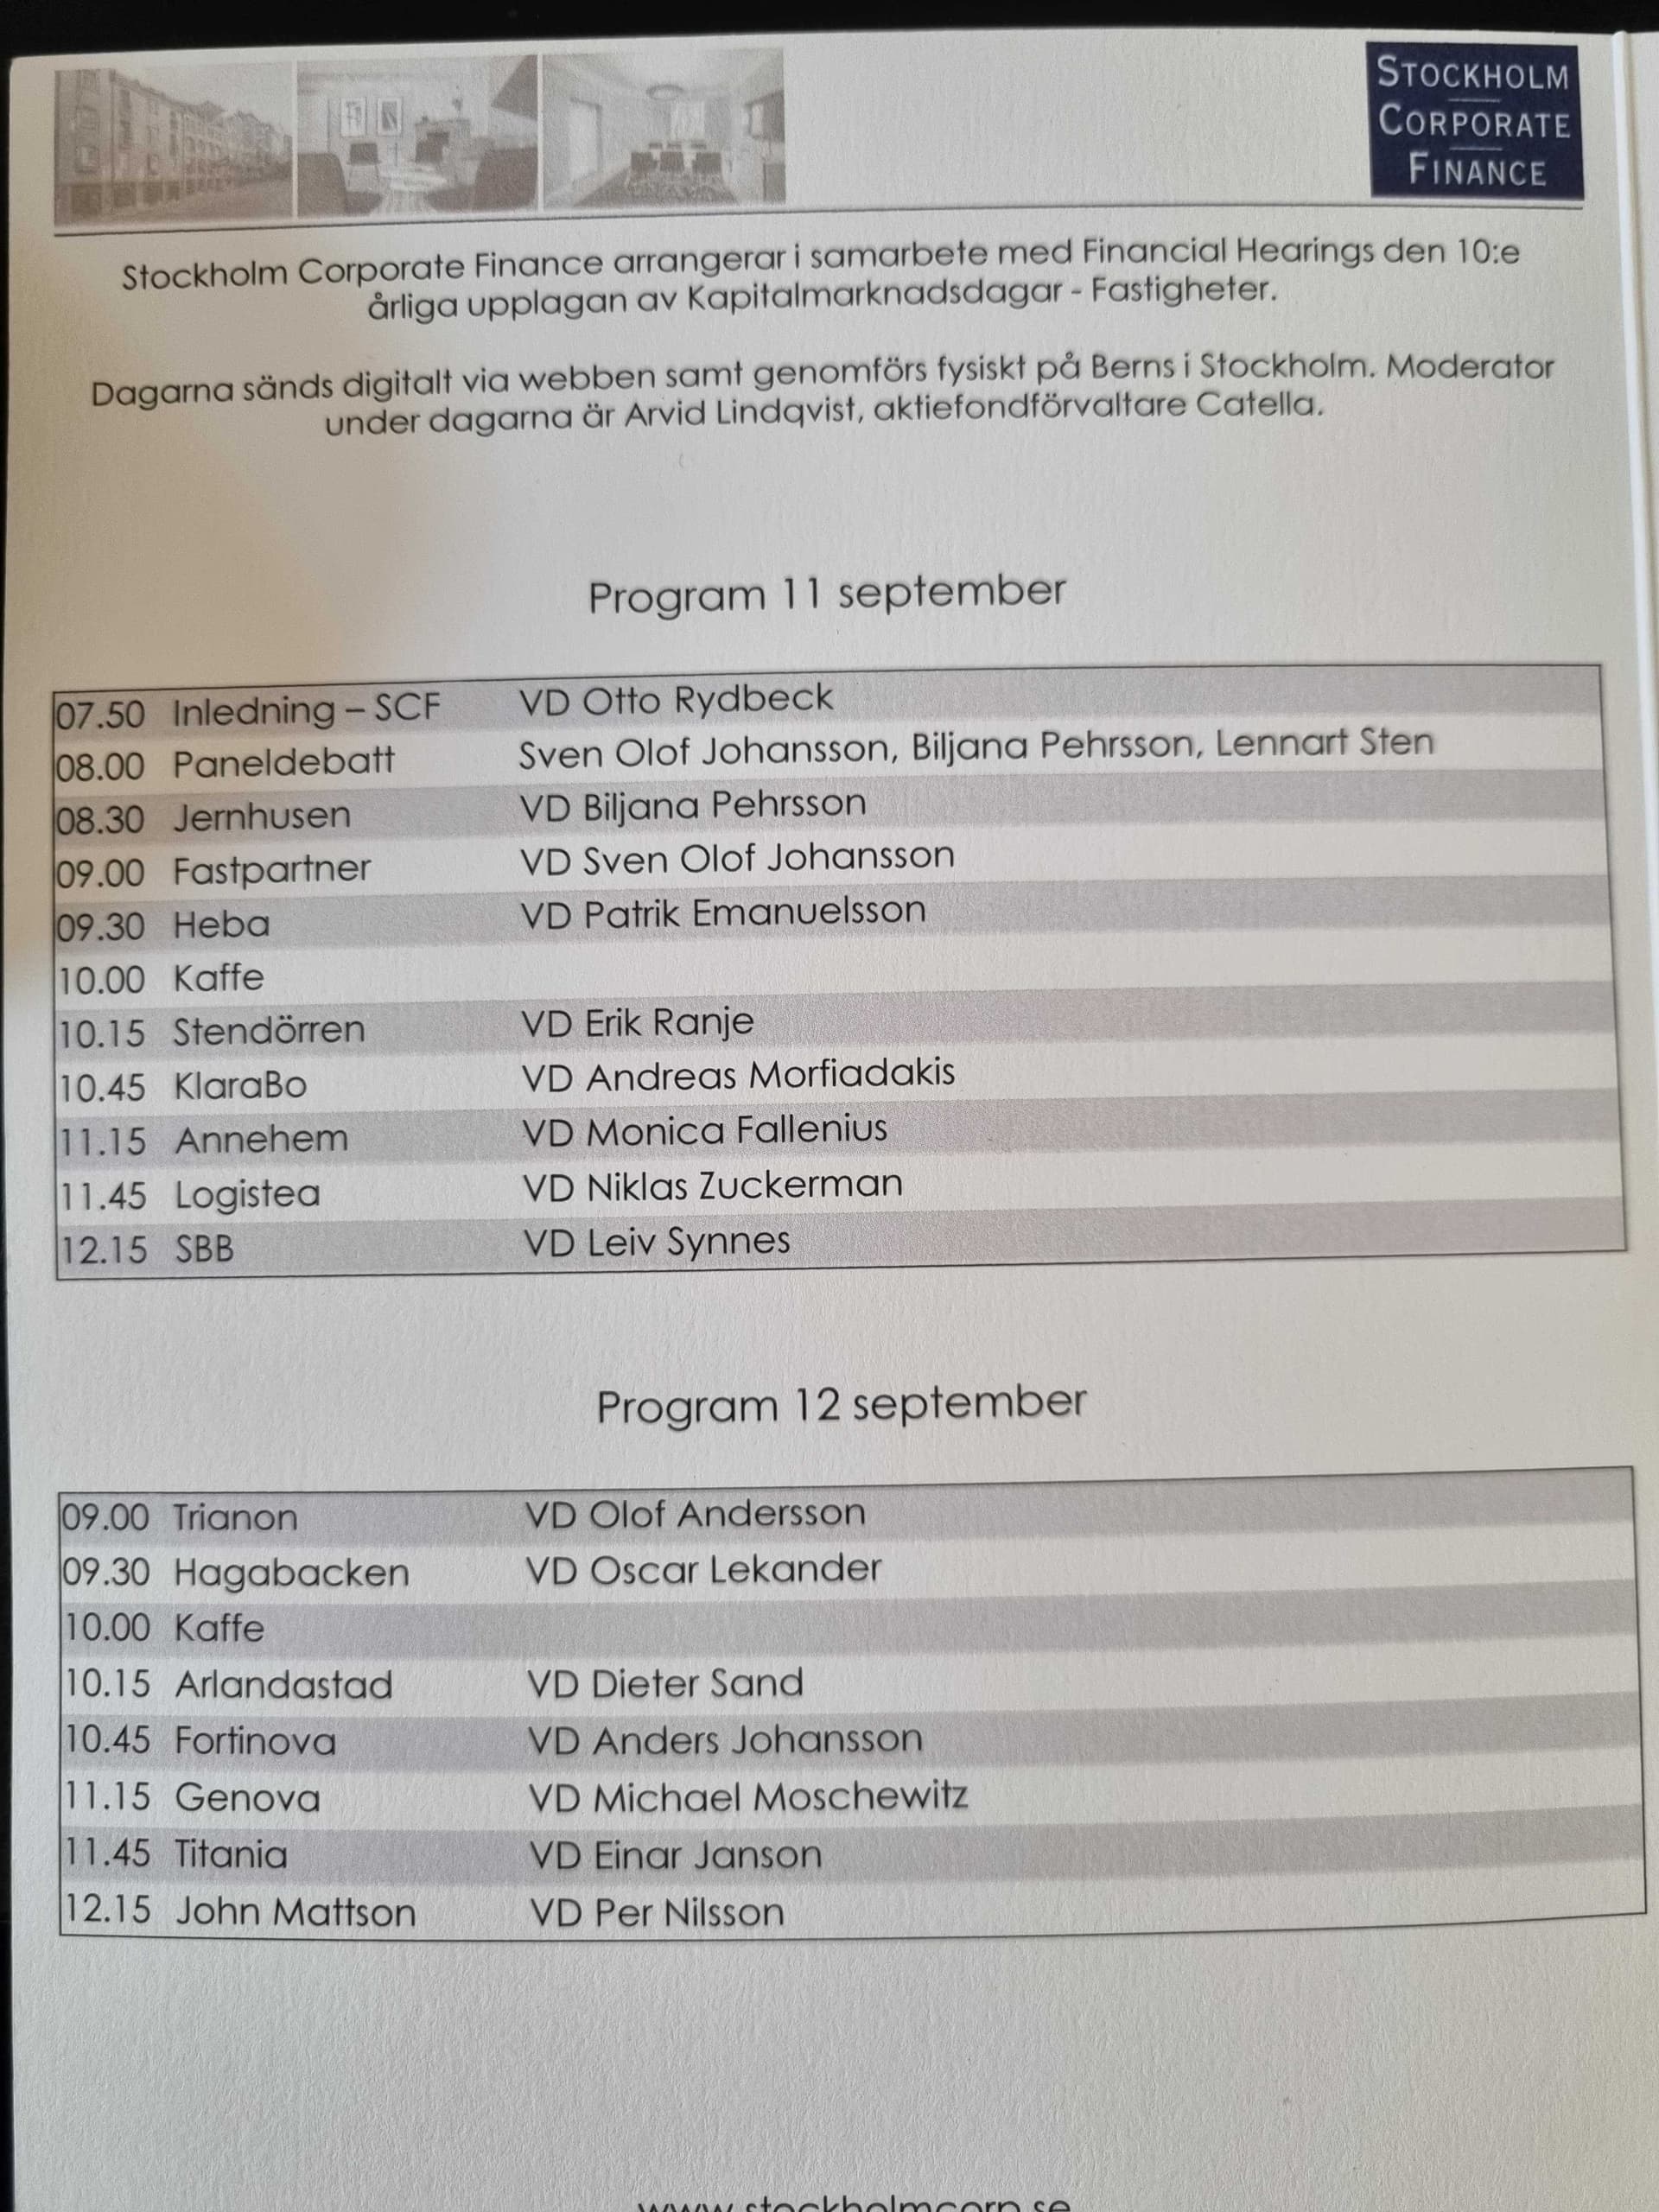
Leiv Synnes took the reins about a year ago and has since kept a fairly low profile in the media. Last week, in connection with an event organized by Stockholm Corporate Finance, we got the opportunity for an interview  !
https://www.inderes.se/videos/sbbs-leiv-synnes-det-finns-en-orsak-till-varfor-akelius-ar-rik
Here is the program:
**
**
Other CEO interviews (with a direct link to the respective CEO’s presentation for each interview). Good stuff - generally speaking:
5 Likes
Could someone smarter explain what the press release published on May 13th is practically about, regarding the corporate arrangement (Strategic ownership interest) Aker - PPI - SSB?
- Aker will own 9.08% of SBB going forward
- Aker will own 24.56% of PPI going forward
Benefits for SBB at least due to the fact that a 10x company now owns almost 10% of it
SBB also owns 33.4% of PPI
1 Like
Apparently a major move:
This company was on my research list a couple of years ago, but it was so confusing with its separate share classes and in poor financial health that I skipped it. It would be interesting, however, to see some discussion if its finances were now on a bit more stable ground and the company was investable.
2 Likes
It would be good to get some thoughts on this after the latest developments. The situation seems to have improved with the deals. SBB’s share of PPI is closer to 40%, and AKER/APG’s ownership in PPI also grows from 23% to 33% as a result. Among other developments, SBB’s debt problem is postponed.
Apparently, SBB D-shares are hot, as there is a possibility for a larger dividend later, when dividend payments might resume.
The B-share, on the other hand, behaves irrationally to good news (strong selling pressure), as it is the most shorted stock on the Swedish stock exchange.
1 Like
In this interview from September, SBB’s CFO comments on the direct question of when the D-share will start paying dividends again:
1 Like
1 Like
Is anyone else still following this? I find it really hard to keep up with this company because almost all the texts are only available in Swedish, and the company’s balance sheet and financial position are really murky.
Yesterday’s result apparently didn’t satisfy the investment community, as the reaction was around -20%, and there are still plenty of shorts, currently 16% of the outstanding shares.
A sleepy video clip about the quarterly results; it should jump to the SBB i Norden section:

It would be interesting to examine more closely what the situation is with this crisis-ridden company nowadays (though less interesting than when I bought it, as my position has shrunk) if I could just find a place to start.
1 Like