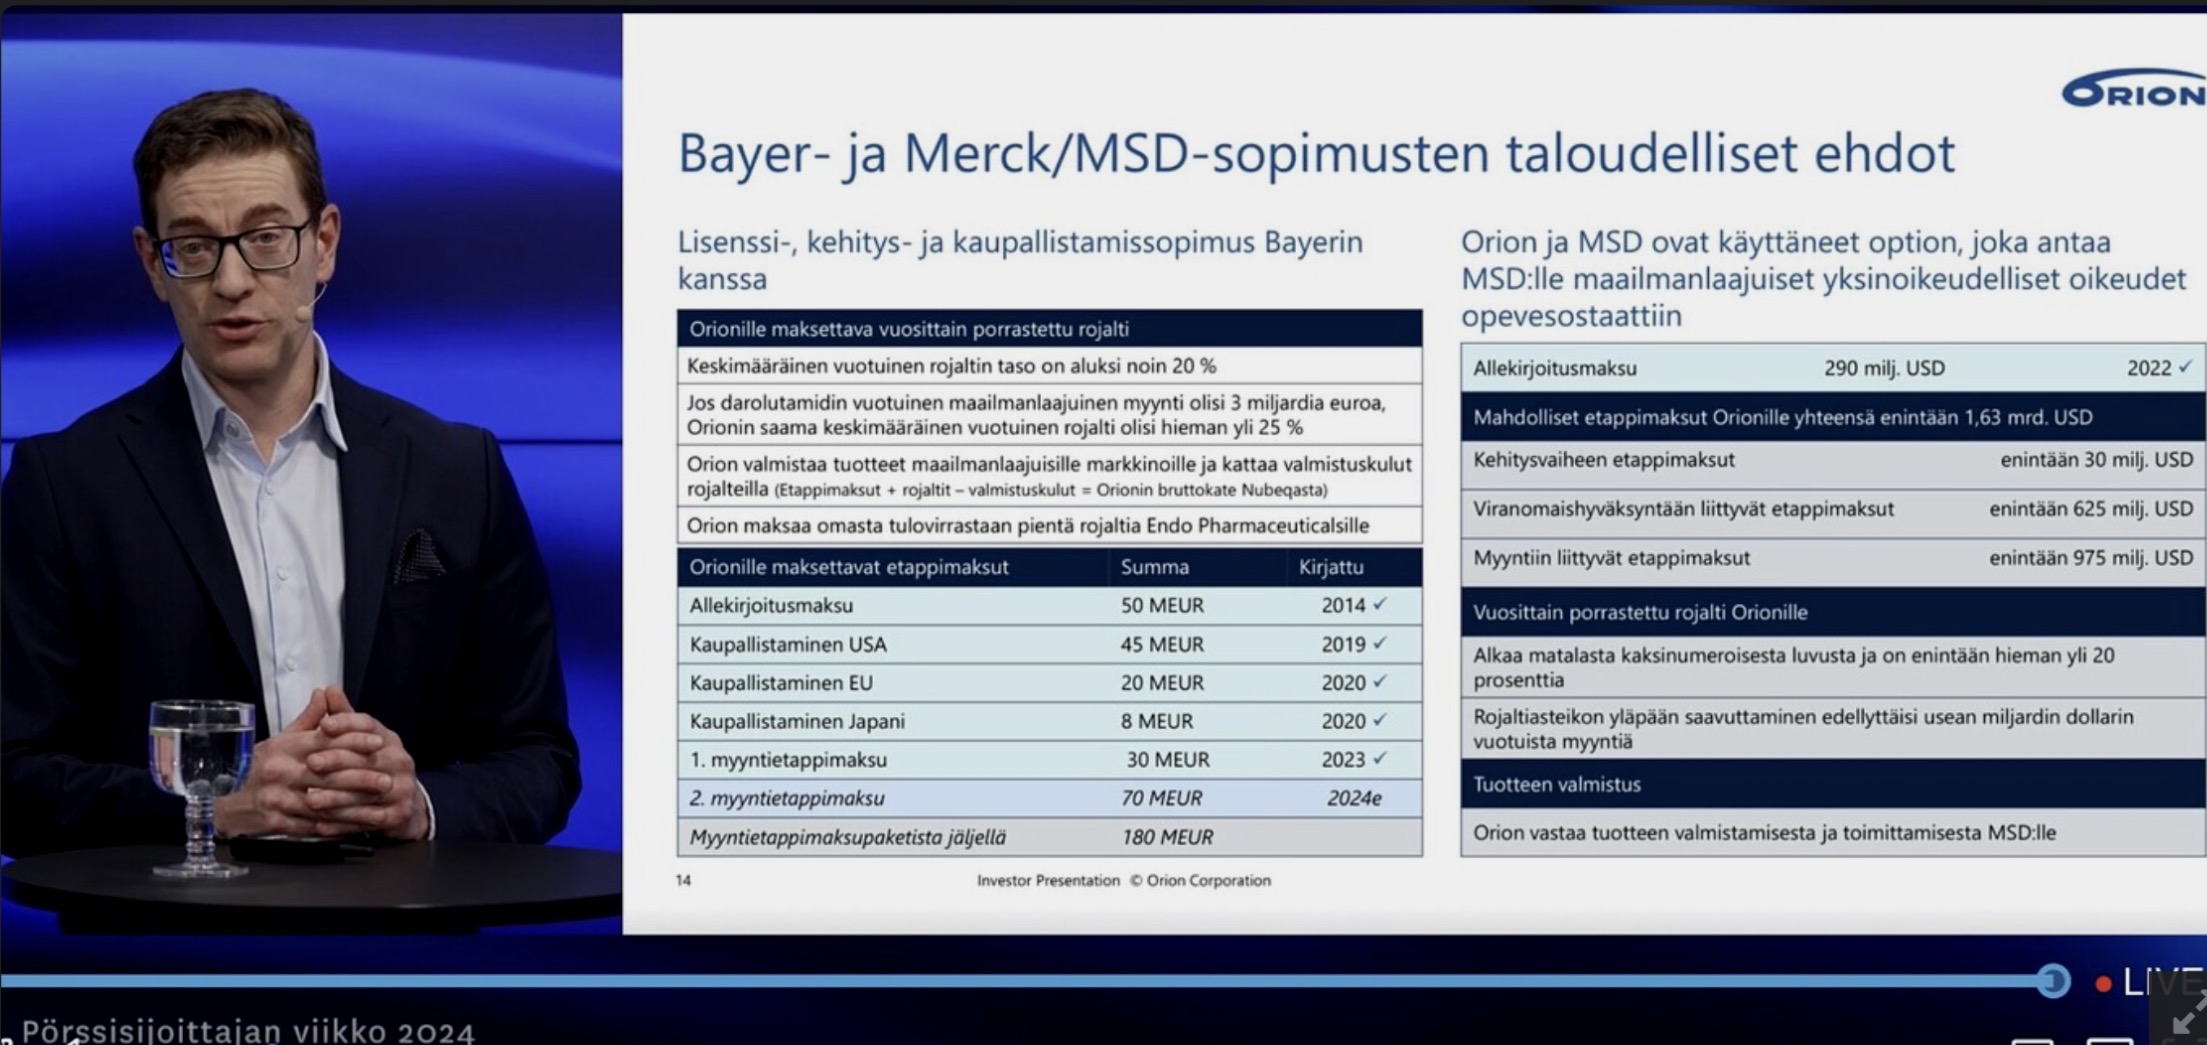
That slide shows royalties. Nubeqa and then MSD’s drug. For Nubeqa, it doesn’t stay at 20% for sales over 3 billion, but rises to 25%. And manufacturing costs are also mentioned in calculating the margin.
9 Likes
Thanks! This is good information. Now we’re over the threshold and the milestone payments are already in the pocket. It looks increasingly likely that Orion is becoming a very profitable company.
2 Likes
Orion’s CEO Liisa Hurme talked with Antti about the Q3 results and other recent topics 
Topics:
(00:00) Introduction
(00:11) ”An excellent quarter”
(00:23) Nubeqa behind the strong result
(01:25) Organizational change
(04:07) Manufacturing of Nubeqa’s active ingredient
(05:08) DASL-HiCaP study
(05:44) Significance of biosimilars
(07:23) Progress of ODM-216
(08:29) Long-term outlook
5 Likes
Here is a company report on Orion by Siltanen following Q3 :)\n\n> Orion’s Q3 was once again strong. Earnings clearly beat our estimates, and revenue was in line with expectations. The earnings beat was driven by stronger-than-expected growth in high-margin Nubeqa royalties. We are raising our earnings forecasts for the coming years as Nubeqa reaches its potential faster than anticipated. However, long-term forecasts remain largely unchanged, as they already factor in significant success for Nubeqa. We revise our target price to EUR 90 (previously EUR 87) in line with the forecast changes and reiterate our Reduce recommendation, as we believe the share valuation already prices in most of the potential for the coming years.\n\nOrion Q3'26: Jälleen vahva tulosneljännes - Inderes
4 Likes
 Thanks for the fresh report, @Antti_Siltanen.
In it, you estimate that lower competitor prices could put price pressure on Nubeqa starting from 2028. However, Xtandi’s negotiated Medicare price is already $7,004 / 30 days starting January 1, 2027. That is 48% below the 2024 list price, so not the current net price.
What is the reasoning behind that 2028 timing based on? Could the impact already be seen in 2027? Insurers steer drug choices too. Are Nubeqa’s benefits and the growth in patient numbers enough to offset the price drop?
- CMS original publication, price table on page 2: https://www.cms.gov/files/document/fact-sheet-negotiated-prices-ipay-2027.pdf
1 Like
Hi, very good and relevant questions for the investment case! I think there could already be some minor impact in 2027, but in terms of scale it would still be small enough to be overshadowed by the overall Nubeqa picture. So, I took a bit of a shortcut with my wording. Reasons why I consider the '27 impact to be small:
- In many cases, it is likely easy for doctors to justify Nubeqa based on its milder side effects.
- As I understand it, the medication cannot be switched for current patients because cancer drugs are “protected” under Medicare. In other words, the impact would mainly concern new patients.
- The market entry of generic enzalutamide will, as far as I understand, only affect insurer policies starting in 2028. Price negotiations for Nubeqa will, based on my understanding, take place in spring 2027.
In our forecast, Nubeqa continues largely with its current strong momentum next year. A small extra boost will still come from reaching the top royalty tier slightly earlier again. In 2028, growth then slows down for the aforementioned reasons, and in 2029 it stalls as a result of the IRA. From 2030 onwards, there will be growth again from indication expansions, until Nubeqa’s revenue turns into a decline starting in 2033 due to patent expirations.
In those figures for Orion, there are also future milestones modeled with a 50% probability, for example for opevesostat, which is why the above isn’t reflected quite so straightforwardly in the group-level forecasts.
The best estimate for Nubeqa’s 2027 will certainly come from Bayer’s guidance, which will presumably be provided in connection with the Q4 report in February.
11 Likes