What are your thoughts on Orion as an investment right now?
Has anyone looked more closely into the potential of the R&D side? Among other things, the phase 3 trial results for the prostate cancer drug were supposed to be published in September. How much could the project, if successful, increase earnings in the 2020s, for example? @Tottoropoika
I see the laws and regulations imposed by governments (especially Finland) that cut into profits as a brake on earnings growth. Competition is fierce, as there are many producers of generic products.
On the other hand, total drug consumption will certainly increase in the future due to, among other things, the aging population and advances in medical science.
Well, if the drug is new, it still has patent protection. In my opinion, Orion has at least one quite recent hurdle in the domestic sector, namely Oriola’s weakened position in general. The general attitude of pharmacies towards Oriola has deteriorated, which indirectly also affects Orion, as Orion’s products are delivered through Oriola. On the other hand, Orion is still, in my opinion, in absolute favor with Finnish drug users, now and certainly for a long time to come.
It remains to be seen how Tamro’s future plans will affect products that are not ordered through it - i.e., Orion’s products, among others.
The aging population is an age-old argument, but it goes in various directions. The population is aging, but that growth does not guarantee certain profits for all pharmaceutical companies. Only some will succeed.
‘’ Orion is in the lead by volume, trading at 31.49 euros, down 6.59 percent. The price is being pressured by a recommendation change from Jefferies, which lowered Orion’s target price to 23.40 euros from the previous 30.20 euros. The recommendation is now ‘underperform’, when it was previously ‘hold’.
The bank does not consider Orion’s share return sufficient to justify its current valuation level. According to Jefferies, Orion relies too heavily on Easyhaler and Darolutamide, and needs new flagship products. This forces the company to keep R&D costs high. ‘’
What do you think about Jefferies’ target price? Inderes and Nordea both have target prices over 30 euros. Relying on Easyhaler is good, at least, because it cannot be switched to inhalers from other companies at the pharmacy. As far as I understand, user feedback on the inhaler is also positive.
Based on research results, Darolutamide has better selectivity and safety profile compared to other APEs in the same drug group. It’s difficult to say how significant these more favorable properties will turn out to be for patients in real life. However, Darolutamide will certainly gain market access.
I think I’ll buy more if the price drops to around 27-28 euros
I already managed to make one quick trade (30.85-31.07) as I thought that we were already quite low on a daily basis.
However, I don’t normally hold trades over earnings reports, which was a profitable pattern once again.
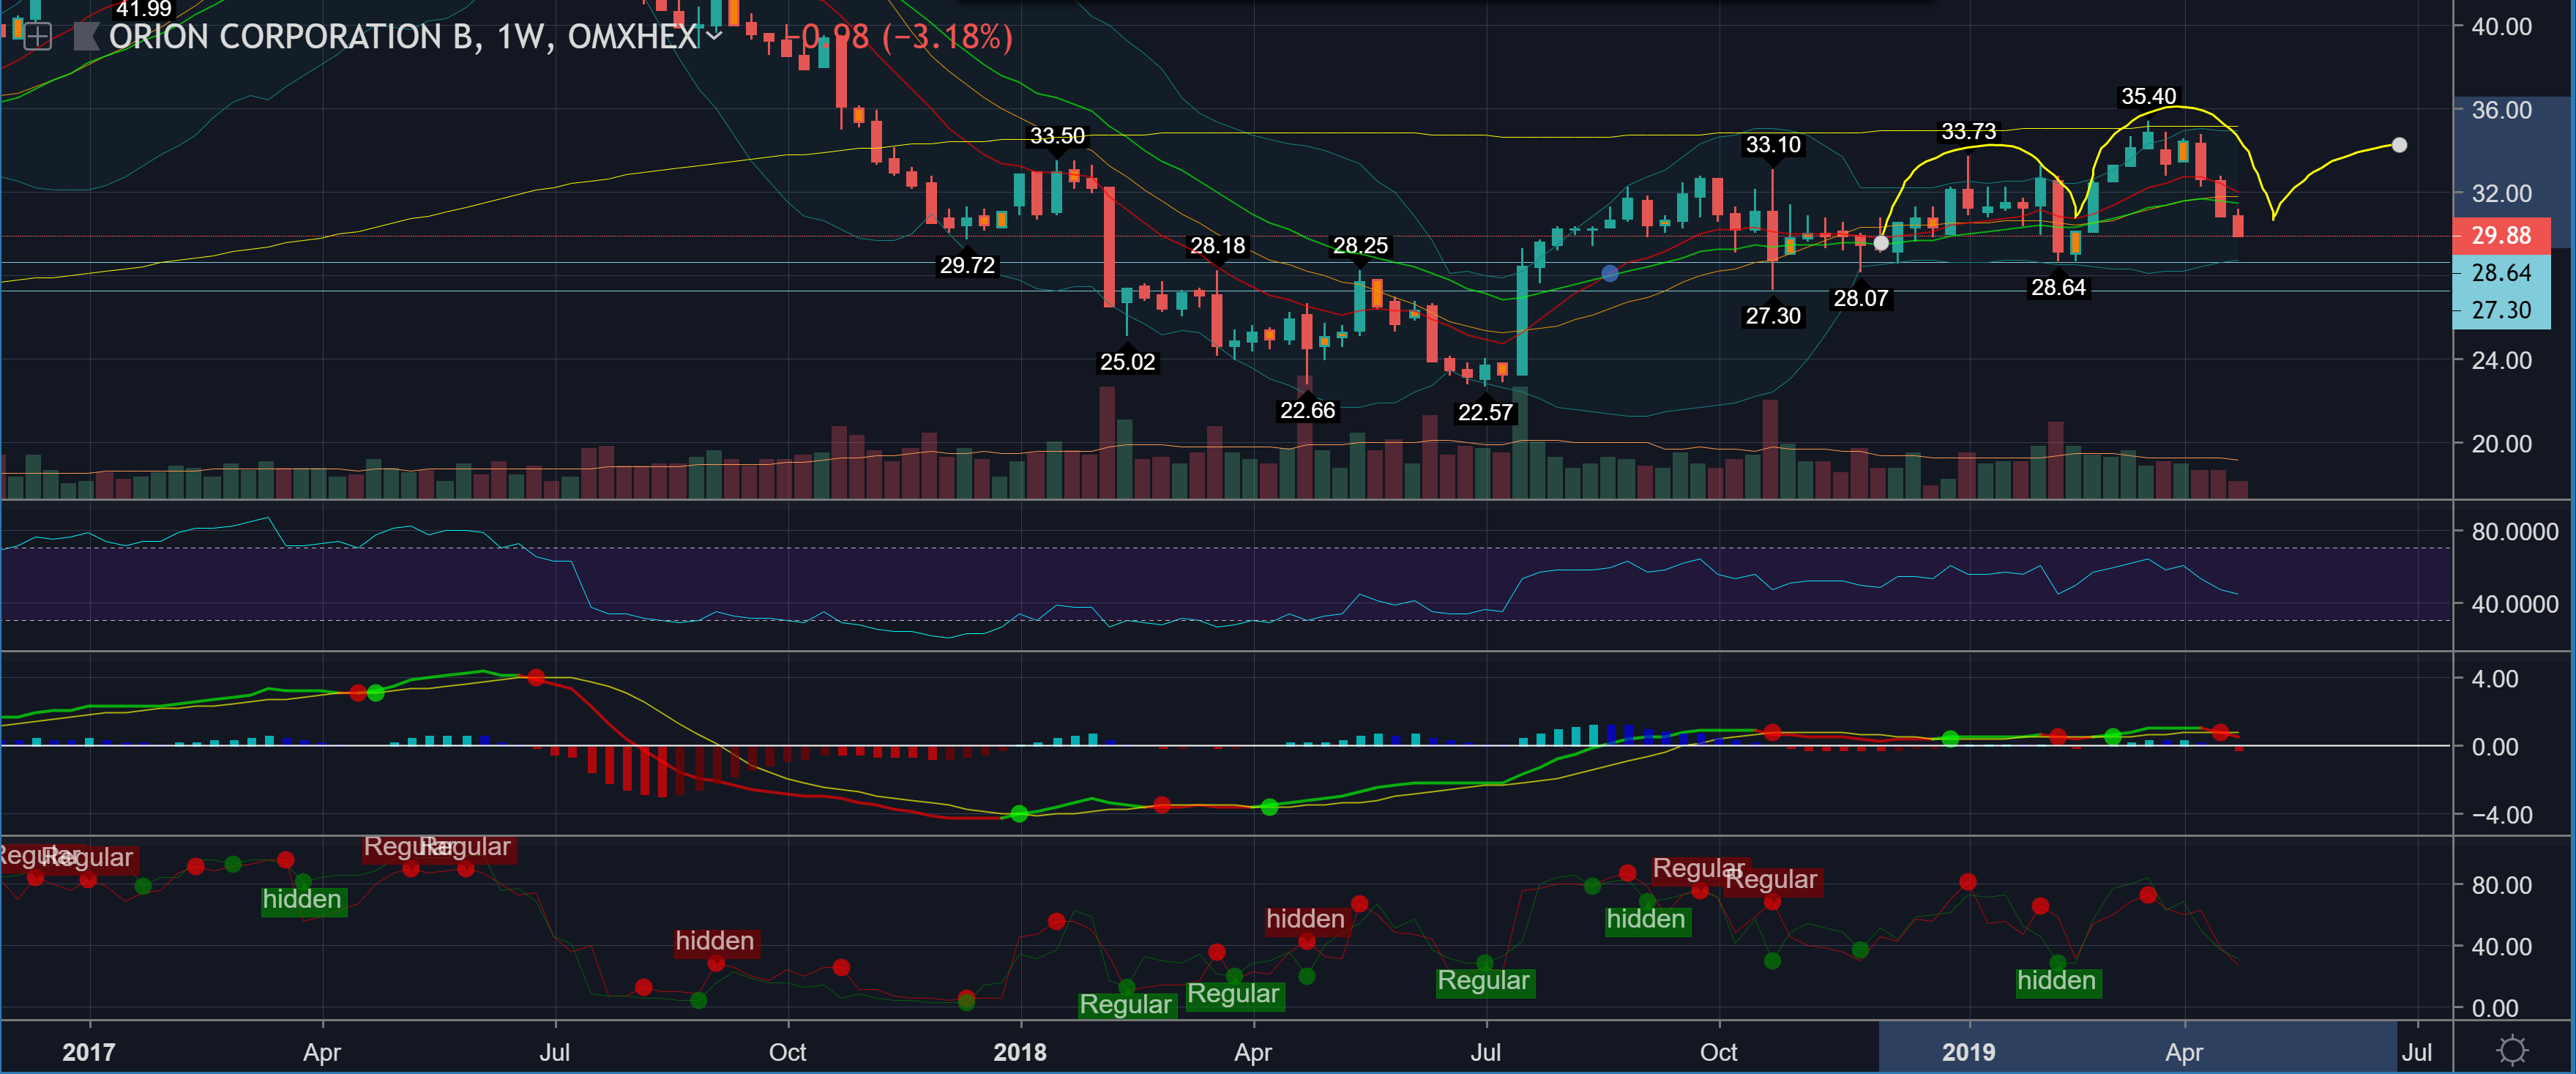
Now, only the weekly support level of 28.64 and the monthly level of 27.30 remain.
An H&S (Head and Shoulders) pattern is forming on a weekly basis, which indicates a change in direction.
“Hold your horses”
According to Orion’s press release, the compound developed jointly by Orion and Bayer received marketing authorization under the FDA’s expedited review procedure. The procedure is intended for drugs that may significantly improve the safety or effectiveness of treating serious diseases.
Orion doesn’t seem to be a forum favorite; it’s probably more of a trusted workhorse for the old guard, doing its job year after year, no matter the weather.
Some strange déjà vu made me wonder if it was time to return to Orion: I sold my long Orion positions in January, and now, after a quick look at their acquisition prices and Orion’s prospects in light of today’s knowledge, it was easy to make a decision. No Orion line will be added to my spreadsheet at these prices.
I came across this news from Yleisradio and thought I’d share it here, hoping it might spark some thoughts on Orion’s short-term potential.
“The two largest manufacturers of hydroxychloroquine are the French company Sanofi and the Finnish company Fermion Oy, located in Espoo and owned by the pharmaceutical company Orion.”
Hydroxychloroquine has preliminarily shown positive initial impressions in treating coronavirus symptoms. Could this be a potential short-term driver for Orion?
Too bad I had to sell my shares at 34, while I still could, because I needed safe cash.
Orion has a great portfolio of existing drugs that will carry them far and can be sold with excellent margins. However, about €15 of the share price is based on expectations for their research pipeline, and they spend about €100M/year on research. Large pharmaceutical giants (JNJ, MRK, PFE, etc.) spend $2-4B/year on research, which is 20-40 times more than Orion, and they can afford to hire the world’s absolute best researchers. For this reason, and despite their existing drugs, I would not invest in Orion, because the probability of them discovering any significant drug is simply non-existent.
Is that a necessity for Orion? This could be seen as a good dividend stock, if one only manages to pick up buys from dips. Darolutamide had a positive impact on the share price and in practice the stock has performed very well even because of this crisis.
I wonder if amateur guessers like me bought “because surely pharmaceutical companies must benefit from this.”
I myself sold half in December and the rest of the shares in February, and it went quite okay for an amateur, as the acquisition price was 29 euros / share.
Good points. IMO, 10 euros would be a fairer share of the growth. Orion has a super strong brand in the Finnish prescription drug and self-care markets, meaning that pretty high valuation multiples can be paid from a sure cash flow. In the current world situation, where the cash flows of numerous companies are decreasing significantly and companies are going bankrupt, Orion has its place in many investors’ portfolios.
In 2020, the equity ratio also appears to be 73%, and the net gearing ratio -15%. I think the market is pricing the stock quite fairly.
So, is drug development the only growth driver? Isn’t growing OTC sales also growth, as well as potential acquisitions, cooperation projects…
Perhaps you answered my question about the importance of drug development in Orion’s case, but the answer was a bit thin.
I was just questioning the view on the importance of drug development for Orion. That way, we could have a discussion and qualitatively compare the discussion points to our own decisions regarding Orion.
It seems clear that I don’t have a definitive stance with Orion, and I don’t think I’ll be getting back in for a while.
Edit: Indeed, I did get on board because of darolutamide, as I saw it potentially having a positive effect on the share price in the short term. A blind squirrel finds a nut in my case.
The term “hand medicine” (käsilääke) is a bit misleading (cf. eye medicine). You probably mean OTC (over-the-counter) or self-care medications. Sometimes, the term “hand-trade medicine” (käsikauppalääke) is also used.
Orion’s stock just keeps going strong in these difficult times. It’s been in my portfolio for a long time, and I even sold a bit of it to fund other purchases. I’m a bit doubtful about the price stability once the world settles down? I certainly wouldn’t buy at current prices, as the dividend isn’t that great either. Of course, it’s a very reliable product.