There are two interesting points here.
In order of priority:
- San Jose InP fab remains on track to enter production by year-end 2026
The further time goes on and everything is indicated to be progressing as it should, the better year 2027 and beyond we can expect.
- The company framed its 2027 guidance for 25-30% growth in Optical & IP Networks as directional
Well, look at that, the word “directional” has appeared here. BofA also believes the potential is higher, provided that point 1 goes well.
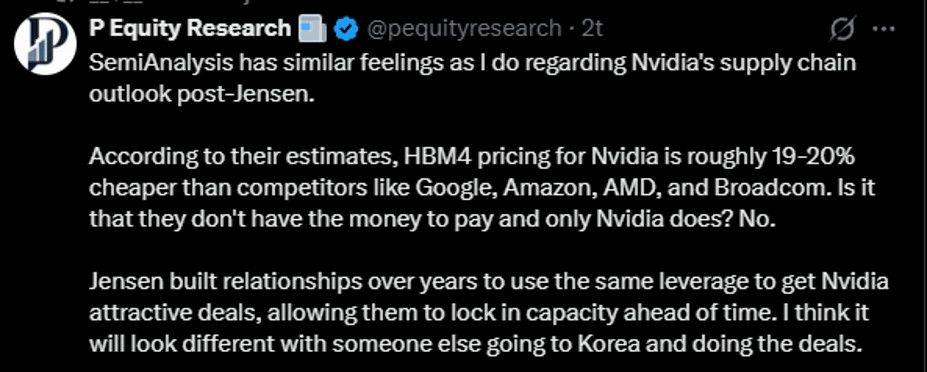
Then, Nvidia. I’m surprised by today’s news. However, the company set its future direction quite some time ago, so I’d be surprised if the AI-RAN narrative changed in any way. Surely this has been protected by contracts as well. One noteworthy thing, though, is that the new Nvidia might not necessarily be as good at negotiating contracts as the old Nvidia. Still, this hardly has any negative repercussions for Nokia, at least. In the end, results and money are what matter.
Edit: Here is most likely the reason why Nokia hasn’t made datacenter deals with Nvidia. Partners are essentially relegated to subcontractors—better prices can be found elsewhere.
Edit: Fixed a few typos