I just spotted that a boat company called Nimbus is listing in our neighboring country, and it seems to own the domestic brands Bella and Flipper. You could subscribe through Nordnet; I don’t know anything about boating myself, but could this be a growing business?  There’s a share sale by a private equity firm plus new shares available, if I understood correctly, with a valuation of roughly €100M.
7 Likes
The following does not contain any terribly deep analysis, and I haven’t really looked at the papers at all.
Nimbus’s brands are definitely in good shape; they are very popular in the Nordic countries, and all of them are quality boats. In Finland, of course, harbors are full of Buster and Yamarin boats, but Nimbus’s brands primarily seem to sell somewhat (much) larger boats than those ~5m boats, which is probably the most popular and common size and price range for the average Finnish motor boater. (I have no information on the boating culture of other Nordic countries; this is based on my observations on the Southwest Finnish coast). Bella, Falcon, and Flipper might offer slightly smaller sizes, but there are also luxury boats available.
The COVID summer of 2020 was likely a good year for boat dealers, even though many fairs and exhibitions were canceled. 2021 is unlikely to change in either respect, and it’s clear that consumers have more money and interest in these things as travel, etc., has decreased.
However, a few things should be considered here. For example, new car sales are struggling, but used car sales are booming. The trend in consumption behavior and COVID restrictions certainly support boating as a hobby, but is a new boat costing tens (or hundreds) of thousands of euros still a slightly different class of consumption decision than Tikkurila paints and Harvia heaters, or even that “already somewhat depreciated used car”? And overall, the entire boat business—production, storage, transport, sales, etc.—is much heavier than basic retail. Everyone can, of course, consider for themselves whether they are a buyer of a new boat or a new car, or if they are looking for something nice and relatively low-mileage on Nettivene or Nettoauto.
The timing for the listing project is certainly opportune. I am definitely interested in examining this more closely.
10 Likes
Here are my thoughts on the new offering, and the following should not be construed as an investment recommendation. I hope we can get more discussion on the offering:
Nimbus Group Ab: (Nimbus Group)
General:
The last time there was something available on the Swedish listing market more broadly for Finns, at least Nordnet and especially Thunderful went quite hot. Thunderful shares were raffled off, and the lucky individuals in the retail offering each received only about €250 worth of shares.
This company is not in as “hot” a sector as Thunderful, but IMO the market is even hotter than a couple of months ago → offerings of increasingly worse companies are going through on increasingly better terms for existing owners. (The previous comment does not directly apply to this company but to offerings and market sentiment in general)
I mainly went through the Finnish summary of the offering. The problem is that there is no prospectus in English, only in Swedish, so I haven’t gone through everything very carefully, and there may be errors in my reasoning.
In a nutshell, the company offers “a wide range of high-quality leisure motorboats under different brands, each with its own clear target group.”
I consider fine motorboats to be luxury products to some extent, so it’s hard for me to see this industry ever exploding into very strong growth with the current growth in living standards in Europe.
Reasons for listing (copied verbatim):
“The Company’s board, management, and principal owner believe that the IPO is a logical and important step in the development of the Nimbus Group. The listing is expected to strengthen the Nimbus Group in relation to consumers, dealers, suppliers, and other partners. In addition to a broader shareholder base, the listing of the company’s shares provides access to Swedish and international capital markets. The purpose of the IPO is to strengthen the Nimbus Group’s growth opportunities both organically and through acquisitions.”
My conclusion is that the proceeds from the listing would presumably go towards acquisitions. Nimbus has made acquisitions before, e.g., in 2018 it acquired Bella Boats. Nimbus Boats SWE acquires Finnish boat manufacturer Bella Veneet OY. I have no information on the success of the integration of previous acquisitions.
Brands:

Apparently well-known and established brands.
Numbers:
- Pre-money: approx. €80 million, with an additional approx. €18 million from the offering.
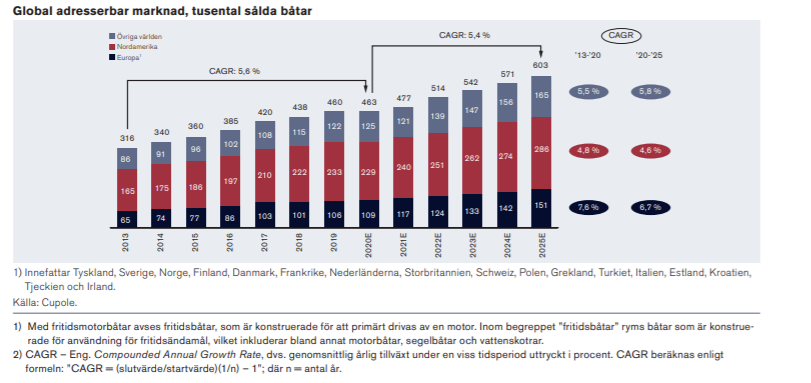
- Global target markets have grown at a rate of 5.6 percent (CAGR) in 2013–2020E, and are expected to grow at a rate of 5.4 percent (CAGR) in 2020–2025.
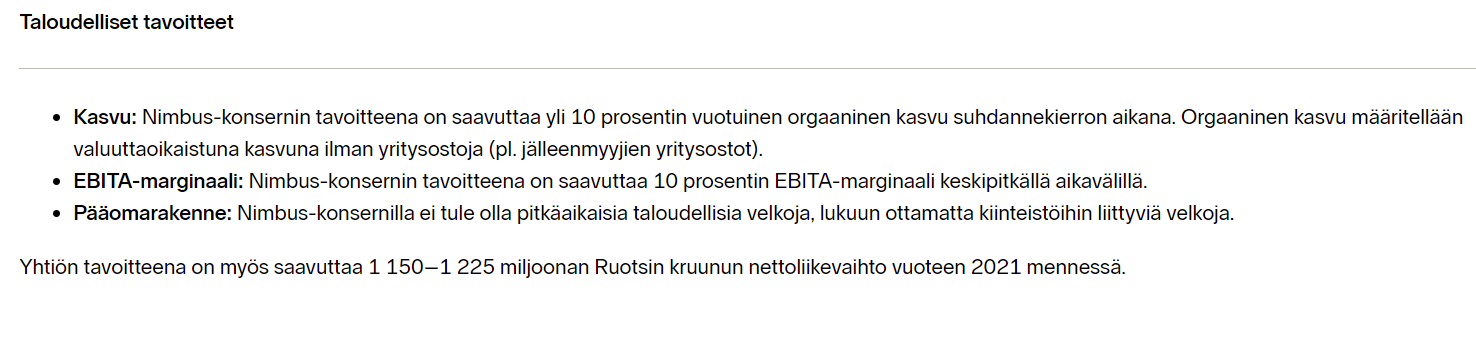
The financial targets for growth are much higher than market growth, so it’s a bit unclear to me how such strong organic growth, significantly exceeding the market, can be achieved. It’s not incredibly cheap relative to its targets, even if it reaches them. With the current market value and assuming the company reaches its 2021 targets (I don’t think the medium term is this year yet, but still), the valuation would be roughly P/S - 0.85 and P/EBITA - 8.5 (post-money). If 10% annual growth materializes, the valuation cannot be considered particularly demanding, and a fine and profitable growth story for owners can also be drawn from this, but in my opinion, the most probable organic growth is not 10%, and I certainly wouldn’t count on it myself. In addition, the company is so small in absolute terms that, in my opinion, larger than normal safety margins should be used in the valuation.
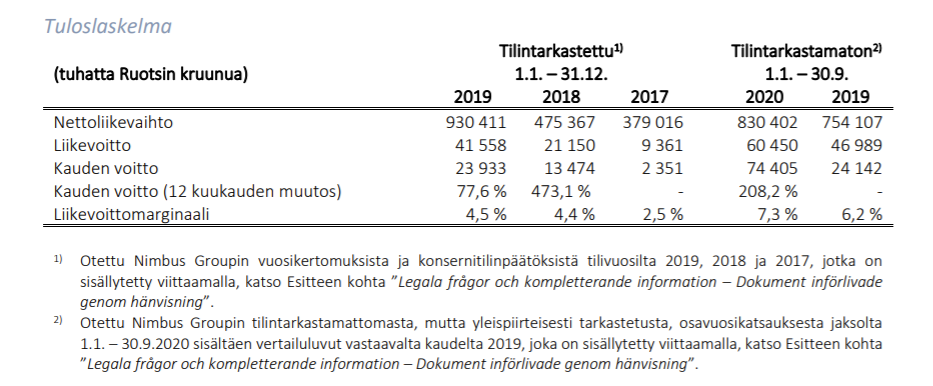
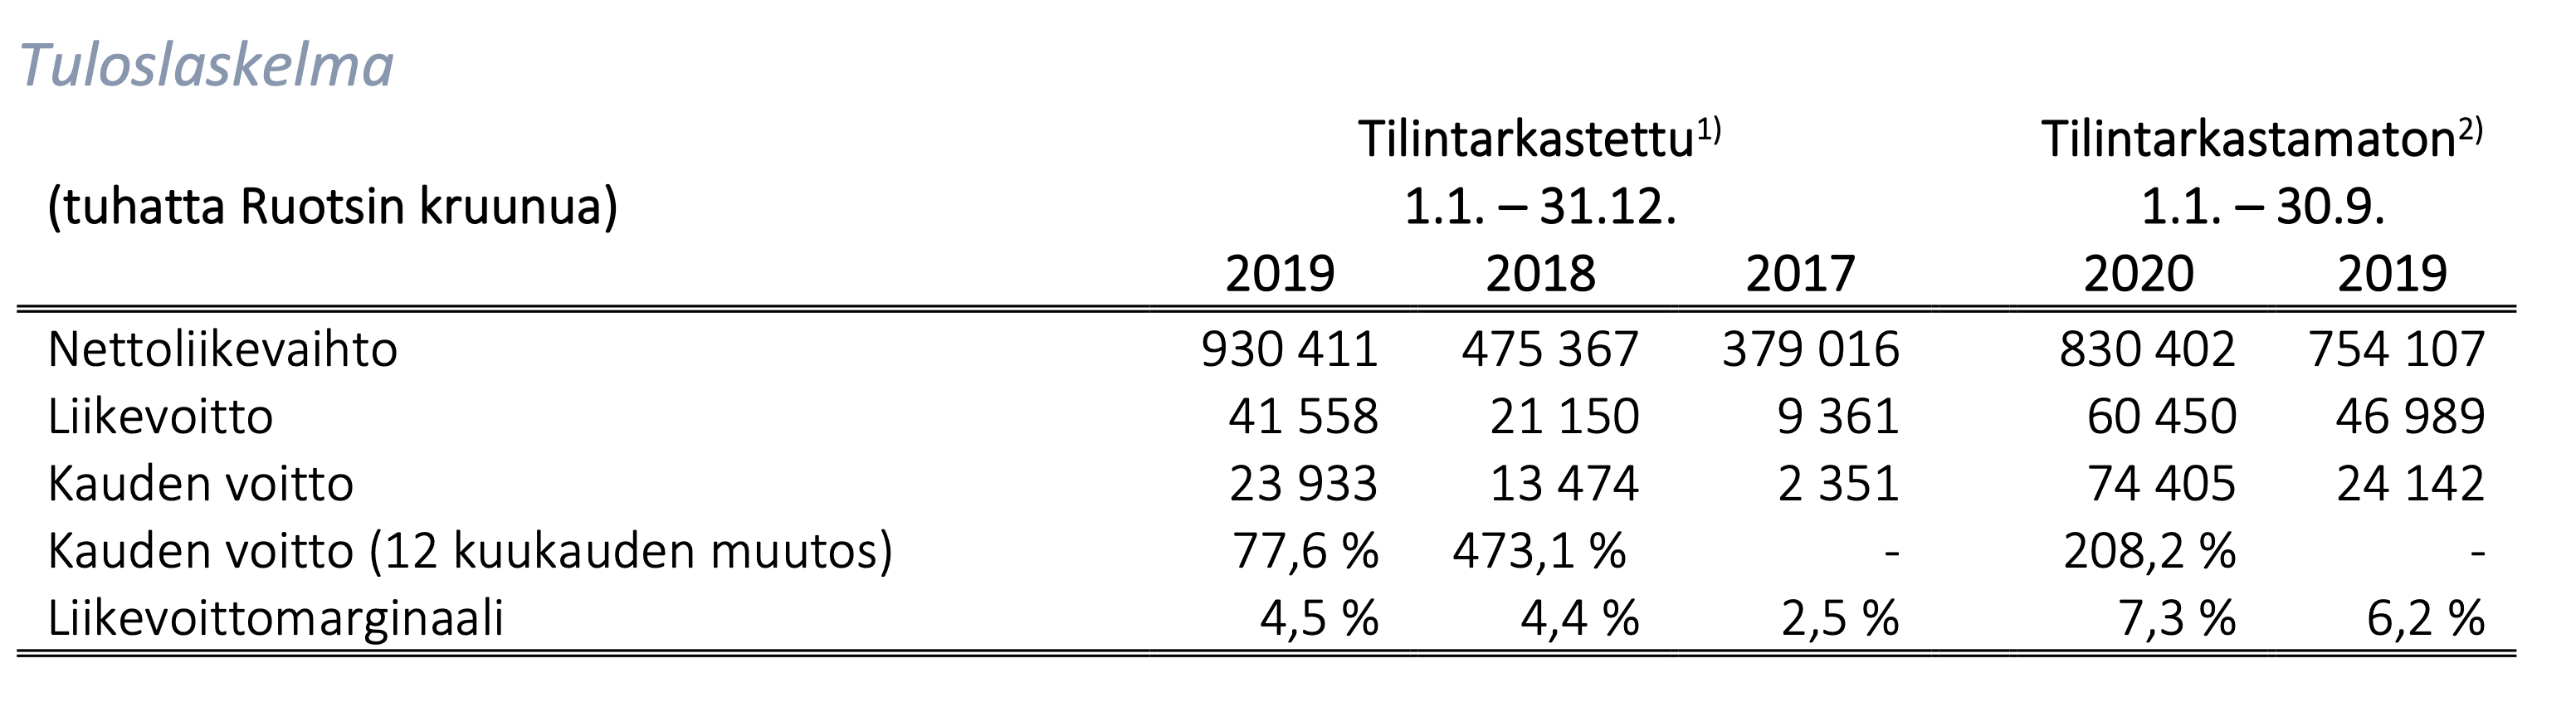
Generally, based on the numbers, it seems that the company has received an additional boost to its business from the pandemic, as people have had more leisure time. In addition, the revenue and operating profit jump in 2018-2019 must reflect the previously mentioned acquisitions. Q4 apparently generally has a loss on the operating profit line; at least in 2019 this was the case, because Q1-Q3 2019 operating profit was greater than the operating profit for the whole of 2019. If one were to extrapolate 2020 operating profit based on 2019 actuals, it could be 41.56/46.99*60.45 = 53.46 M SEK. In this case, the 2020 post-money P/operating profit (note: not P/E) would be around 18x.
In addition, there are 2 other scenarios for Q4 2020, but their probability is quite small in my opinion, assuming that Q1 and especially Q4 would be very poor for boat sales.
- Q4 operating profit would be 0, in which case the 2020 post-money P/operating profit would be around 16x
- Q4 operating profit would be the same as the average for Q1-Q3, in which case the 2020 post-money P/operating profit would be around 12x
With pre-money valuation, the P/operating profit multiples for the previous scenarios would be 15x, 13x, and 10x in the same order.
Especially after the offering, with a relatively strong balance sheet, it would also be reasonable to use EV-based figures.
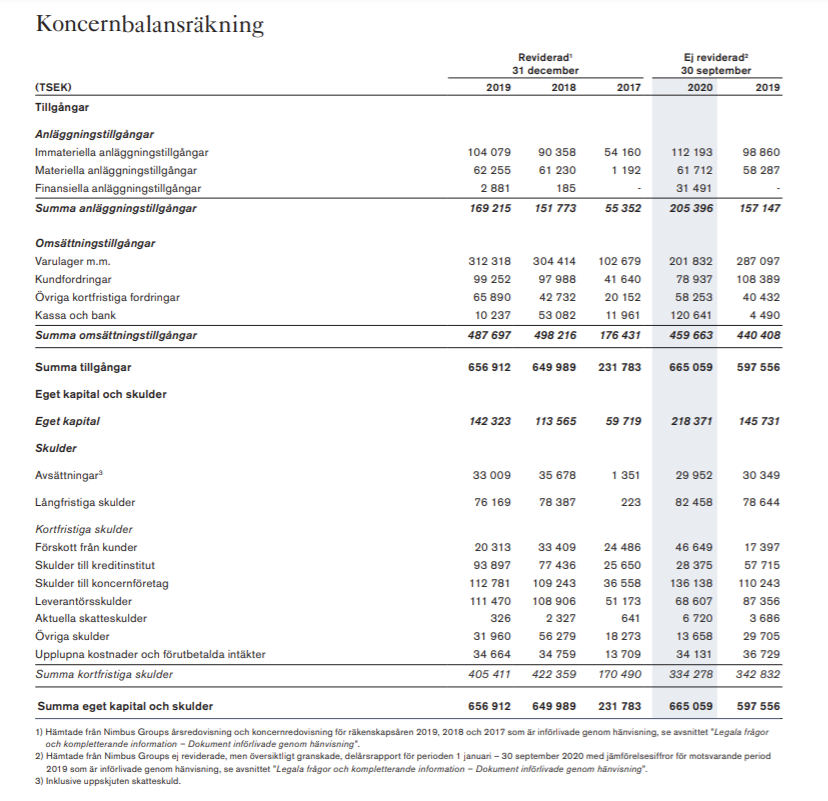
Someone with financial Swedish skills can better examine the balance sheet, but there’s no bomb there at a quick glance:
Composition of the offering:
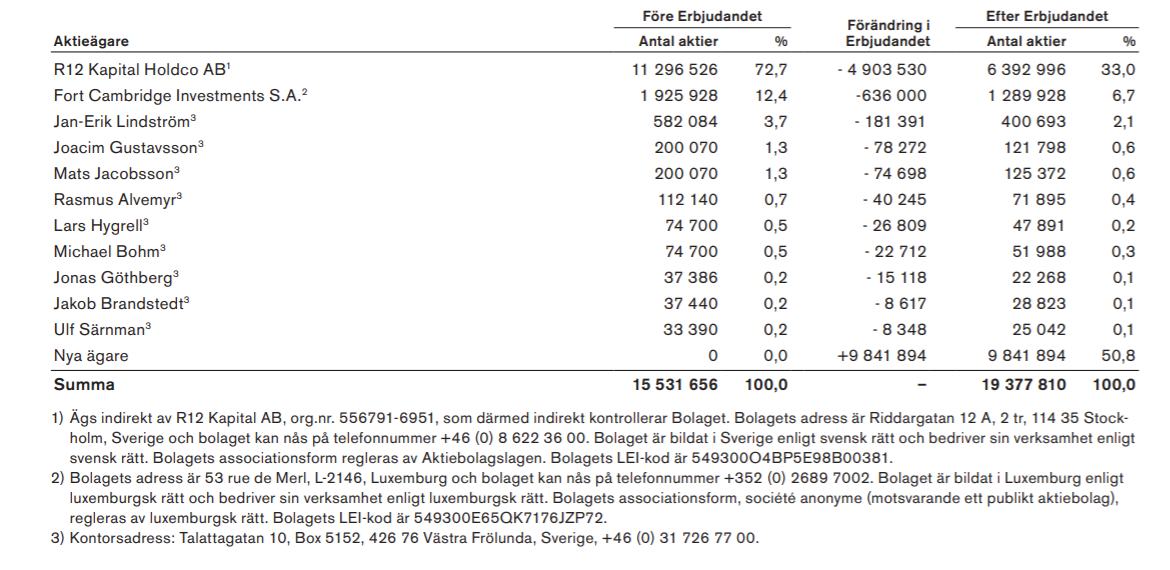
Both a new issue and a sale by existing owners. The price is apparently such that an exit already partially attracts existing owners. Share sales as part of an offering never give me the best impression, but in this case, the main owners will still retain quite a lot of ownership.
Overall, it seems like an interesting offering, and the pricing is by no means cheap in my opinion, but at a level where I believe there will be sufficient demand without a market collapse (compare Case Bilot in spring 2020). However, I find more attractive targets for long-term investment in the Helsinki stock exchange, not to mention Stockholm. I will presumably still subscribe for something and expect “quick profits.”
45 Likes
Nimbuks’ IPO price doesn’t seem like a rip-off, the IPO market is hot anyway, and the corona situation benefits the recreational boat market. In addition, people can afford expensive boats thanks to low interest rates, and rich boat buyers haven’t really gotten much poorer during the corona epidemic anyway. I was thinking of subscribing in hopes of quick profits.
4 Likes
How long can subscriptions be made, i.e., when can the offering be suspended at the earliest in an oversubscription situation?
1 Like
Have you found any analysis of this IPO online? Boat sales will probably grow moderately. How does the P/E compare to competitors?
My own quick calculations. Competitors’ figures are taken from investing.com and are approximate, so there may be some random figures mixed in.
Nimbus:
Pre-money valuation 800MSEK
2019 Revenue 930MSEK
TTM Revenue 1006MSEK
TTM P/S 0.8
2019 Profit 42MSEK
TTM Profit 55MSEK
EBIT-% 5.5
2019 Net Profit 24MSEK
TTM Net Profit 74MSEK (incl. tax refunds 29MSEK)
TTM P/E 10.8
TTM P/E (excl. tax refunds) 18
TTM P/E (if 1/3 of tax refunds are considered) 14.6
The last one is probably the most reasonable? That is, if too much tax has been paid previously, the overpaid taxes are balanced over a few years.
Competitors:
Brunswick
Does other things as well: boat segment Rev 1334MUSD
Groupe Beneteau
Does other things as well: boat segment Rev 1280MUSD
Azimut Benetti
Private: Rev 1008MUSD
Ferretti
Private, was listing in autumn 2019, Rev 781MUSD
“Ferretti saw lowering of its indicative price range for shares from the initial target of €2.50 to €3.70 per share to only between €2.00 and €2.50. That said, it would have meant a market valuation of € 581 million instead of aimed €1.08 billion.”
Malibu Boats
Rev 684MUSD
Sales decreased 19->20 5%
P/S 2.25
P/E 22
In previous years, net profit margin ~5-10%
Mastercraft Boat Holdings
Rev 466 MUSD → 363MUSD (Jun30 19 ending → Jun30 20 ending)
Sales decreased 19->20 22%
Net income 21MUSD → -24MUSD
P/S 1.38
P/E N/A
In previous years, net profit margin ~5-12%
Marine Products
Rev 276MUSD
Sales decreased 19->20 5%
P/S 2.1
P/E 27.3
In previous years, net profit margin ~7-10%
Regal Marine Industries
Private: 223MUSD
HanseYachts
Rev 128MEUR
Sales decreased 19->20 16%
P/S 0.65
P/E N/A loss of 8% of sales, at zero for many years
In previous years, net profit margin ~(-2)-2%
Nimbus:
Net debt 106MSEK
Cash 121MSEK
Figures from the prospectus, so a bit more cash than net debt. Cash has swelled in 2020 as inventory decreased by 110MSEK 12/19->9/20.
Holdings:
Before issue → After issue
CEO 582k → 401k
CFO 112k → 72k
CMO 75k → 52k
CTO 200k → 125k
Design chief 200k → 122k
Looks like a reasonably priced offering to my eye.
According to the prospectus, CAGR growth has been 5.6% for 2013-2020 and 5.4% is expected for 2020-2025.
The subscription period is until February 7th. There is no other mention of oversubscription than that the main owner will buy additional shares in case of oversubscription.
13 Likes
Why can’t I find that Finnish brochure anywhere? I scrolled through the Swedish one and came to the conclusion that it looks quite interesting at first glance.
2 Likes
Interesting. I could participate. As a boater, my feeling is that Nimbuses are very high-quality boats, and the other boats belonging to the Group are also good. Nimbus boats have a classic, iconic design that will surely do well in the future.
No idea about their innovation capability.
The growth is a bit concerning.
2 Likes
In Finnish, there is only an abstract, which can be found after the Swedish abstract in the same PDF.
2 Likes
Well, that seems to be the case. Thank you very much!
I suspect that the proceeds from the offering will go towards improving the financial situation, and this was actually mentioned in the Finnish section as well.
Thus, the funds would not be going into developing the actual business operations. I think this is a bad thing.
Another thing that makes me wonder is what this company has that others don’t. Is there something superior in its operations compared to competitors? I’m not aware of anything like that myself. In my opinion, merely offering different brands is not enough for this company to be the “Kamux” of boats.
However, I don’t consider it impossible to participate in the offering in the hope of a quick profit.
T. Niittari
So where did you find that Finnish summary, as I can’t seem to spot it? I went through all the PDFs… 
https://www.nordnet.fi/fi/kampanjat/listautumisannit/nimbus/nimbus-listautumisanti
Summaries can be found on both.
https://www.nordnet.fi/fi/kampanjat/listautumisannit/nimbus
Around the middle, “Summary of the prospectus (FI)”. The same PDF contains summaries in Swedish, Norwegian, and Finnish, meaning the Finnish summary starts on page 15.
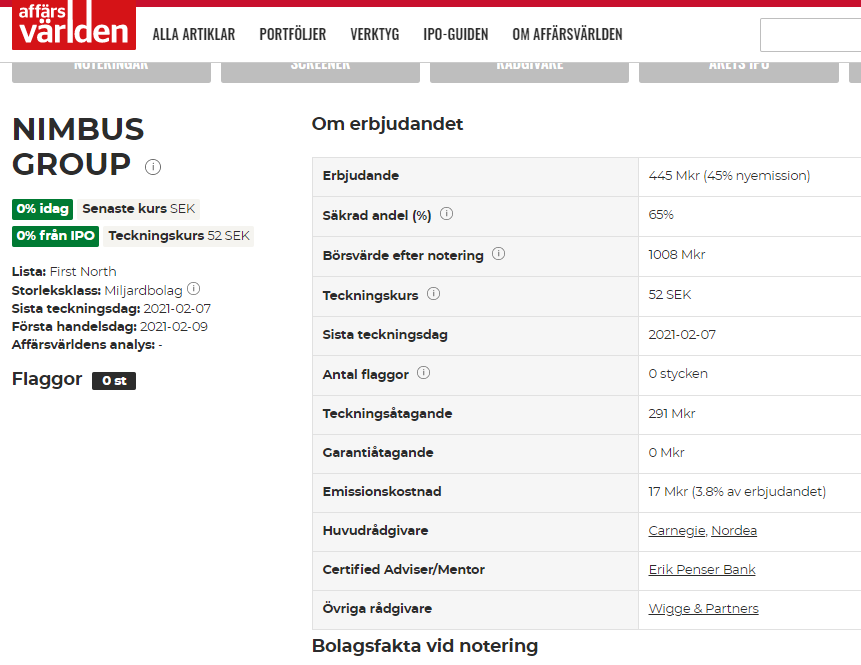
445MKr in total commitments, 291MKr given. So, there is just over 15M€ left to distribute, plus x number of shares in oversubscription. The offering is so small that it will probably be oversubscribed many times over.
Nimbus boats are certainly good. As for the boat market, I wouldn’t be so sure.
Firstly, a boat’s durability is in a completely different league than a car’s. A car rusts in 15 years, and technology develops in just 5 years. A boat, on the other hand, can’t really “rust,” so its lifespan, in terms of materials, is decades. Car manufacturers spend hundreds of millions annually on product development. Boatyards struggle with, at most, millions. Thus, technical development is also quite slow. As a result, the shores are full of perfectly usable boats, and someone has even said that a new boat’s worst competitor is an old boat.
Another issue is climate change. A car can even be essential for living and working. A boat, however, rarely is. New cars are required to have a consumption of 0-4 liters per 100 km. A larger planing cruiser easily consumes almost a liter per kilometer. Of course, in light of the kilometers driven, it won’t destroy the world, but it’s still not terribly acceptable or appealing.
Batteries and charging infrastructure cause headaches for electric cars. If you want to get a planing cruiser to run on electricity, the challenges are manifold. Weight is poison for a planing boat. The power needed for smooth travel is many times greater compared to movement on wheels. This, of course, explains the difference in consumption between a boat and a car. Of course, few people want to drive a pleasure boat 1000 kilometers on one tank, but a hundred kilometers nevertheless.
Waiting for hydrogen technology to become cheaper…
3 Likes
From the offer details:
“The purpose of the IPO is to strengthen the Nimbus Group’s growth opportunities both organically and through acquisitions.”
"This ratio is a bit “concerning”:
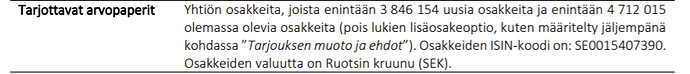
“The IPO consists of a maximum of 8,558,169 shares, of which 3,846,154 are new shares of the Company. The remaining 4,712,015 shares are existing shares offered by the Company’s shareholders.”
If the purpose is to grow and acquire companies, why is the majority of the offer shares a cash-out for current owners?
5 Likes
It’s pretty standard for old main owners to exit at the same time. Especially when the largest owner is apparently a private equity firm with a 33% stake. With this information, I plan to subscribe. I probably won’t hold it for long, so the ultimate reasons for listing don’t interest me that much.
Oversubscribed. We’ll get crumbs like from Bilot a year ago. But you can get a small quick profit, if you want…
This is what I assume…