That naturally depends on which metrics you use to look at the matter. In my opinion, however, your characterization is quite unfair to the company.
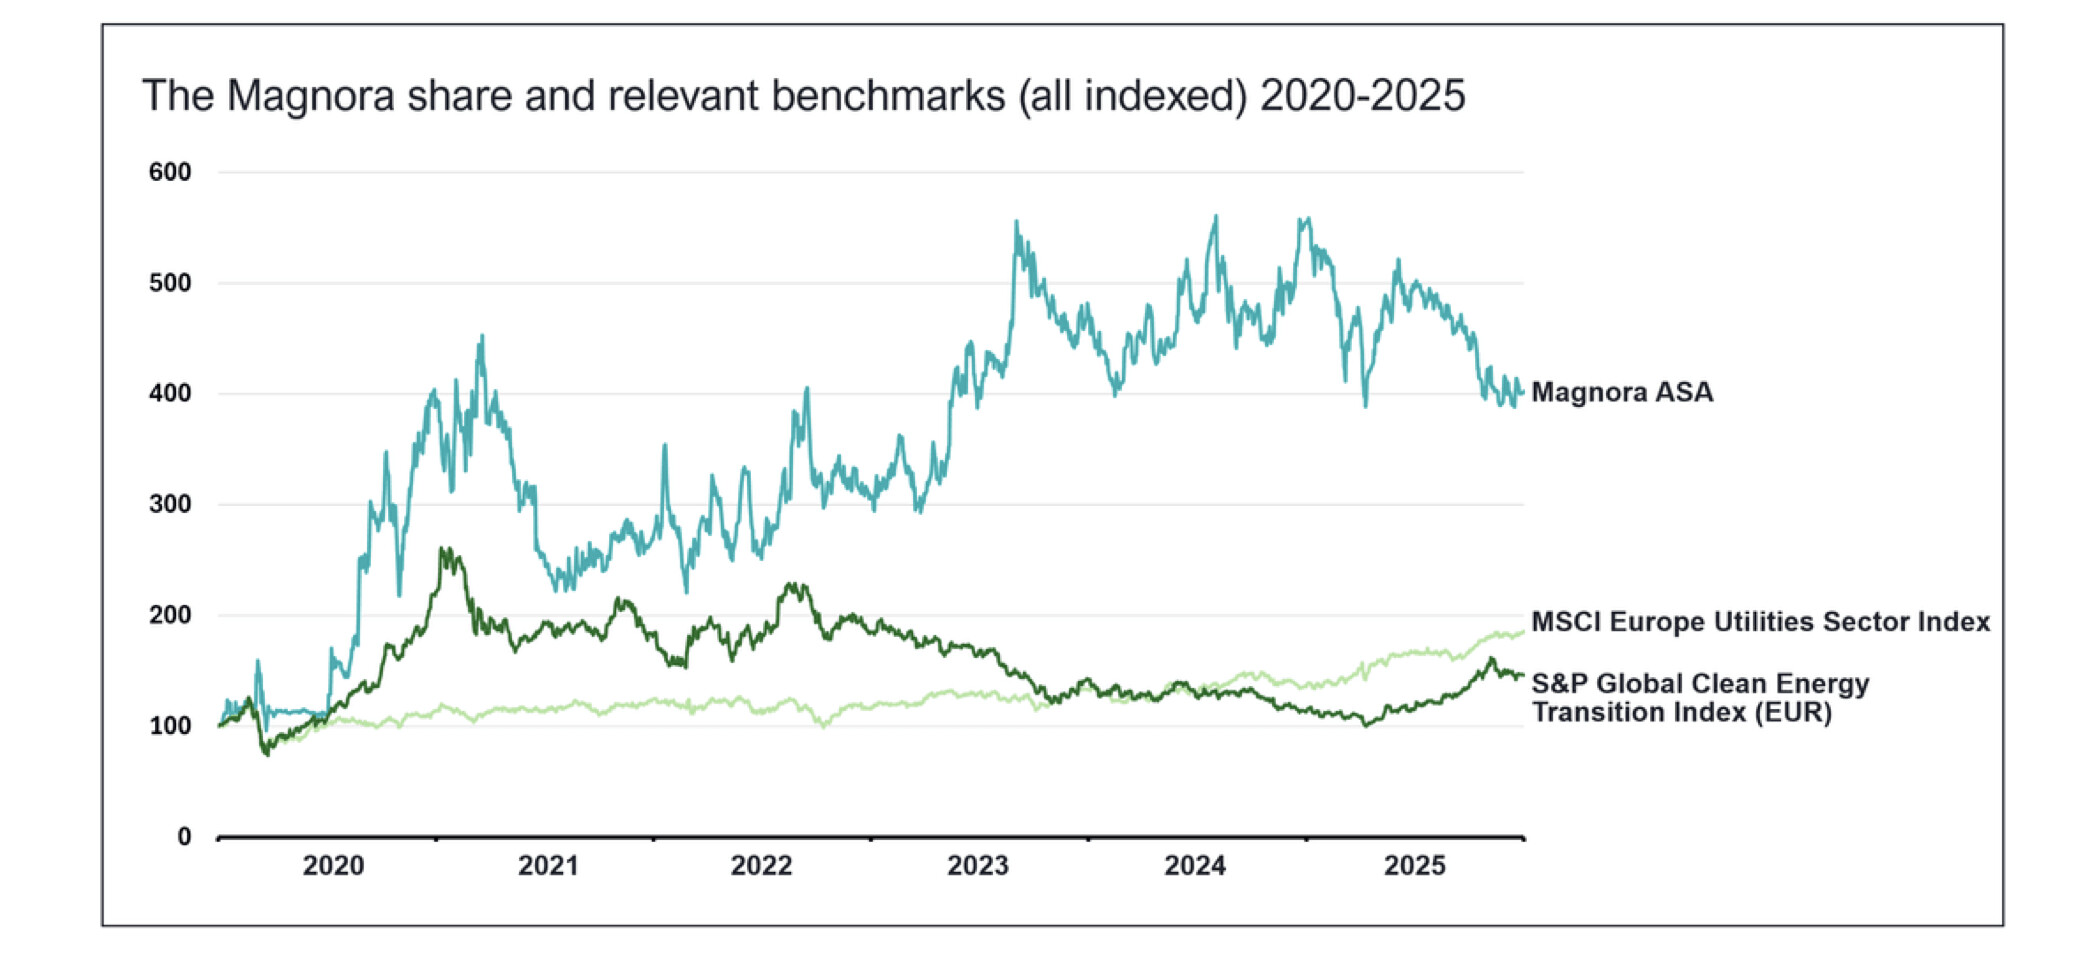
In recent years, they have successfully managed investments and exits in Evolar and Helios, for example, both of which were sold at excellent prices, while less interesting assets have also been divested quite successfully without dumping massive amounts of capital into bad projects. For instance, offshore wind power, Hermana, green hydrogen, and ammonia are areas where a worse management team could have sunk a lot more good money.
The data center business has its own independent market value determined daily by the “efficient market” stock exchange, which has literally been whipped up from nothing in a few years. You may disapprove of the way this value has been created, but it exists beyond a shadow of a doubt. Had the data center business not been started, Magnora’s share price would currently be significantly lower than it is now.
Currently, the largest unsold assets are in South Africa, where the electricity market reform has been delayed due to reasons beyond the company’s control. The South African Wholesale Electricity Market (SAWEM) was supposed to start operating in 2026, but now it looks like it will be 2027 or even 2028. This naturally and inevitably affects the willingness of Magnora’s customers to buy, as there is still so much uncertainty in the air regarding the returns that developers will get from their projects. There is, of course, a genuine risk that these projects will not sell at all in the near future, but it is hardly going to be due to a lack of management expertise, value-creation capability, or business acumen.