I would challenge this a bit because, to my eye, it looks like a lot of expectations are already baked into the current price. By what metrics or key figures do you consider Lemonade cheap?
5 Likes
I can’t provide a better analysis of the LMND valuation than Paperbag myself; here is a video from 2 months ago. There might even be some bumps along the way, but the fair value today is likely somewhere around $150-200, and I’m sure that will be reflected in the share price by the end of the year.
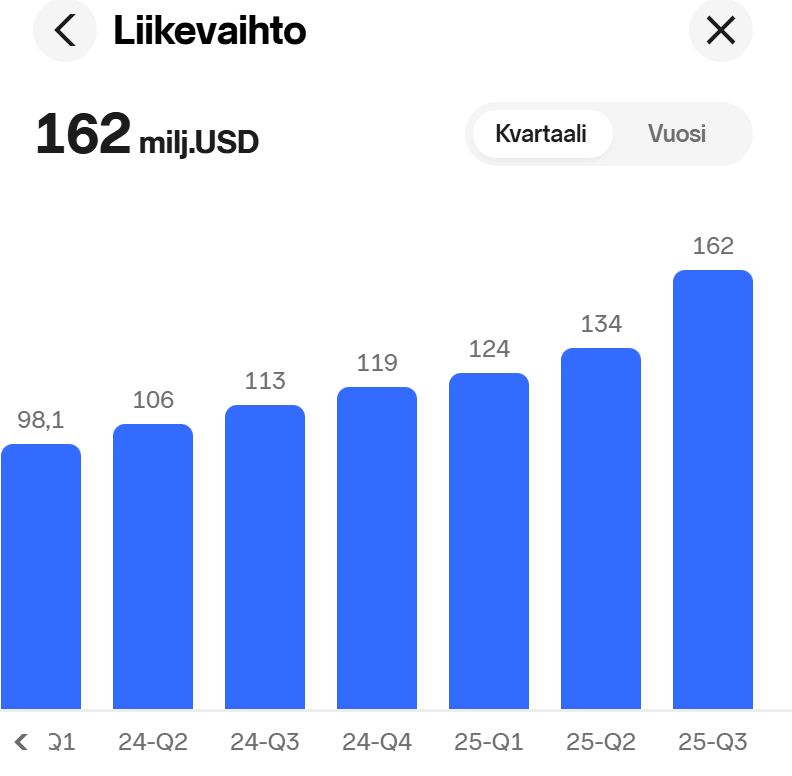
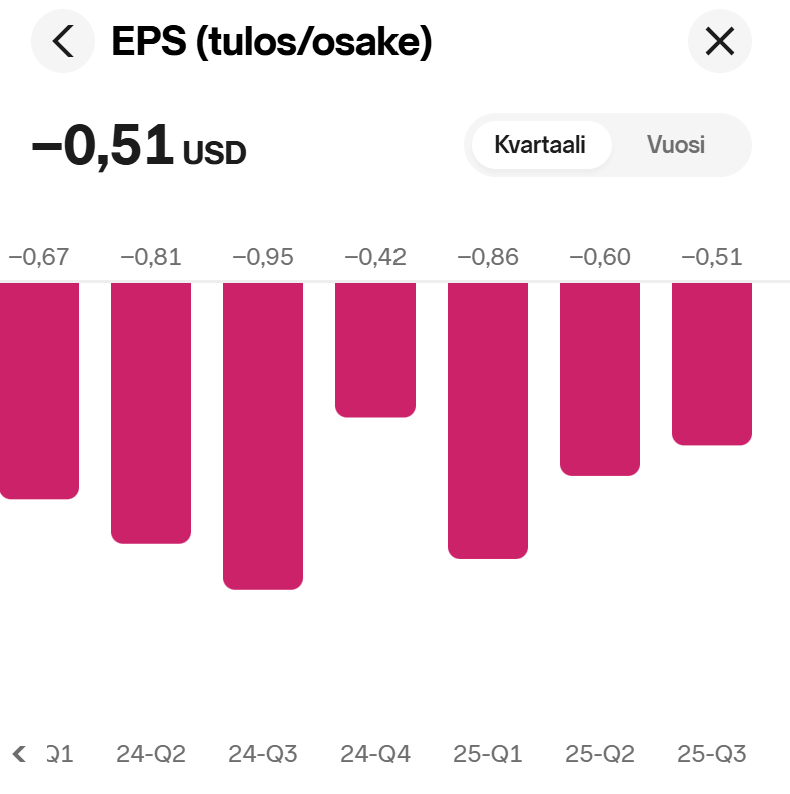
I’m doing the work for you now, but that guy (lemonade super bull) seems to be taking his estimates from his spreadsheet. Briefly, I suppose if you calculate that if it’s given a P/E 100 valuation in 2029, this stock would be worth $182 now. Of course, it’s worth noting that Lemonade hasn’t had a single positive quarter yet, and in Q3 25 revenue was $162 million and the result was -$37.5 million. The company’s market cap, by the way, is $6 billion, so as I see it, there are a lot of expectations loaded into the stock price.

5 Likes
Valuating a super-grower is challenging. Sure, if the current growth started to stall, one could question that pricing. But the situation has been the opposite for the past year. If things don’t turn profitable by the end of 2026, as LMND management has stated, it would definitely be a red flag.
Of course Lemonade is risky. Growing pains and such will surely occur, and these are followed closely in the LMND community as well. Competitors, such as Geico, have also hired people intended to close the gap on LMND’s lead.
But the company is exceptional, the management is experienced, and they have experience in scaling startups. The timing has also been spot on, as they began developing an AI-driven insurance company more than 5 years before AI became a hot topic.
It is easy for insurance companies to grow revenue by selling cheaper than others if they don’t need to make a profit on insurance operations, which is currently the case with Lemonade. Personally, I wouldn’t talk about a “hyper-grower” here even though revenue has increased; to me, it looks like normal good growth for revenue of that size. When revenue is in the billion-dollar range, growth percentages will likely look different anyway. If I remember correctly, part of the revenue growth is also currently due to reducing the reinsurance share, which can’t be done indefinitely—isn’t that the case?
I understand the difficulty of valuing hyper-growth companies like Iren or Nebius, which quickly pivot their business from bitcoin mining → AI data centers and see revenue grow by many hundreds of percent per year.
If you want to think about how much expectation is priced into the stock right now, you can consider how much you would pay for a company with that amount of revenue and negative earnings at 0% growth?
Here is the revenue:
EPS development:
7 Likes
This has already been discussed in this thread, but the business is already profitable if growth investments are not taken into account. Reinsurance was reduced this year from 55% → 20%, and it will be reflected in the revenue (LV) gradually, becoming fully effective by next summer.
9 Likes
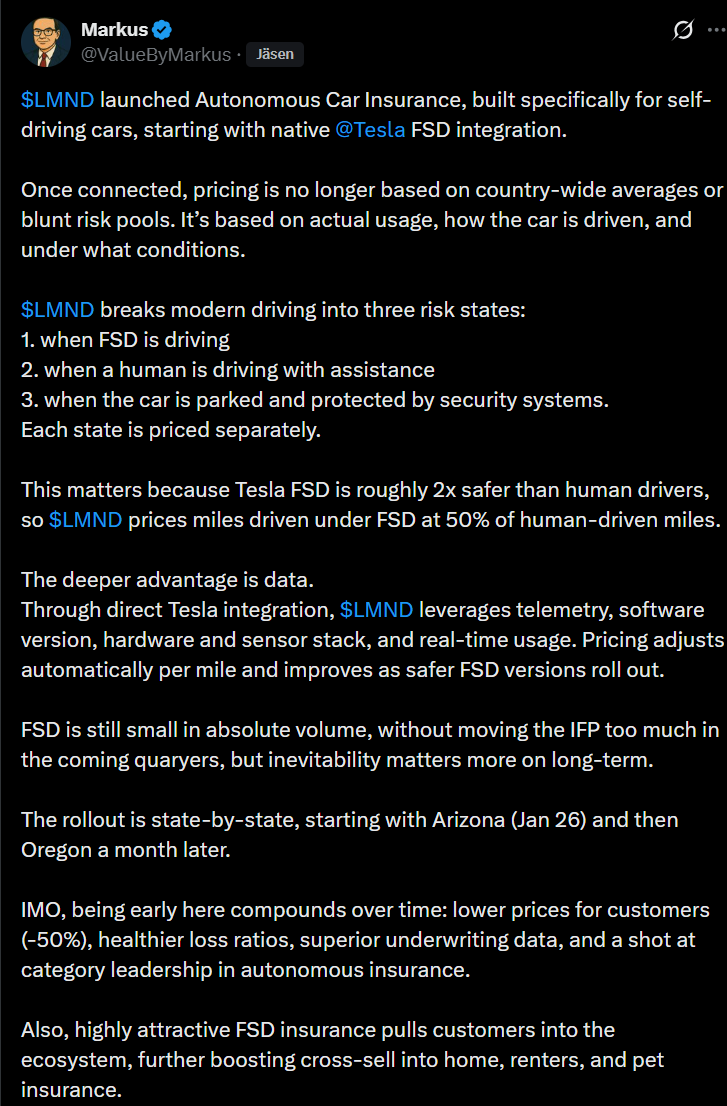
Here is Markus’s tweet about Lemonade launching autonomous car insurance for self-driving cars. 
IMO, being early here compounds over time: lower prices for customers (-50%), healthier loss ratios, superior underwriting data, and a shot at category leadership in autonomous insurance.
https://x.com/ValueByMarkus/status/2014094118188630384
In this tweet, Markus “quoted” his old tweet from October:
https://x.com/ValueByMarkus/status/1979261528189673770

2 Likes
A certain Elon Musk shares the same.
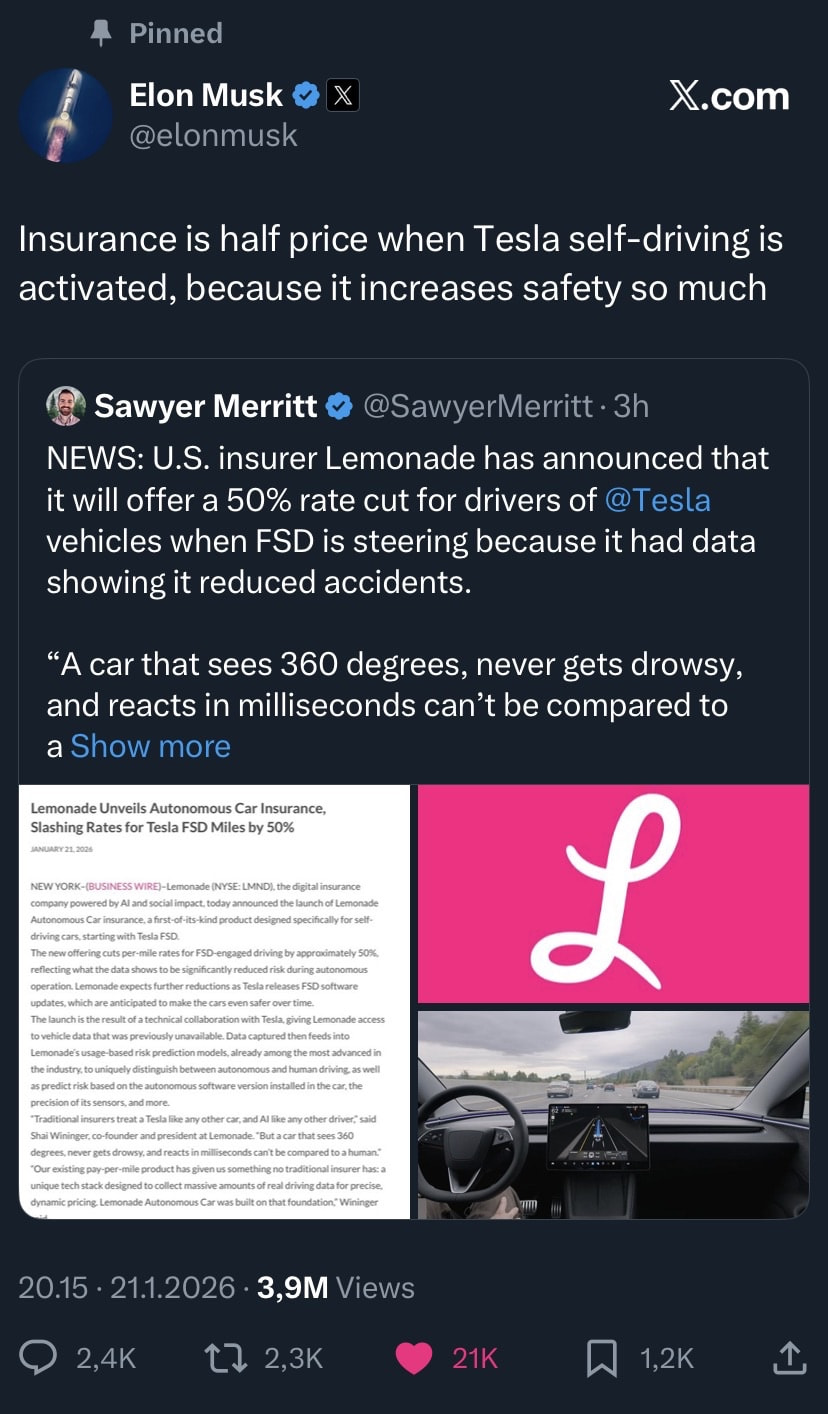
6 Likes
Adding the link to the original: https://x.com/elonmusk/status/2014039116854300810?s=46
I almost choked on my latte yesterday when I checked the market in the evening and the price was knocking on the door of a hundred. As soon as I saw the tweet this morning, I was sure $90 would be broken. The journey is only just beginning; it’s certain there will be plenty of volatility ahead. About 40 days until the Q4 results and 2026 guidance. A great year 2026 ahead!
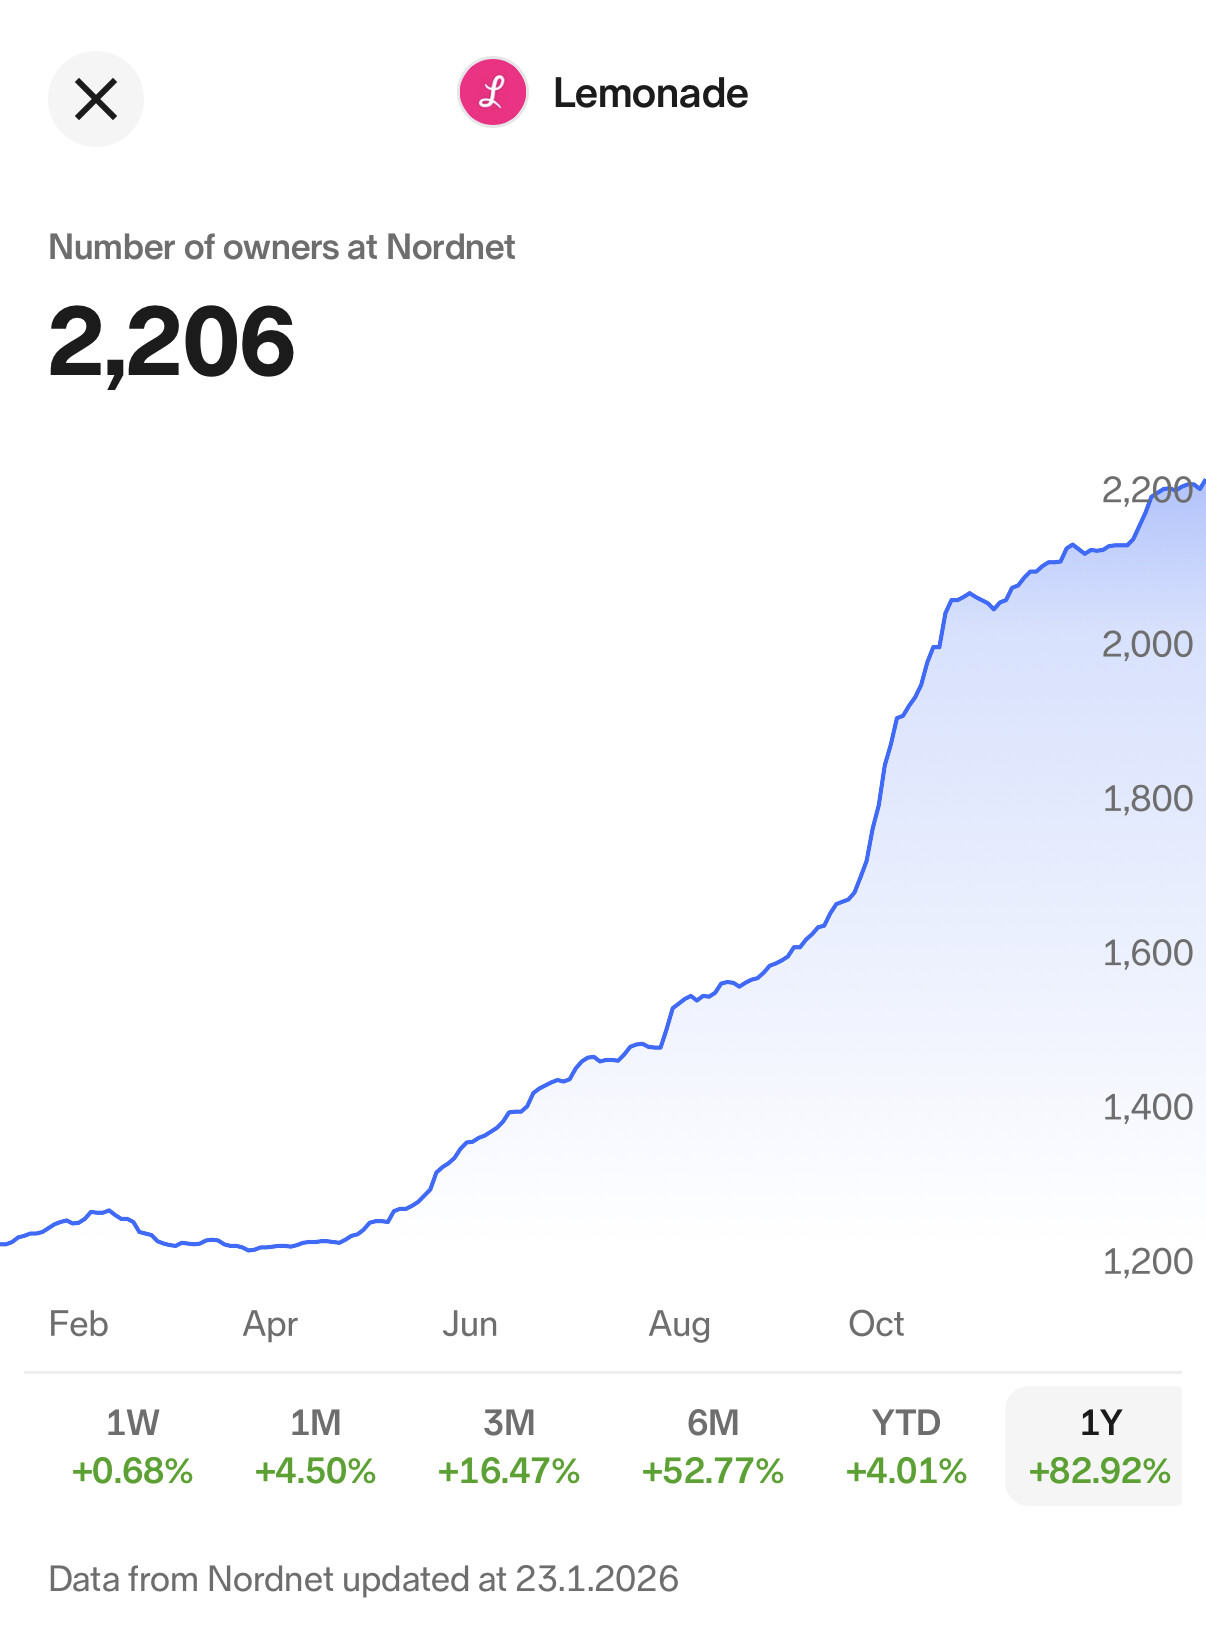
The number of investors on Nordnet is growing nicely, but for comparison, Faron has over 12k owners…
4 Likes
An interesting article in Arvopaperi about Lemonade and how the company is revolutionizing the traditional industry with its FSD insurance solution: Lemonaden yhteistyö Teslan kanssa ravistelee Sampoakin – Vakuutusalan disruptoija on ladattu täyteen sijoittajien toiveita | Arvopaperi
”Investors may be overoptimistic, but it cannot be denied that the company is shaking up the entire insurance industry. Traditional insurance companies risk falling behind in the competition unless they quickly adopt AI as a central part of their business.”
2 Likes
Sounds interesting. Unfortunately, it seems to be behind a paywall.
The stock price has corrected a bit, as it has slid down about 30% in a couple of weeks. Q4 and 2026 previews will start coming soon! Exciting times.
It’s hard to imagine that traditional insurance companies haven’t woken up to the arrival of AI. Of course, in larger companies, changes certainly happen more slowly, but they also surely have resources on a different level when they want to develop AI to suit their own business.
1 Like
If you want to check out the market’s best LMND analyst ahead of the earnings report, here it is:
The market has offered some buying opportunities recently. I just haven’t had any free chips to add more.
4 Likes
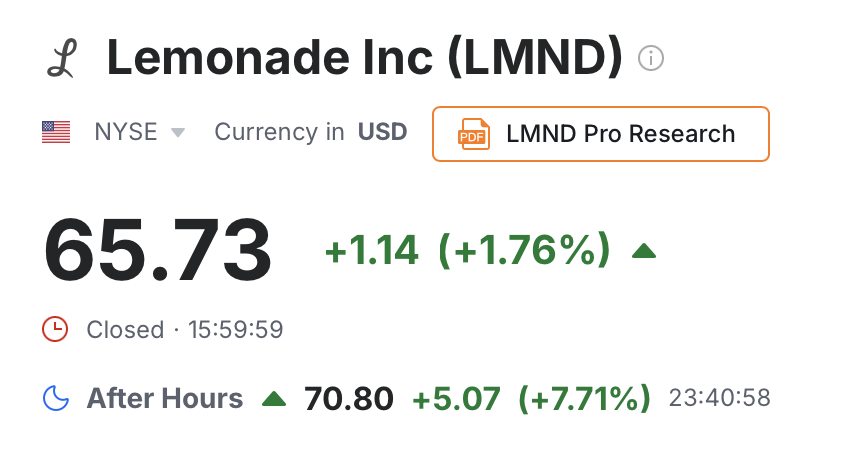
Well, looks like Lemonade is in a decent rise in after-hours. I wonder if someone has better info or just more robust speculation about the results being released later today  In any case, we are still far from the roughly $100 level spurred by the Tesla news, which was only about a month ago. Shareholders have an exciting day ahead today, as along with the results, we’ll also get the full-year 2026 guidance!
7 Likes
There it is. ”By any measure, the fourth quarter of 2025 was our strongest ever.”
5 Likes
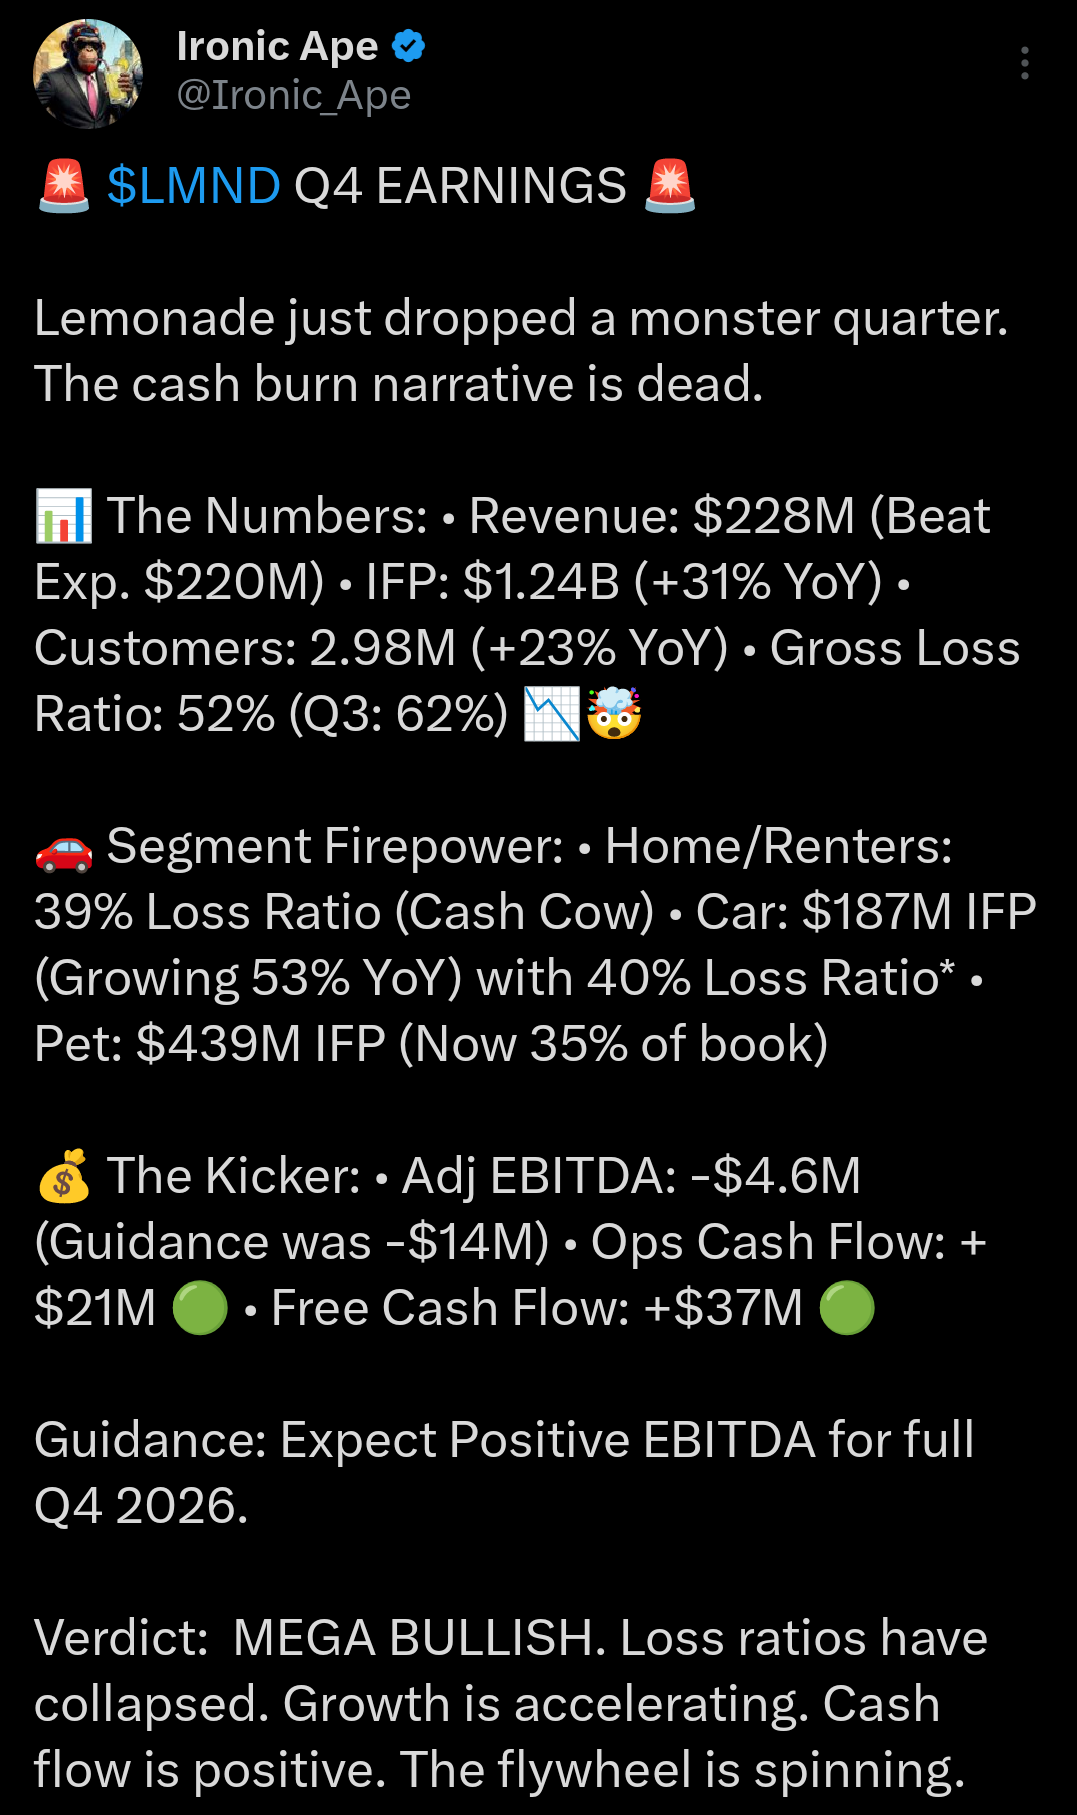
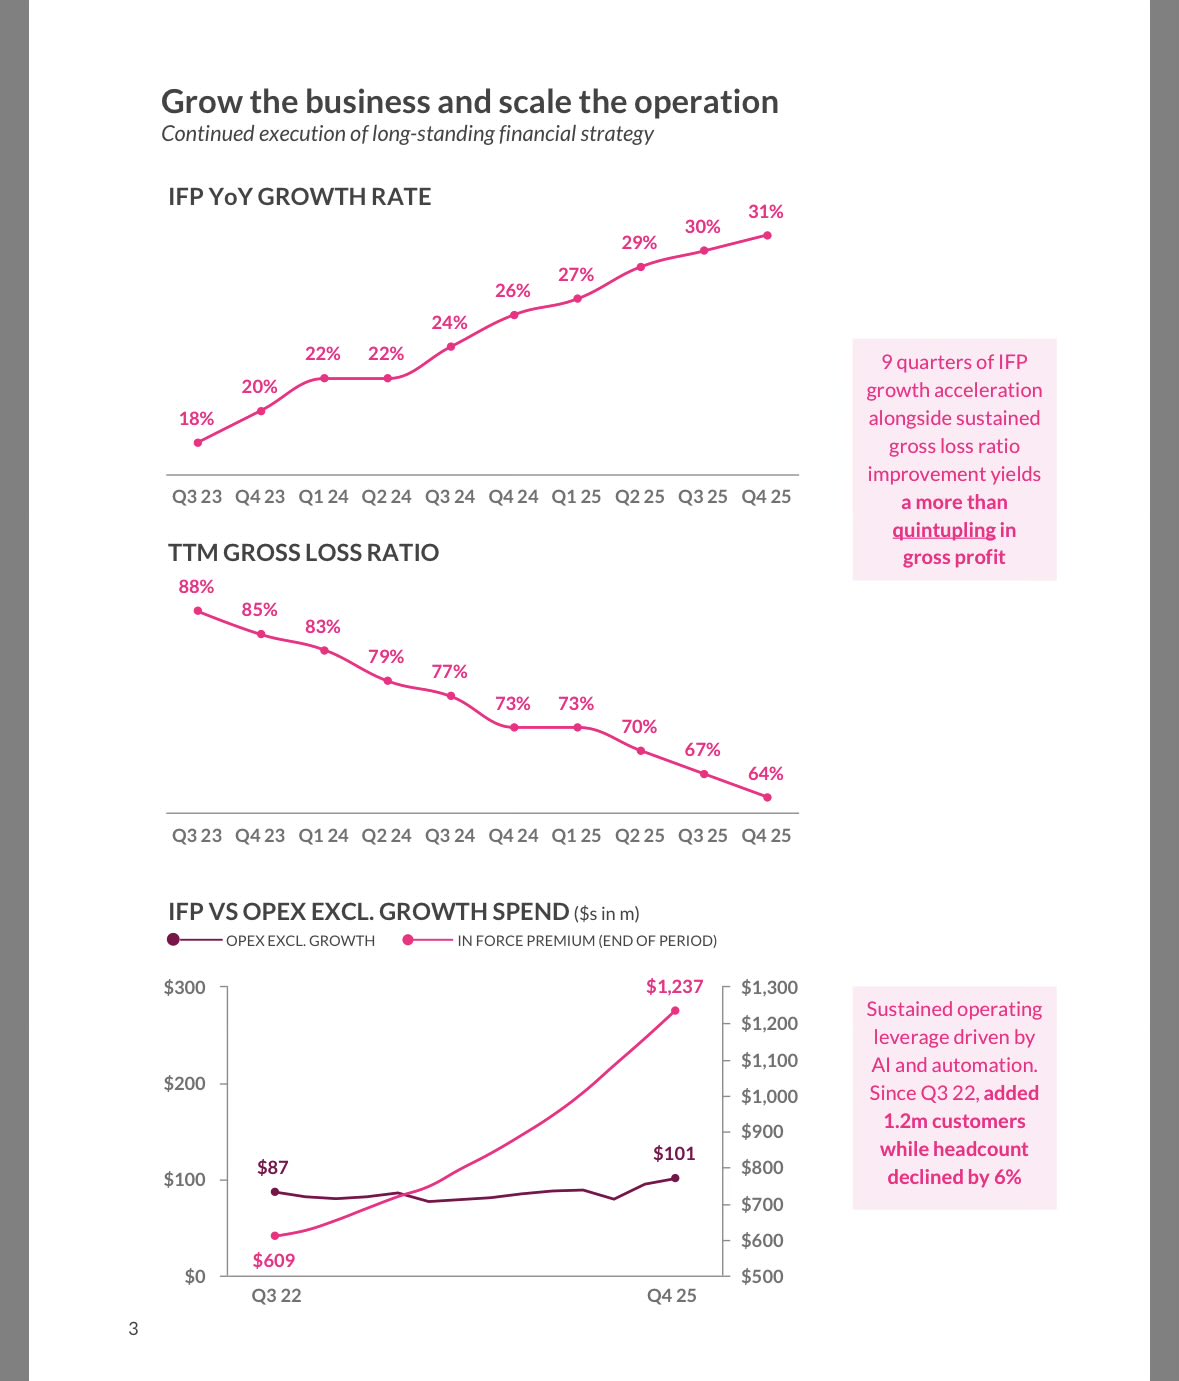
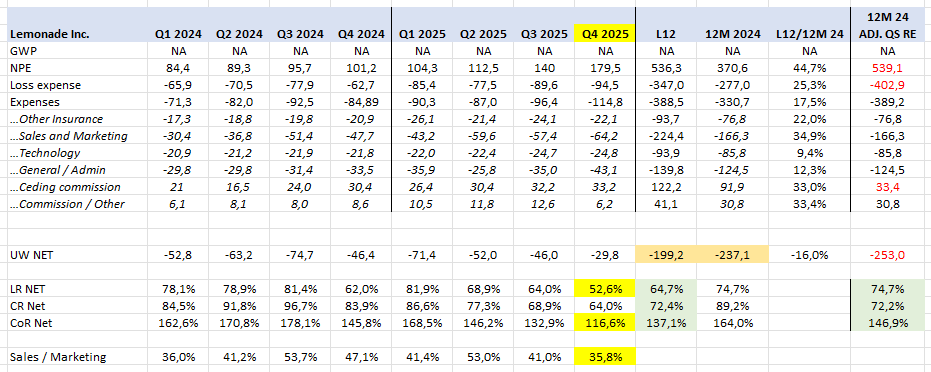
Positive (yellow) - negative (green and brown). Weak guidance. A long way to profitability, insurance business burn approx. 200 MUSD p.a.
7 Likes
That approx. 200M is used for customer acquisition. As Stickström states on X as well. LTV/CAC is churning out good results with all the money put into customer acquisition.
But it’s nice to see positive comments from @AP_1981! 
4 Likes
Unrivaled Investing has updated their Lemonade review. I think it takes growth investments into account well, among other things.
3 Likes