One thought on this. The previous Capital Markets Day was relatively recently, at the end of May. I don’t believe the company’s core message could have changed drastically since then.
On the newer side, there’s the “restructuring and operating model renewal” (as part of the fixed cost reduction program), which was announced in connection with the profit warning. We will likely hear more about those in the near future. As a shareholder, I personally don’t expect continuous reporting on this unfinished business, even though after the massive profit warning, the company’s situation and competitiveness are a bit worrying.
Looking at the CMD slides just now, this caught my eye:
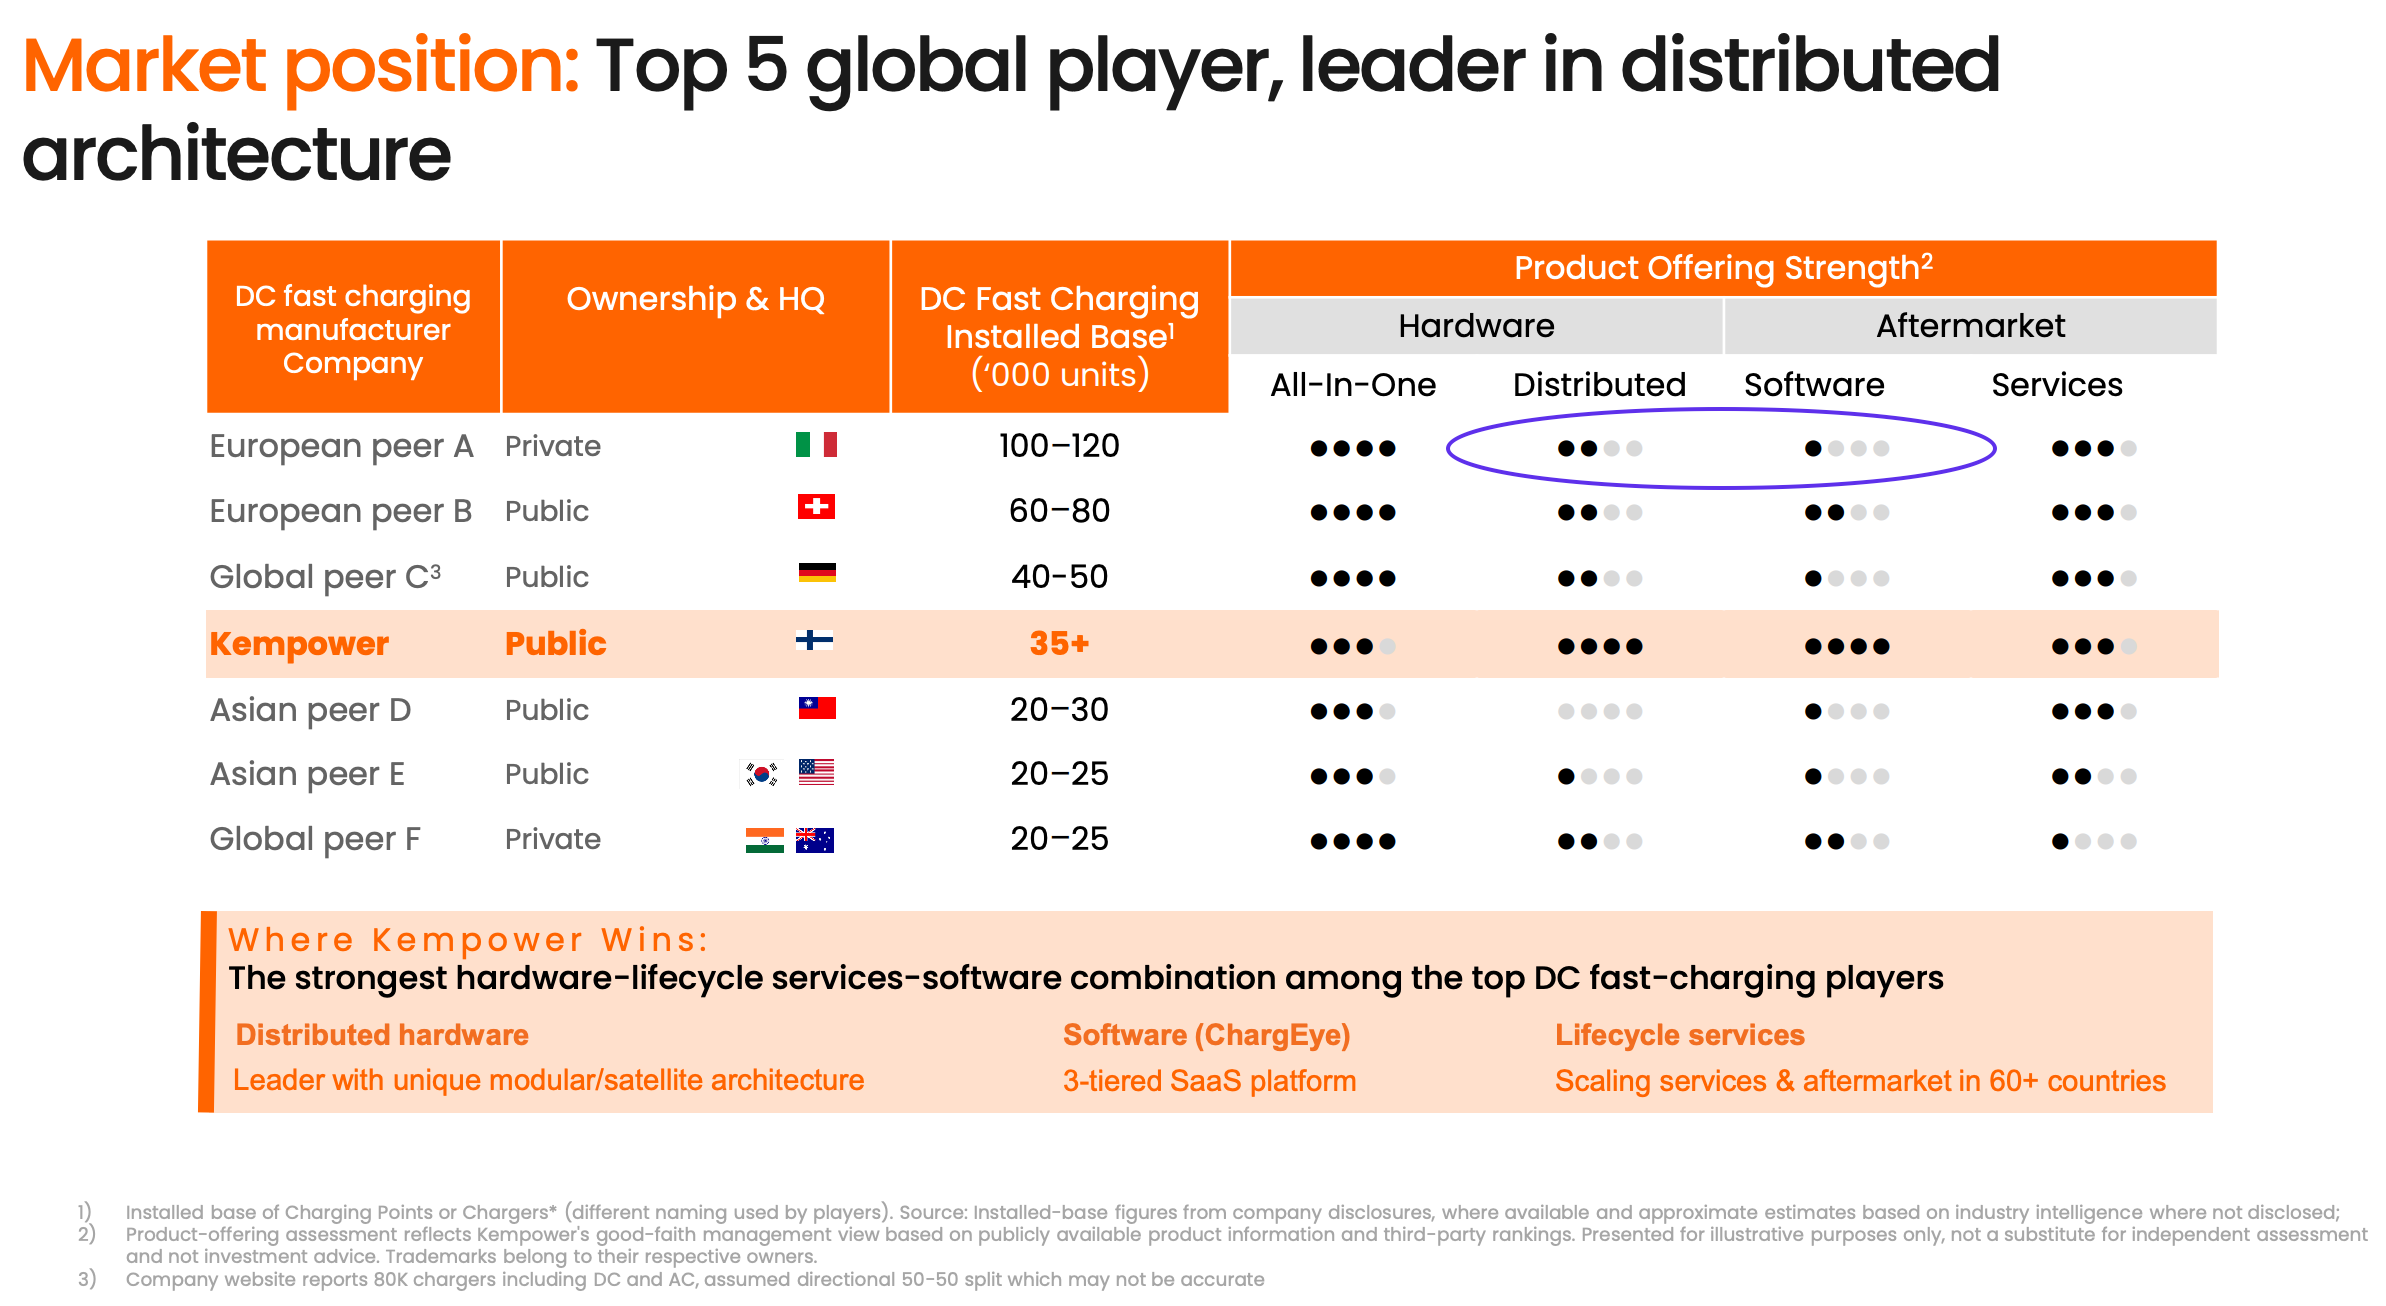
Relating to the (at least previous) competitive advantage in satellite solutions, which interests me greatly, and recent HYC1000 observations.
More specifically, back in May, Kempower’s good-faith assessment was that Alpitronic’s (“European peer A”) distributed strength was 2 dots, whereas Kempower had 4/4.
If and when the HYC1000 works reasonably well in production, as one might assume, Kempower will probably have to raise that assessment too. An analyst, for example, could grill the company management a bit on this the next time there’s an opportunity for questions.
“Do you still consider the Italian ‘peer A’ to be 2/4 in distributed solutions? Even though your customer ‘ABC’ has chosen it over Kempower for certain sites.”
(Side thought: I don’t think Kempower’s IR has been seen on this forum. Maybe I’ll email and ask myself.)
On the same slide, Alpitronic was given only 1/4 on the software side! That’s another detail that raises the question of whether the competitive landscape is genuinely still that uneven at the moment.