The construction industry and a quality company don’t belong in the same sentence.
36 Likes
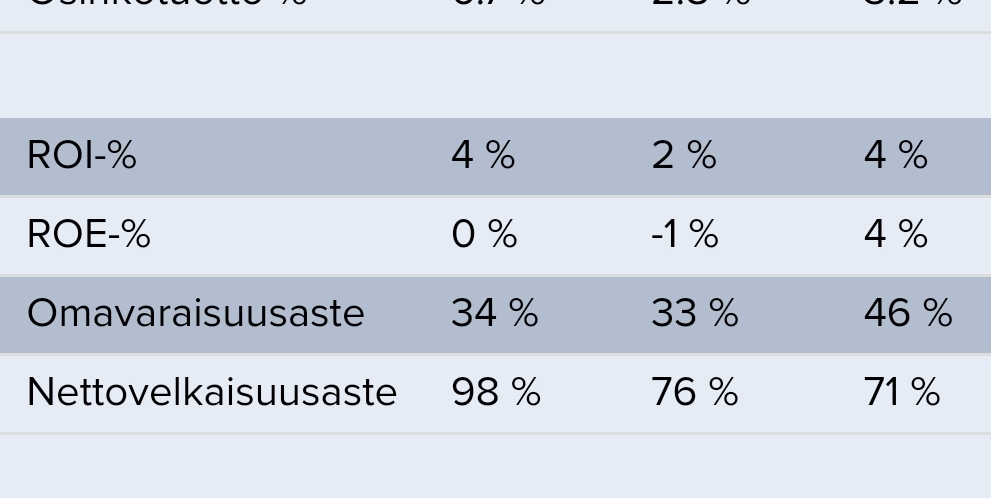
Come on now @jaska7, the ROE has been between -1 and 4% for the last three years, and the net gearing ratio is only 71%. And there’s no need to worry too much about the cyclicality of the construction industry.
20 Likes
My last few weeks:
“Yay, Nasdaq futures are green, today’s the day!!!”
4:30 PM:
Maybe today 
54 Likes
Oh no, and especially since productivity isn’t exactly at the forefront of development… it’s those Estonian construction workers… or is it?
I could add under $110, bought P&G sometime under $75
1 Like
I agree! Though it might not be a new phenomenon. In the more than ten years I’ve been reading investment articles, I feel that even well-known “gurus” have grouped pretty much all companies from OMXH that have managed to stay alive long enough into the quality category. Often it seems that a long history is a sign and prerequisite for a quality company for many, even if the business itself has been in shambles for who knows how long.
Calculated this way, a quality company is often just a synonym for a large, slowly fading old-timer.
And then, for example, a small company with highly profitable, growing business operations doesn’t qualify as a quality company for the same group at all, because it’s small and volatile and doesn’t plod along enough and whatever else. And darn it, it hasn’t even paid increasing dividends for two decades.
This was not an attack on the Q&A questioner, but perhaps more a small criticism of our financial newspaper’s investment sages.
27 Likes
I must admit that I too easily label a company as a quality company. I have tried to be aware of this quality company fallacy of mine. 
About four years ago, Heikkilä&Vilén Show’s episode 31 discussed the concept of a quality company. The episode had good general advice from two professionals, so I will list them below.
Heikkilä’s exaggerated definition of a quality company defines the hallmarks of the quality company fallacy:
“A quality company. It is a company that does not grow, does not pay much dividends, but is expensively priced. It is good to keep in the portfolio, as it looks terribly smart.”
Hallmarks of a quality company á la Heikkilä&Vilén:
- Clearly higher return on capital than the market average and across cycles
- Some permanent competitive advantage that keeps it in the competition
- Evidence of creating shareholder value
- High-quality core business
Points to note:
- Do not too easily label a company as a quality company
- No company is protected by a moat forever
- Quality companies are sold/lightened from the portfolio when they are blatantly overpriced
16 Likes
Nomad’s 2021 Hindsight 
25 Likes
Where did those P/E 10 multiples go?
5 Likes
I hope such trolls don’t multiply on this forum.
65 Likes
Orthex expensive but Tesla cheap 
14 Likes
It’s as if pastor Markku is “a little” excited
5 Likes
He seems to have just received a permanent suspension.
54 Likes
Markkupappi’s videos seem to be working well, though 
I don’t know what to think about this… once again, it’s a little too good to be true. But it’s hard to deny that the pieces are falling into place quite nicely…
6 Likes
Yep, I agree.
What is familiar, “safe,” and has some kind of warm emotional connection is labeled as quality.
Qualities such as competitiveness, return on equity, profitability, the ability to profitably reinvest cash flow back into the business, management’s ability to allocate capital, the company’s ability to react to change, etc., are completely forgotten. 
I didn’t intend the mention to be sarcastic or an attack either, mainly an observation and “thinking out loud.”
I saw a good point related to this on Twitter, that the depth of a moat changes all the time. It doesn’t help if you buy a company whose competitive advantages are actually eroding. You should buy companies whose moats are constantly deepening.
26 Likes
Let’s play “Hyzon Man,” the goal is to avoid challenging questions from the fundamental analysts. 
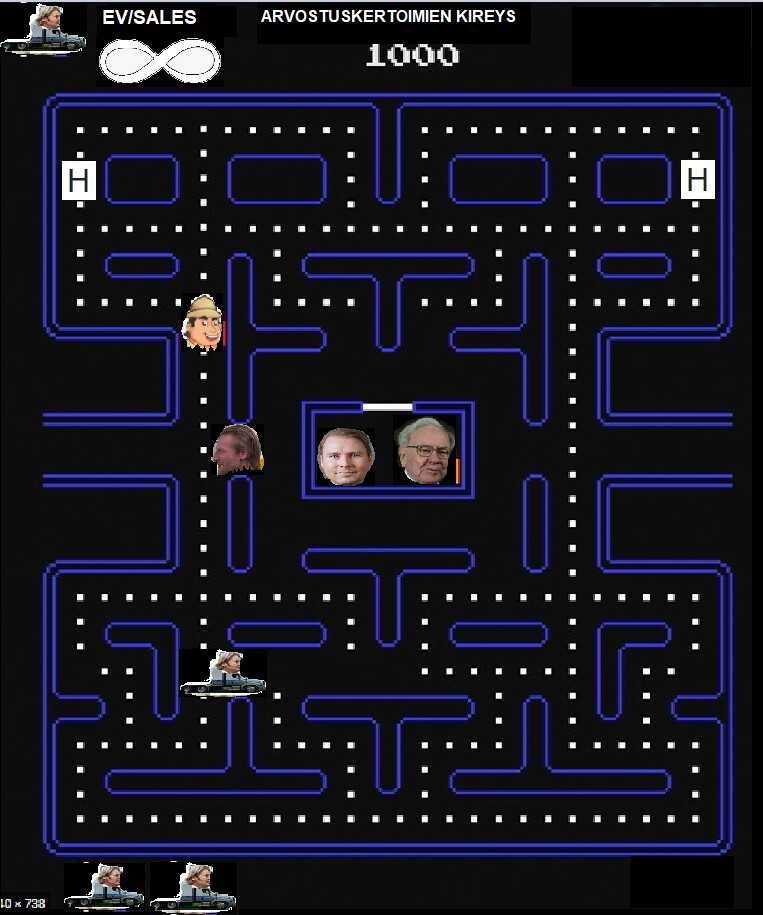
P.S. Yes, I still own the company.

130 Likes
What’s missing here are those pellets that, when eaten, turn the fundamentalists into cowardly and easily consumable bonuses. Oh, wait, sorry, they are there (H).
8 Likes
Those dots are Indecoins. They are indeed missing.
Edit: oh, but the cherries and strawberries. Those are Indecoins.
4 Likes
Spot on.
Construction is twice the work for simple people
1 Like
The earnings season started with an EPS growth of 14 points. A few more like these and even the fundamental boomer will slowly start nodding 
1 Like