Heeros complements its international offering through a partnership - in the future, banking connections will be available via APIs comprehensively to European banks  the company’s angle on internationalization has been to offer Finnish companies targeted services that enhance financial management efficiency for operating in Europe (esp. sales and purchase invoices), and now this partnership complements that offering

2 Likes
@Antti_Luiro spoke about Q2 with interim CEO Niklas Lahti.
Topics:
00:00 Introduction
00:13 Niklas Lahti
01:45 Q2 highlights
03:13 Softness in new sales
04:03 Sales successes
05:24 Change negotiations
06:58 Strategic focus
08:23 Role of new customer acquisition
10:09 Guidance
2 Likes
@Antti_Luiro and @Frans-Mikael_Rostedt have written a new company report on Heeros. 
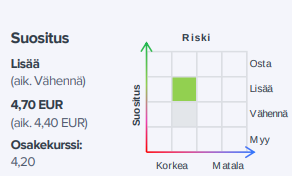
Heeros’s Q2 figures were overall as expected. The company is now moving toward tighter cost control, where profitability and growth efficiency are given higher priority. We lowered our growth forecasts, but our profitability forecasts rose significantly in response. Following the change in direction, profitability multiples (2024-25e EV/EBITA 12-9x, adj. P/E 15-12x) become the pillars of the valuation; in our view, these are already cautiously attractive relative to the risks associated with the profitability improvement.
EDIT:
Here are the morning comments as well. 
2 Likes
Heeros coverage ends. The company has no analyst coverage. 
We are terminating coverage of Heeros’s share after the company terminated the company research agreement. Consequently, we will no longer provide a target price or recommendation for the share. Heeros’s organic growth has been slow in recent years. At the same time, however, the company has turned its profitability positive, increased its customer base, and expanded its product portfolio. Following new cost savings launched in the spring, the company is taking its next steps under new owners in its transformation toward a profitable development phase. In our view, it is crucial for Heeros shareholders to monitor the trajectories of the company’s earnings performance and the organic growth generated with more limited growth investments in the coming years.
3 Likes
Could the momentum of the collapse in Hex small-caps (-45% / 25 months) finally be starting to fade?
Even Heeros hasn’t had a single share on the sell side all day so far.
Sellers have finally managed to sell all they wanted, while buyers remain cautious.
This should be enough of a decline for one time, considering Hex small-caps have been sliding for 750 days straight without a rebound.
1 Like
A quite significant ownership stake in the company for the new CEO. 
https://www.inderes.fi/fi/tiedotteet/heeros-oyj-sisapiiritieto-niklas-lahti-nimitetty-heeros-oyjn-toimitusjohtajaksi
2 Likes
2 Likes
Heeros joins the ranks of IT companies undergoing change negotiations. The release is from Monday, but I missed it then.
According to preliminary estimates, the need for personnel reduction is fewer than 10 people. The negotiations cover the entire personnel of Heeros PLC and its subsidiary Taimer Ltd, a total of 81 people. The aim is to conclude the change negotiations during February.
2 Likes
This small forgotten firm caught my radar; Inderes (Inden) coverage ended a little less than a year ago with a 4.7 EUR “Add” recommendation. Since then, the interim CEO was made permanent, and after stumbling through the end of last year, things seem to be working relatively well again, even if revenue didn’t really grow. The seasonally weak Q1 offered a good improvement in profitability, and operating cash flow nearly doubled. They’re promising gradual improvement for the rest of the year. And why not, as the Finnish economy is already starting to show early signs of life.
Q1 presentation:
This is an interesting setup, as the new main owners (from Norway) paid over 4.5 euros per share, and the current CEO also acquired some for 200k at a price over 4 euros. Perhaps the plan is to steer it into Visma’s lap, who knows.
Are there any long-term Heeros (H) investors on the forum, and does anyone have a view on the company’s products and their competitiveness? I have no personal experience with products in this field.
The trading volume is so low that I think I ruined a good downward streak when I bought a small tracking position, sorry.
6 Likes
Is it perhaps too small a morsel for Visma?
Heeros looks more like an outfit for ECIT AS, if only Heeros were off the stock exchange. Norwegian ECIT buys stakes in smaller companies in this sector and enters into options to buy the rest of the company over the coming years at an agreed EBITDA multiple. Due to the listed status, ECIT would be forced to make a tender offer for the whole lot, even if they initially only wanted two-thirds.
Heeros apparently shut the hatches on pursuing international growth. Only one person remains working in the Netherlands, and the long-worked-on breakthrough into Central Europe apparently never happened. Perhaps trimming the fat and the concluded change negotiations are about getting the company into shape, who knows?
Otherwise, it’s hard to be interested in a company under tight pressure in the domestic market with few growth drivers.
2 Likes
Good performance development and signs of a pickup in new customer acquisition.
2 Likes
Looking good again, hopefully the momentum continues
1 Like
What do you think about this?
Tender offer for Heeros:
Consideration of EUR 5.58 per share, which
includes a premium of approximately 51.6 percent compared to Heeros’ share
closing price (EUR 3.680) on Nasdaq First North on 21 November 2024
22 Likes
Short summary of today’s financial statement release:
- Revenue 2024: Grew by 1% from the previous year, amounting to 11.4 million euros; recurring revenue decreased by 0.2% and was 10.7 million euros.
- Profitability: EBITDA grew by 10% to 2.7 million euros.
- New customer orders (ARR): Increased by 28% and exceeded 760 thousand euros.
- Cash Flow: Operating cash flow rose by 86%, amounting to 3.8 million euros.
- Dividend Distribution: The Board proposes no dividend distribution for the financial year 2024.
- Accountor Finago Oy: Announced a voluntary share purchase offer to Heeros.
- Market Outlook: Growth is estimated for the European SaaS market through digitalization and automation.
Summary generated by FinDL
https://attachment.news.eu.nasdaq.com/a8049d9988552a9b0853e7d0458ac0ff2
e. The stock price probably won’t budge much from this, though 
3 Likes
The operating cash flow is quite strong relative to the tender offer price.
2 Likes
Any guesses if Accountor will reach 90%?
Hard to imagine they wouldn’t, 80% is already achieved.
2 Likes
This offer has indeed been prepared quite carefully, as stated in the board’s statement:
“During 2024, the Company received several inquiries expressing interest in Heeros, and in this context, the Company also actively and confidentially contacted certain other parties that the Company identified as potential strategic partners for Heeros. As a result, during 2024, the Company received expressions of interest from several parties with whom it has held preliminary discussions, and also received preliminary non-binding offers for Heeros, including the offer made by KKR through the Offeror. During this process, the Company allowed the parties to conduct due diligence on Heeros. As a result of this process and the Heeros Board’s assessment of other strategic alternatives available to Heeros, the Heeros Board has concluded that the Tender Offer announced by the Offeror is the most favorable option for the holders of the Company’s Shares and Option Rights.”
Because of this preparation, a competing offer was never likely at any stage.
Therefore, I would consider the offer’s success to be very clear.
2 Likes
Goes through
1 Like