Opening a thread for Fortum

Juha Kinnunen now covers Fortum instead of Petri
Do you have Fortum in your portfolio?
- I own it
- I don’t own it
- I’m considering it
0
äänestäjää
Juha Kinnunen now covers Fortum instead of Petri
Do you have Fortum in your portfolio?
Uniper potentially selling its power plants in France.
E: Adding a company introduction here on 20.11.2018

Great and necessary opening! I’m especially excited about the logo usage at the beginning 

Something good came with Uniper’s portfolio, such as hydropower from Sweden, but also a lot of junk and political risks.
As for fossil fuels, a shutdown or conversion is only a matter of time. The largest share of Sweden’s nuclear power came from Oskarshamn, where 2 of the 3 reactors have been shut down. Demolition costs have already been funded, but to my knowledge, not nearly in full. Of the four reactors at Ringhals, where there is a significant minority stake, 2 have received shutdown orders. The decrease in the number of reactors will not reduce the maintenance costs of the plants in the same proportion. The political risk regarding these plants increased significantly during the previous government term when the red-green bloc, led by Miljöpartiet (Green Party), was pushing to shut down all nuclear power in Sweden through taxation.
Fortum will likely try to drive significant restructuring in Uniper’s portfolio and get rid of certain parts, but it won’t be easy. The German state forced E.ON to include nuclear power in Uniper’s portfolio so that it wouldn’t be able to shirk demolition costs. In other words, Fortum is unlikely to get rid of them if they were to try.
Nord Stream 2 and Russia are unpredictable cases, even though Fortum has experience in the Russian markets.
I’ll be watching from the sidelines and waiting to see what develops. Hopefully, it won’t end up like Vattenfall.
Behind a paywall but you can read something from this 
Here you can find news from Reuters and Gulf News that are not behind a paywall:
https://www.reuters.com/article/us-germany-energy-coal-utilities-idUSKCN1PK0JK
https://gulfnews.com/business/germany-should-quit-coal-by-2038-merkel-commission-says-1.61686156
Quote
Compensation should apply to plants in operation and those that have not yet entered service or were still being built, which includes Uniper’s Datteln 4 plant, the report said. The older the plants, the lower the compensation, it added.
Eckhardt Ruemmler, chief operating officer of Uniper, which operates 3.8 GW of coal-fired capacity in Germany, said the report suggested the Datteln 4, a 1.05 GW coal plant that has so far cost 1.2 billion euros, would never enter service.
Quote
RWE, Uniper, EnBW, and Vattenfall are likely to shut down approximately 12.7 gigawatts of production (2022). The total annual amount of compensation is around 2 billion (2023), and it appears to cover producers as well as consumers, and probably also regions economically dependent on coal.
Compensation paid to producers depends on the age of the production facilities. Uniper’s plant fleet is old, with the exception of Datteln 4, which may not even be started. There are many claimants for the compensation pie, so it is unlikely to cover lost revenues. As the articles reveal, this is a compromise with which producers do not seem very satisfied.
Germany’s decision cannot be considered a surprise. Only the future will show how successful Fortum’s investment in Uniper will be. To me, however, this has looked a bit like the cash had to be “used” for something, and they couldn’t wait for better investment opportunities.
In my opinion, a stronger lead could have been taken towards renewables, with the (political) trend being so clear. Results from ITER (and a few private ventures) on cold fusion can, optimistically thinking, be expected perhaps in the latter half of the next decade, meaning that at least one technological generation could be monetized before a truly clean and massive-scale alternative (current estimate around 2050) becomes available.
Edit: typos
“Fortum’s €2.5 billion bonds”
If I understood correctly, Fortum is taking on debt to repay existing debts. Opinions on this?
Isn’t this just normal loan restructuring? I don’t know 100% for sure,
but the interest rates didn’t seem very high. So if the old rates were higher, there’s immediate savings right there 
electricity prices from here
e:
https://www.fortum.fi/media/2019/01/fortum-tahtaa-pelto-ja-puubiomassan-jalostuksella-globaaleille-biotuotemarkkinoille
https://www.fortum.fi/media/2019/01/fortumin-ja-rusnanon-tuulivoimasijoitusrahasto-kaynnistanyt-50-mw-tuulivoimapuiston
Does anyone have any fundamental information on what’s dragging Fortum down so drastically?
SMRs (Small Modular Reactors) are again in the spotlight.
Municipalities and new energy companies are very interested in small reactors for producing district heating, among other things.
Quite significant legislative changes would be needed for these to become a viable option for producing district heating or electricity. It somehow feels like these discussions always focus only on the lower acquisition cost of reactors, but the understanding of the operational aspects of nuclear power plants is conspicuously absent. Without legislative changes, the operational costs of an SMR plant relative to its power output are simply not competitive with large units.
It remains to be seen whether the Norwegians’ sales will cause downward pressure on Fortum’s stock in the near future. I’ll have to monitor the situation 
At the turn of the year, the fund seemed to have slightly over 1% ownership in both Fortum and Uniper. No decision has been made yet, but a committee was appointed to investigate the matter. Additionally, there are two levels on the list (observation / exclusion), so the block is unlikely to be immediately sold even if the rule change comes into effect. For example, Berkshire Hathaway Energy Co is on the list (observation / 10.07.2018), but the fund still owns Berkshire Hathaway Inc shares (31.12.2018 / 0.74%).
Fund holdings as of 31.12.2018
https://www.nbim.no/en/the-fund/holdings/holdings-as-at-31.12.2018/?fullsize=true
Reports and rules can be found:
The list Fortum probably doesn’t want to be on:
https://www.greenoptimistic.com/finland-battery-recycling-20190412/#.XLTIAPdOk0P
The price just keeps going down 
Uniper’s annual general meeting was on 22.5, I think.
Uniper’s current share price is about 27€ / Fortum’s paid price was (quickly googled) 21.31€/per share. Could the final redemption possibly be expensive if it happens? 
 On the other hand, Fortum could, in my understanding, just buy from the market over time… (if that Uniper water thing in Russia can be outsourced)
E: Nordea predicted Fortum to be a potential earnings disappointment in Q1. Consensus price: 20.6€
Fortum has been a question mark for me for a long time. I trust Lundmark’s work. He has been very clear and convincing, e.g., in his presentations at investment fairs back in 2015/2016. And since then, he has systematically done exactly what he said he would. So, this is not the question mark, but these are:
Previously, Fortum has strongly reduced fossil energy production and championed green energy. Now, with Uniper, a lot of coal power came along, as well as gas, oil, and nuclear power. Energiewende, or the transition to carbon-free energy, is not an easy task in Germany, especially when they also want to phase out nuclear power. Regarding Uniper, @Rauta wrote descriptively about the situation in Sweden earlier in this thread.
@Nyyb.K, in turn, referred to the Norwegian Oil Fund’s new requirement to get below 10,000 MW in coal-produced electricity. As KL wrote earlier:
‘The Norwegian Oil Fund has tightened its stance on coal use. According to the new rules, the Norwegian Oil Fund should sell its holdings in companies whose annual coal-fired electricity production exceeds 10,000 MW. The previous rule was that the fund could not own companies where over 30 percent of electricity production was coal-based.’
Fortum passed the previous rule. From this new milestone, it apparently gets off the hook by selling Uniper’s coal power plants in France and Brazil. But will the requirements get stricter? Norway has a fairly large stake.
Does anyone have a crystal ball to see how electricity prices will change? Electricity consumption is increasing as, for example, traffic and telecommunications need it more and more. And if energy has to be produced green, then methods are needed to satisfy the growing energy demand. Fortum has traditionally been a pioneer in green energy and recycling. Could they or we (and if shareholders are involved) actually have a bright future?
I also read Inderes’ latest report, and it contained these same issues, but no answers. The numbers look calmly good - but those hunting for gazelles should not bother. Are there any skilled energy sector specialists and clairvoyants on this Forum to shed light on Fortum’s future?
The crystal ball is currently too foggy.
But if you are interested in the electricity market, here are some links:
Market data and information on the Nordic electricity markets
Information on the markets
You can use the filters to see, for example, upcoming major maintenance outages.
Next year, at least in Sweden, nuclear power plants will have longer than usual annual maintenance shutdowns, but these are not yet visible in the list I linked (they are, however, known to the market). The law obliges the introduction of new backup cooling systems (a significant investment, which is spread over several years).
Thanks @Rauta!
I’ll look into these, but as you said, things will only become clear over time. Let’s stay alert, shall we? The position isn’t huge, but the company is good and basically has every chance to be a future winner.
https://www.fortum.fi/media/2019/04/maailman-ensimmainen-markkinapaikka-hiilidioksidin-poistolle
You can see emission allowance prices (EU) here
@Juha_Kinnunen How do emission allowance prices affect Fortum’s result?
Electricity price is 
Emission allowance prices
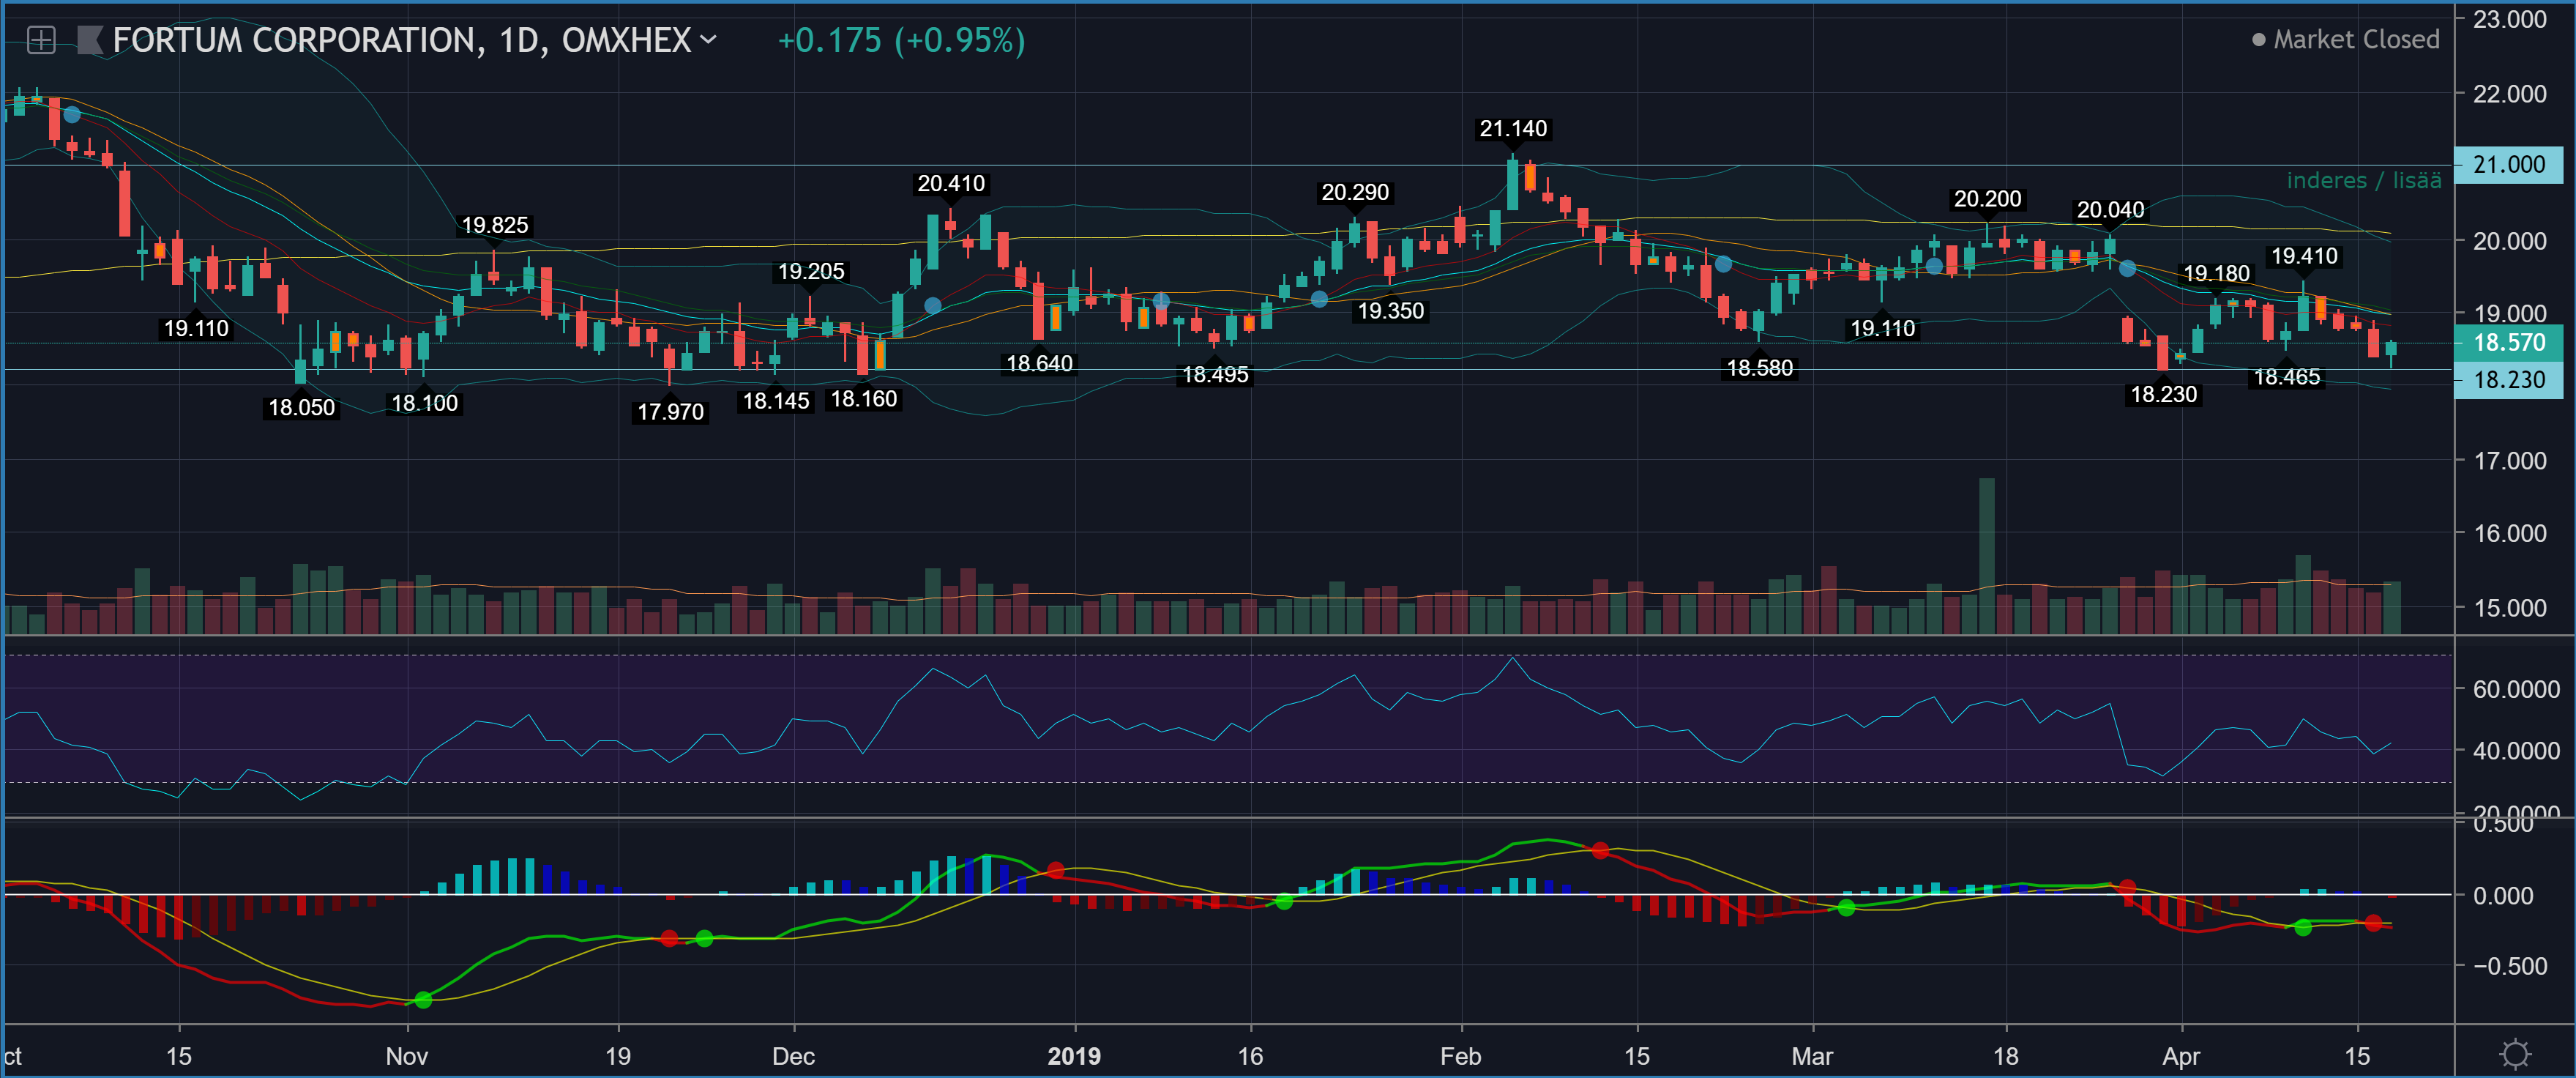
Fortum’s share price  (dividend was detached less than a month ago @19.98)
The rise in the price of emission allowances should, in principle, have a positive impact on Fortum’s current earnings precisely through the increase in electricity prices. Approximately 95% of Fortum’s electricity production is CO2-free, which is why the rise in emission allowance prices does not cause corresponding costs.
At least previously, Fortum has also received more emission allowances than it needed, which is why it has been able to sell allowances at a profit. I have not investigated the current situation in more detail, as these are not significant for a company of Fortum’s size. We also do not have information on how the company has (possibly) traded emission allowances.
In the short term, the share price is driven by many other factors than the short-term price of electricity and the earnings level, so it is not advisable to draw major conclusions based on these in the short term. At present, Fortum is certainly significantly affected by, among other things, the Uniper situation and related speculations. We will be wiser regarding Fortum after the company’s Q1 report.
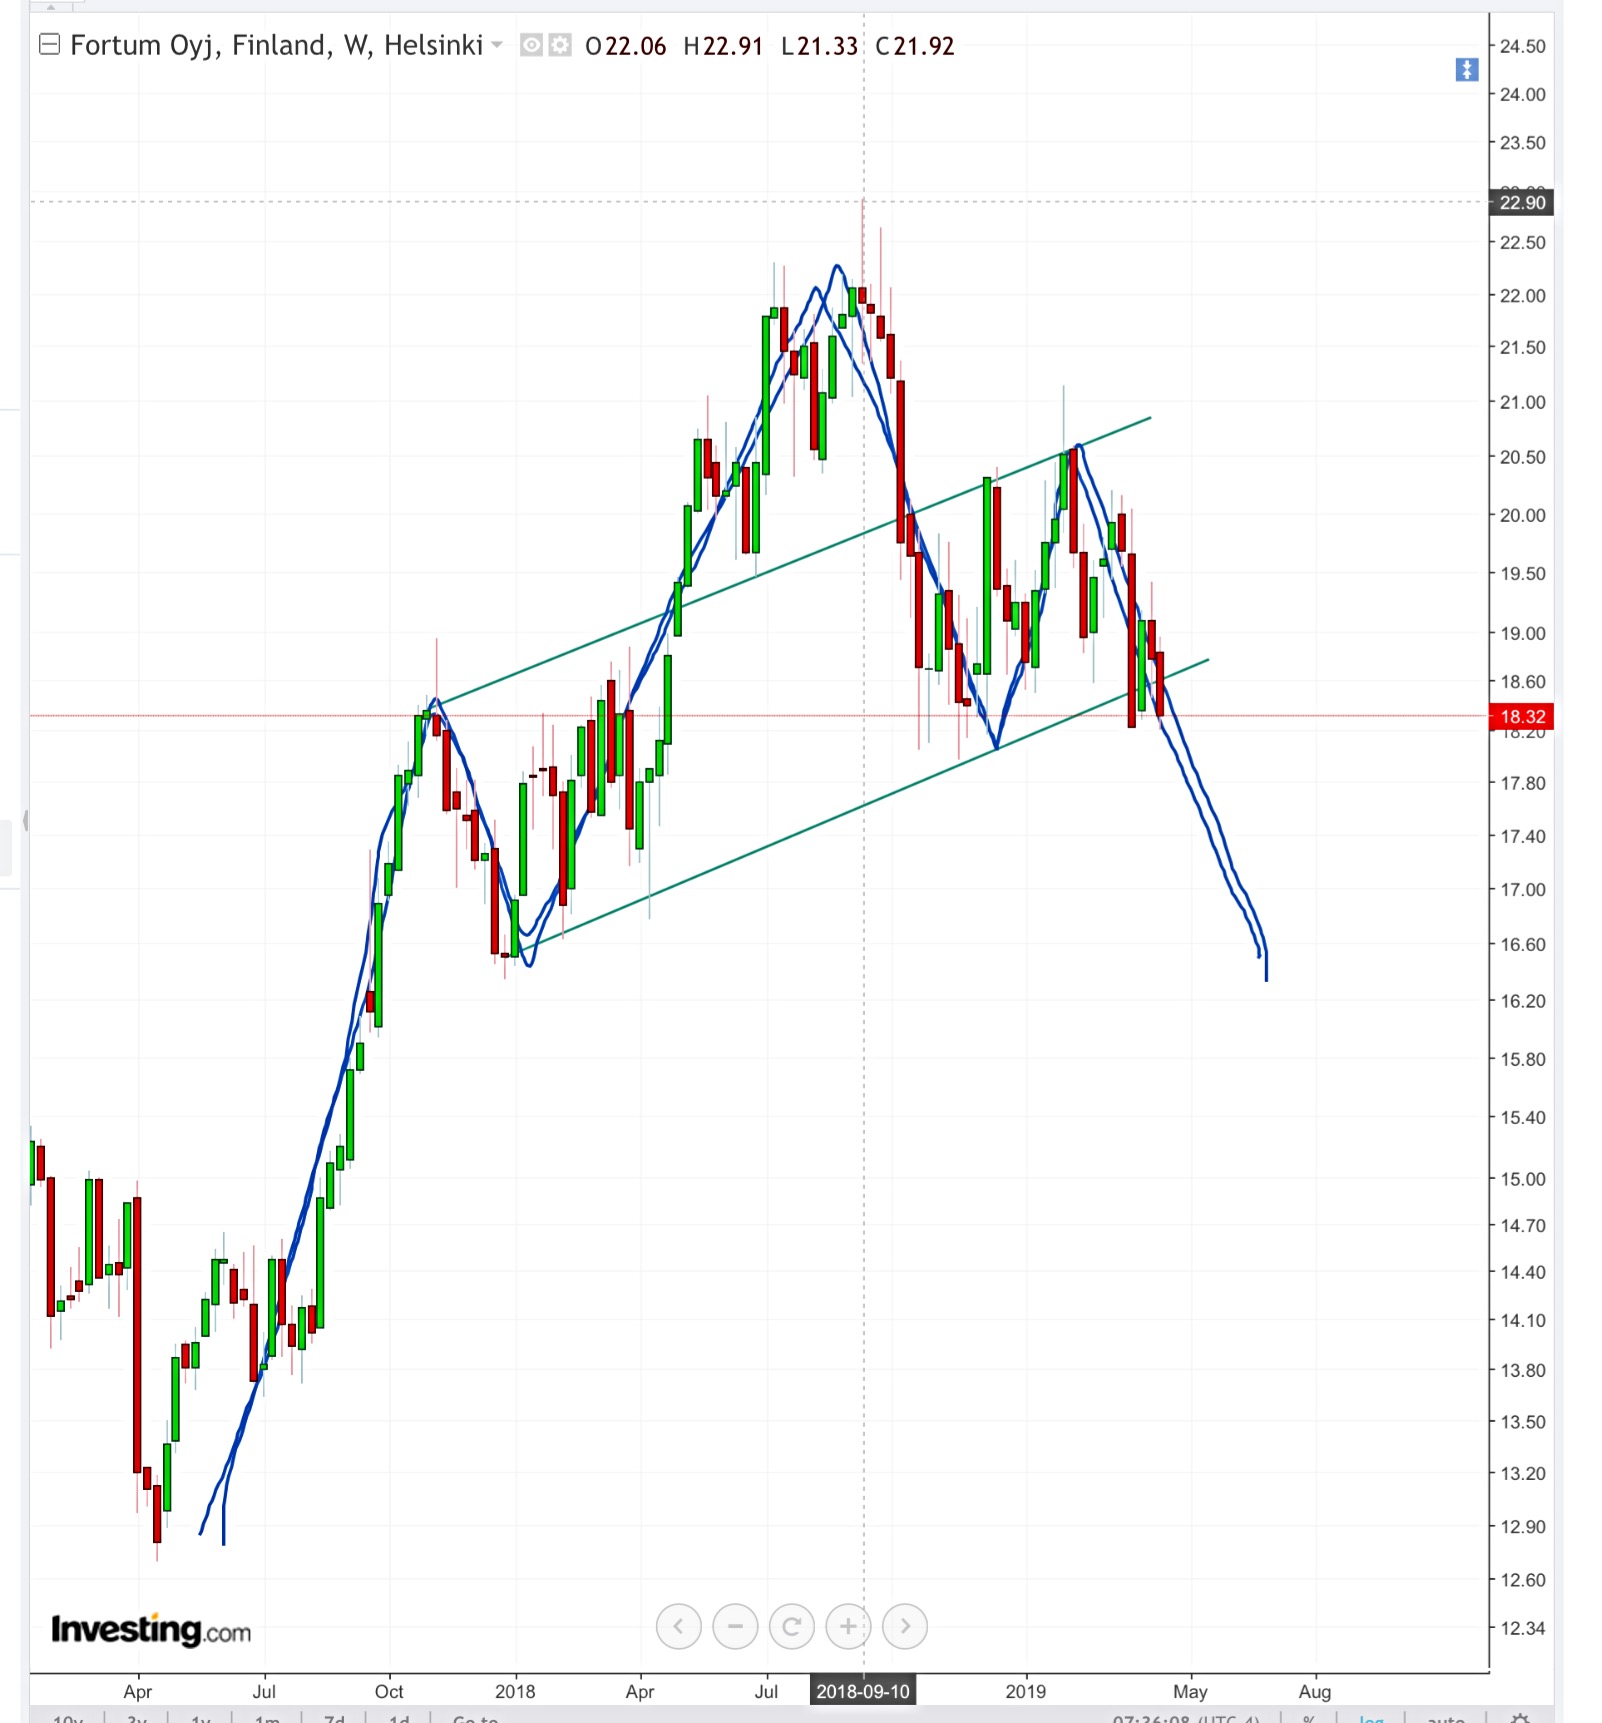
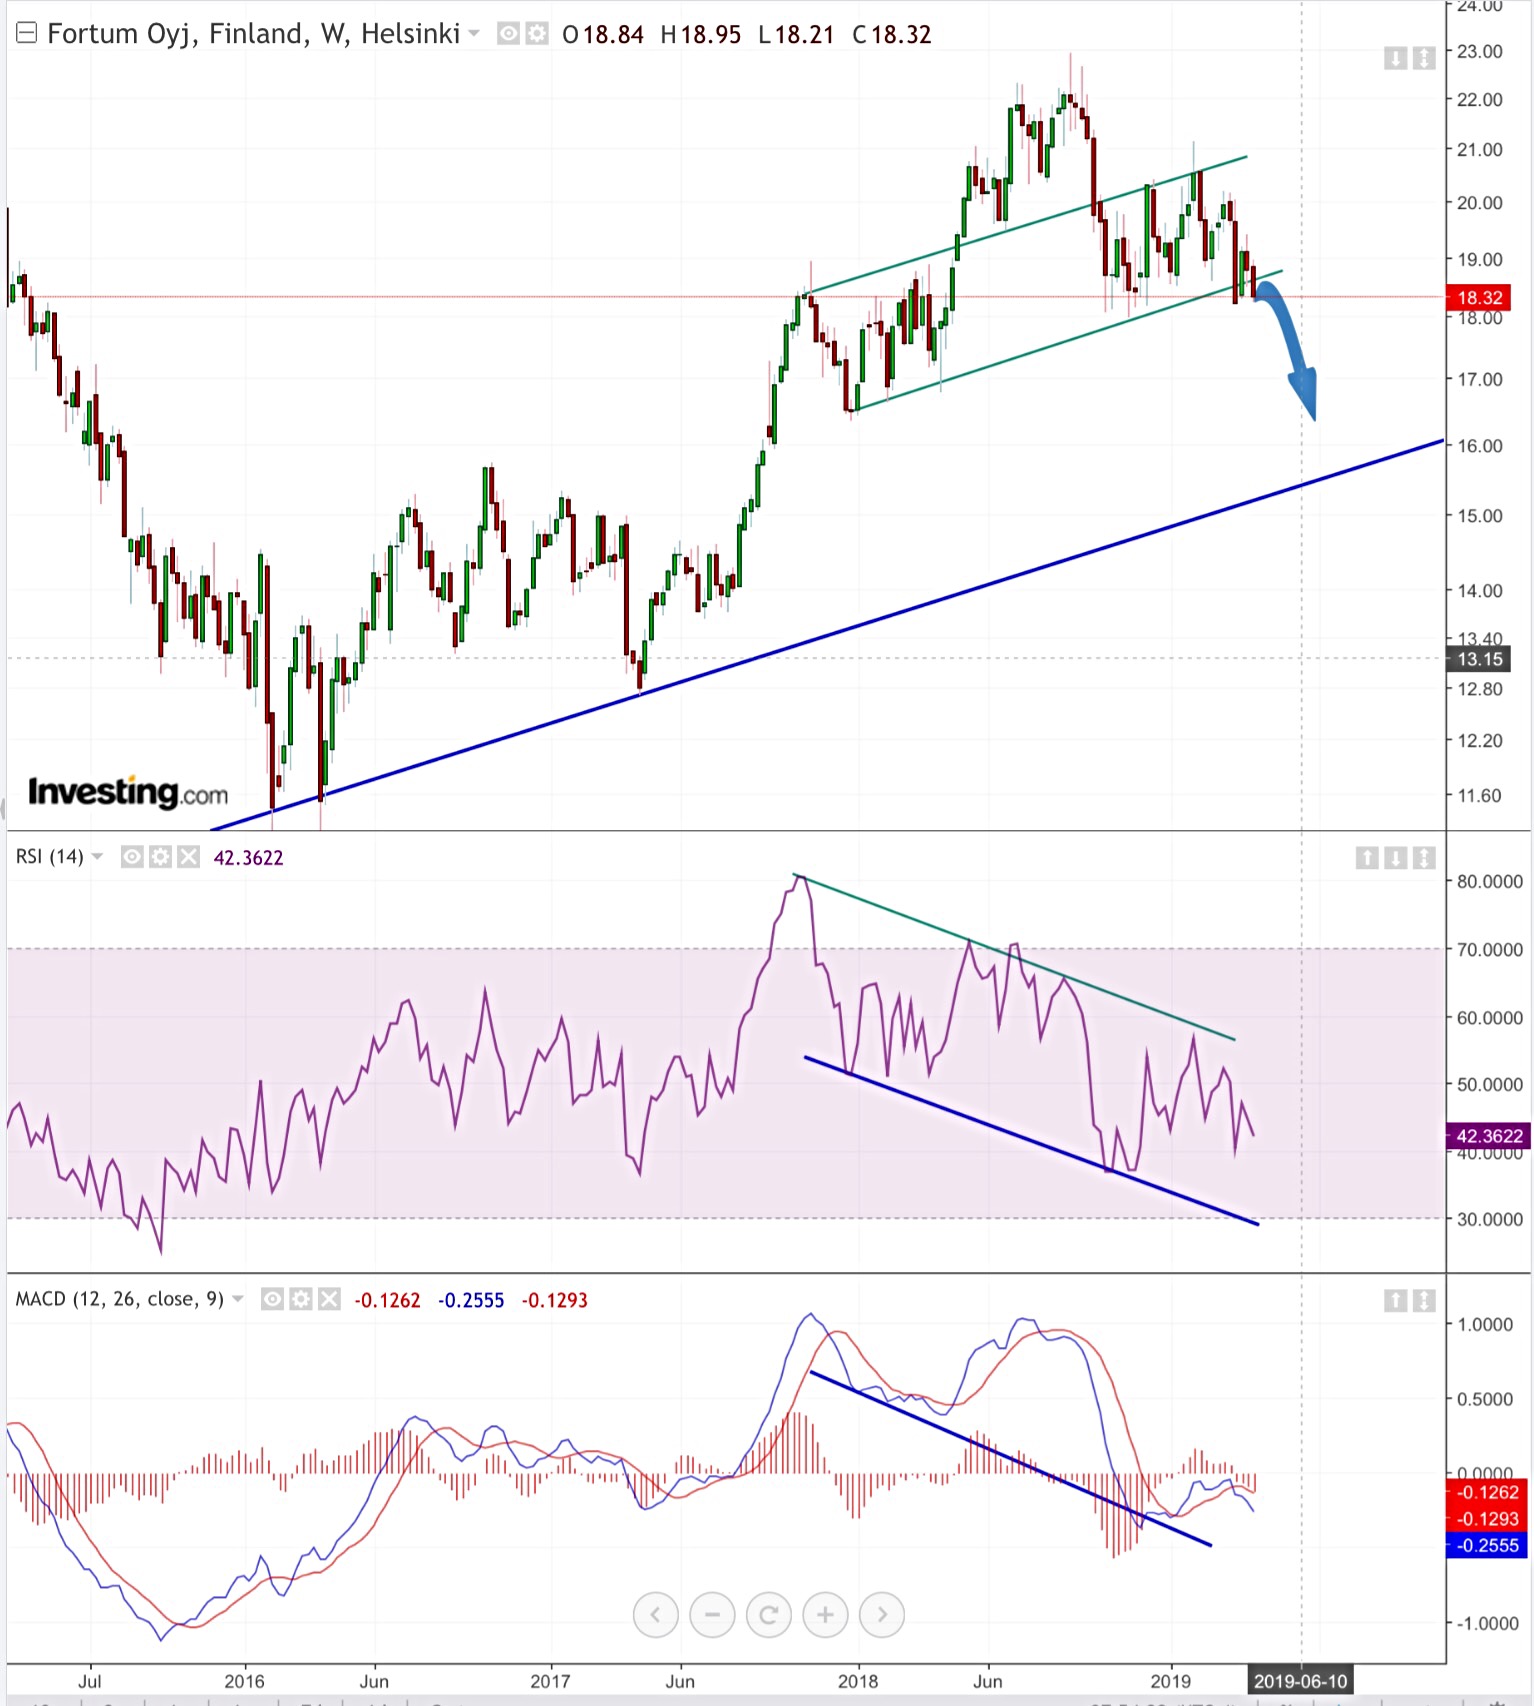
It’s starting to look to me like the dandruff pattern figure of Fortum already has its right arm broken.
… otherwise, it looks technically quite weak; momentum patterns predict a downtrend rather than a jump. MACD and RSI are drawing quite strong divergence against the price curve.
I’m waiting to see if it reaches around 16 euros in the autumn before I consider investing. However, Fortum has a pretty okay outlook in the big picture, so it’s not at all an excluded company from a pension portfolio.