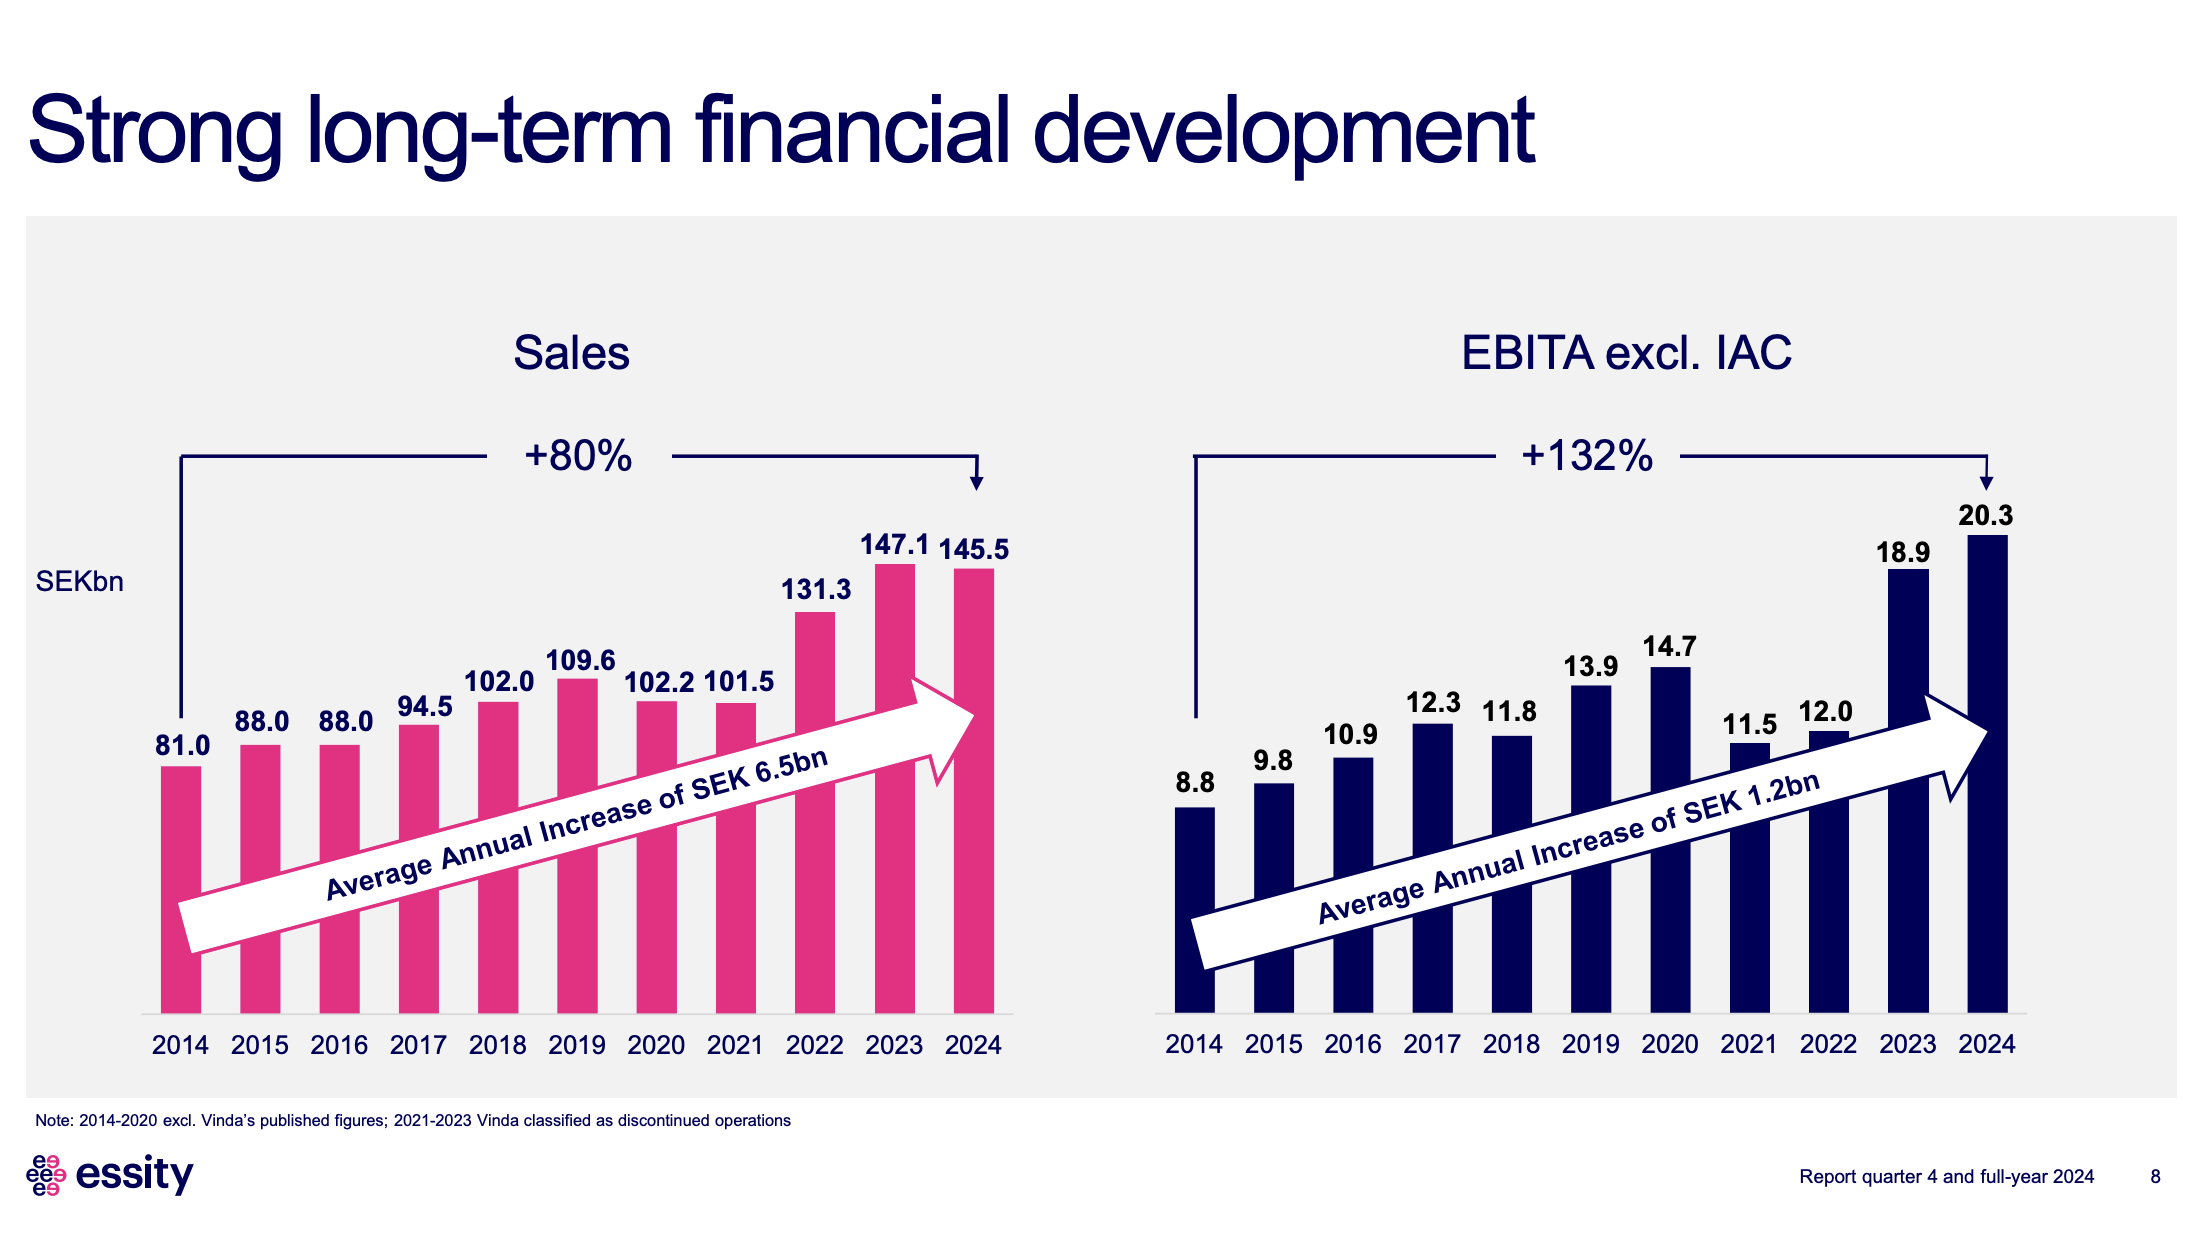
Let’s continue the almost dead discussion about a quality company.
Essity has continued its steady progress. The dividend is growing again and the balance sheet keeps improving. The company is starting to have the strength to either buy back more of its own shares or embark on complementary acquisitions. I would definitely consider it among the best Nordic companies. A deadly boring and profitable company. The strategy to grow from traditional bulk products to higher value-added products has worked. For example, the Health & Medical segment achieved an 18% EBITA margin, which I would consider excellent.