Engcon released its earnings yesterday. The growth company reported a decline in orders, and the stock plummeted by up to 20% yesterday at its worst.
In 2022, the king of tiltrotators was listed on the stock exchange, with its IPO prospectus painting a picture of explosive growth. In Sweden and Finland, the penetration rate of tiltrotators is 90%. Soon enough, the rest of the world would follow suit. Engcon holds a market share of nearly 50%. As the excavation world transforms, Engcon’s shareholders would win too.
Globally, however, the breakthrough of these contraptions hasn’t progressed much in recent years. Judging by Engcon’s market share estimates and its own figures, the market is roughly the same size as it was in 2022.
This order and sales chart also depicts very steady—not explosive—development.
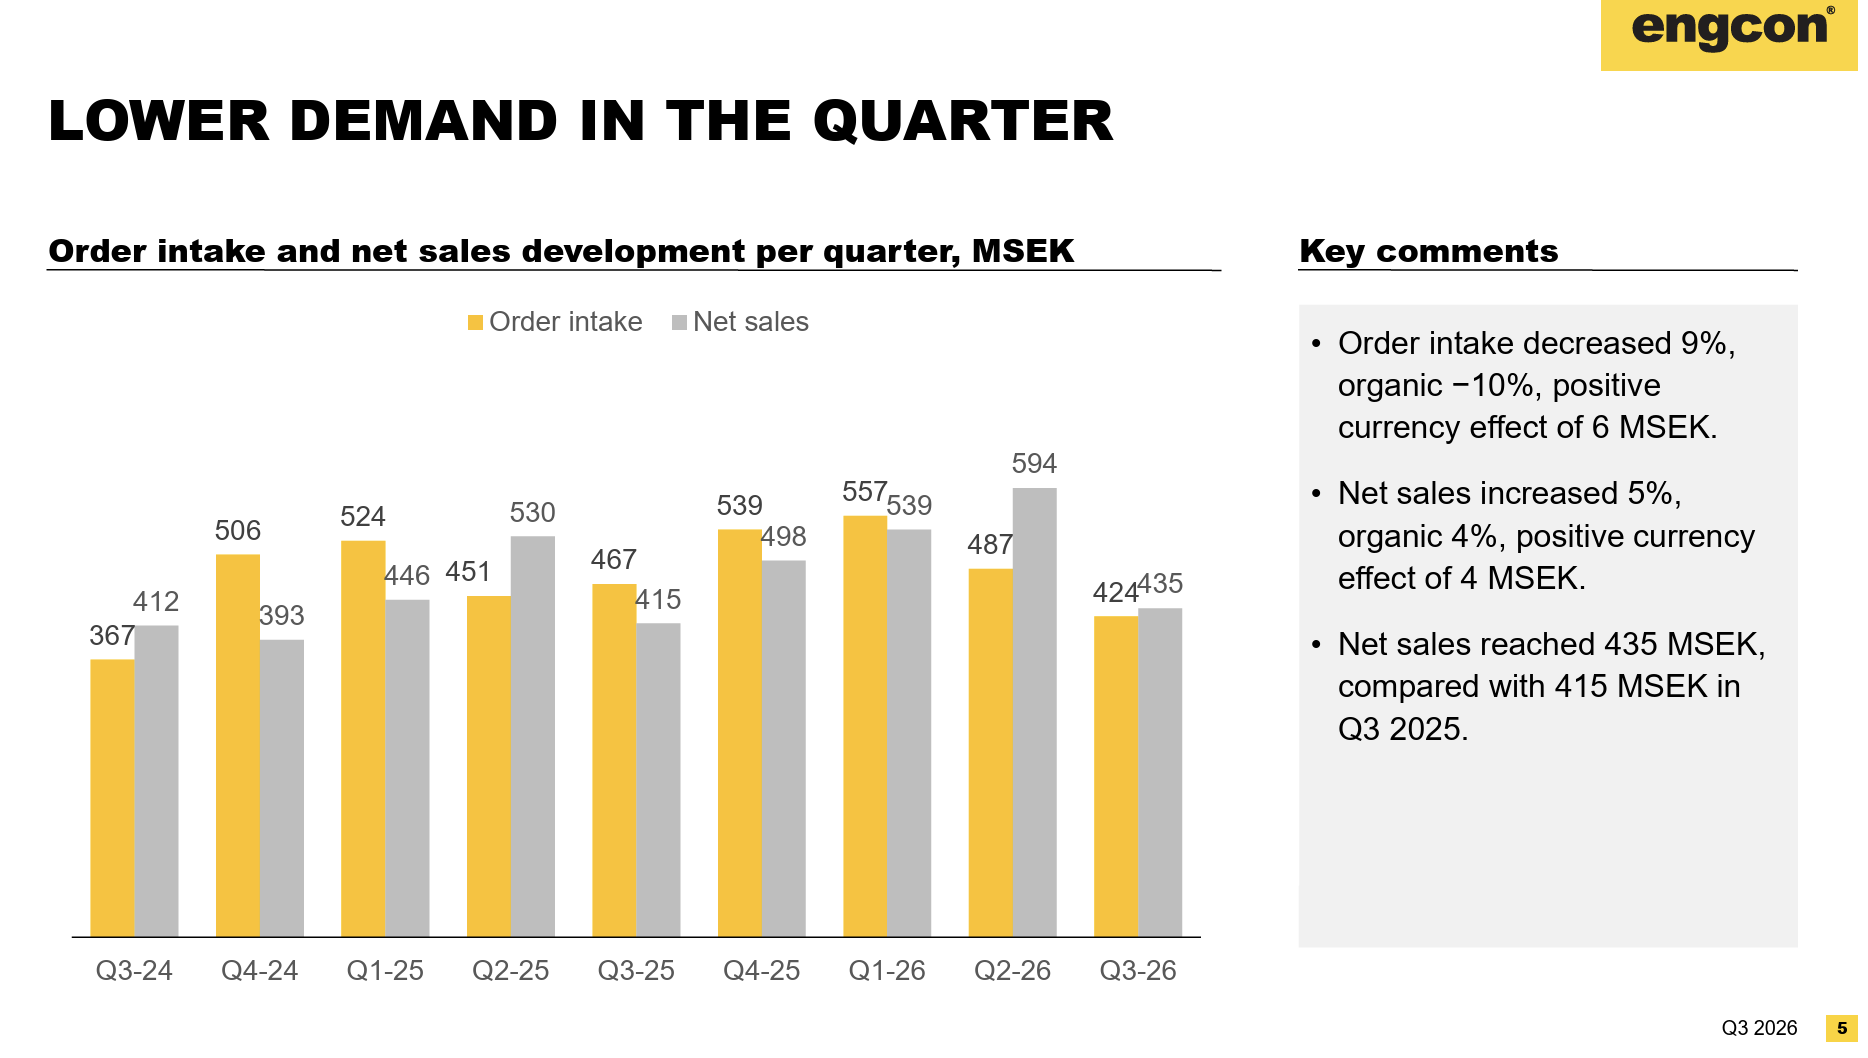
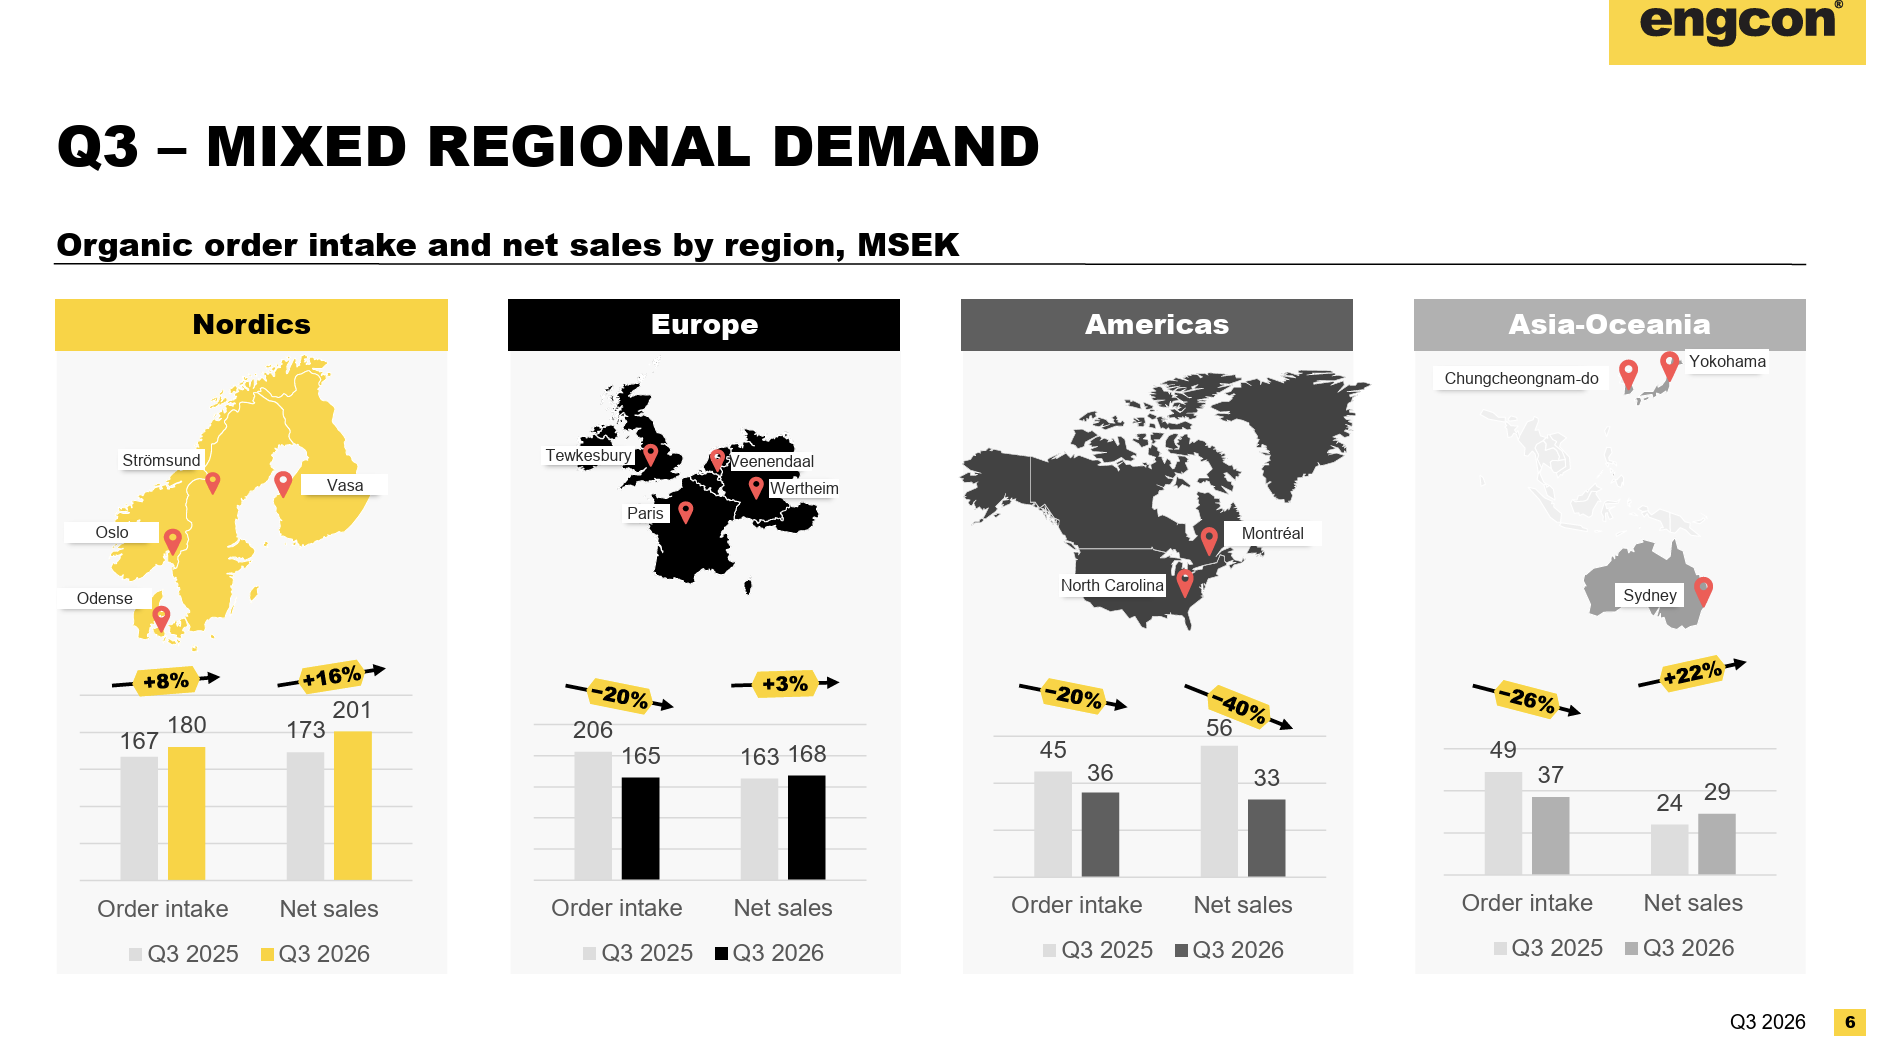
Macro factors (and a bit of their own execution) are blamed for the sluggish development. Especially in the United States and France.
People have paid rather sweaty multiples for the stock, I’d guess because if things take off into explosive growth, who wouldn’t want to enjoy growth greased by >40% returns on capital and ~20% margins? Now the stock has roughly halved from its peaks, yet it is still being valued at almost 10 billion SEK against sales of under 2 billion SEK.
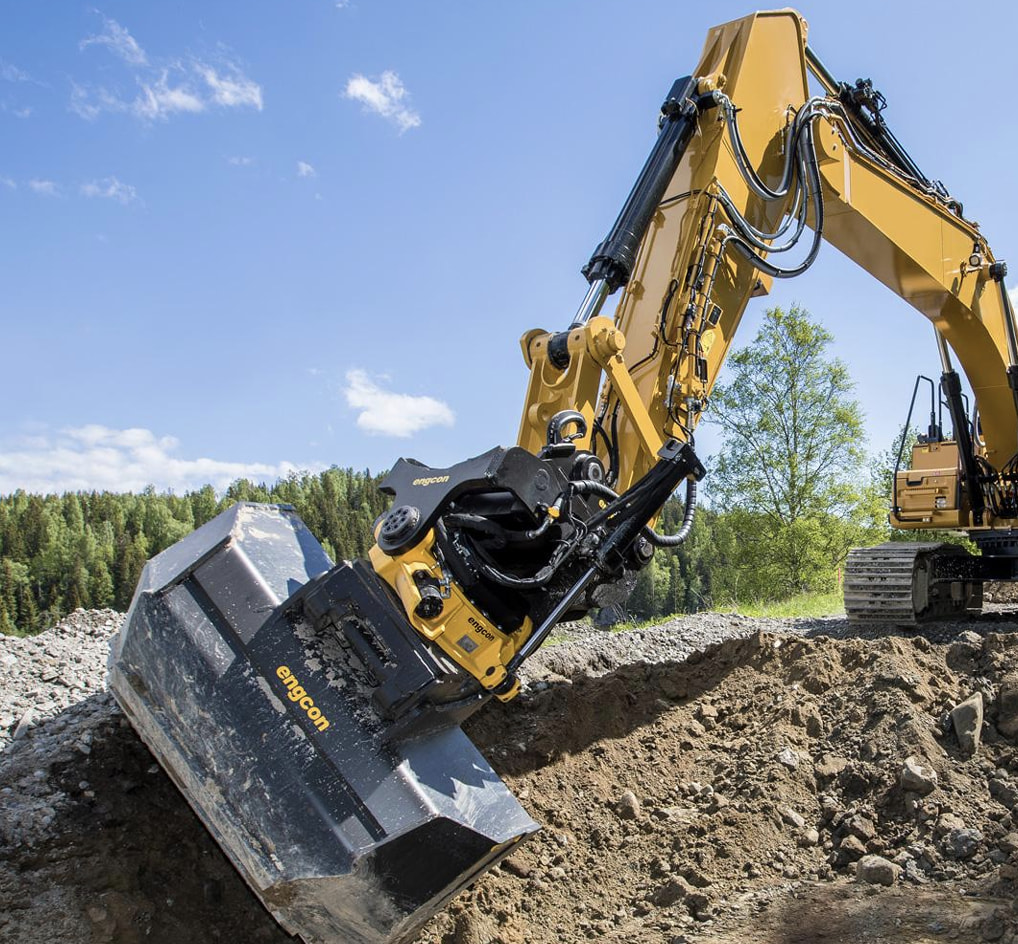
The machines look sweet, so let’s decorate this quiet thread with one more picture.
Here’s also a link to the audiocast (which is produced by Inderes  )