What happens in practice in February if you don’t agree to sell your Citycon shares for €4.0?
2 Likes
The stock will normally remain listed unless the principal shareholder reaches 90% ownership, which would entitle them to compulsorily acquire the remaining shares from minority shareholders. It seems likely that the 90% threshold will not be met and the stock will remain listed.
11 Likes
Citycon tender offer poll
- I accept the offer
- I do not intend to accept the offer
0
äänestäjää
Let’s do a small poll out of interest regarding Citycon’s public tender offer.
What does the forum think? 
4 Likes
If/when the acquirer doesn’t get 90% of the shares, the shares will remain on the exchange.
When the 4.0 EUR redemption offer was announced, the share price rose from 3.0 EUR → 4.0 EUR.
The redemption offer has undoubtedly supported the price, so it will be interesting to see what happens to the price if the 90% threshold isn’t exceeded and the redemption offer isn’t extended.
→ it drops if you don’t desperately want to stay on the catman’s sled?
If the offer falls just short, it could also be that speculation starts that a new redemption offer might come sometime after 6 months.
→ it rises?
Interesting to follow how this one turns out as well…
6 Likes
 What if 90% is not met?
In this case, there are two main options:
 A) The company remains listed (but becomes illiquid)
Only a few shares may remain in the free float
Trading may be very minimal
The price may no longer reflect the true value
B) Voluntary delisting
The company can still apply to delist if:
the general meeting approves it
minorities are offered a reasonable exit (often a new tender offer)
Nasdaq Helsinki also evaluates:
whether trading is functional in practice
whether the listing requirements are met
Quote AI. If option A occurs, then who would buy these and at a decent price? If the stock were to be delisted from the exchange, would it become even more difficult?
So the easiest and safest option would probably be to get rid of the Citycon shares after all?
6 Likes
Personally, I think there are countless better risk-reward ratios out there, starting with a simple savings account. The risks are high if you stay hanging on to Citycon, even though at the same time I feel that €4/share is far too little for the assets. I consider it likely that if the cat man gets, say, 85% of the shares and the stock remains on the exchange, the share price will start drifting lower on low volume. There won’t be dividends either… I intend to accept that this didn’t result in huge returns and move on.
Edit: You can look at the Musti share price for a bit of a precedent.
11 Likes
I completely agree, meaning that even though the offered price is blatantly low, I see nothing but bad and even worse options here. If there were even a slight chance that the cat man (the bidder) could reach that 90% threshold, I think it would be within the realm of possibility for the arbitration court to raise the price, but since there are life insurance companies as major owners here as well—and they are famous for hanging onto these for years (e.g., Musti and Finnlines)—reaching 90% is highly unlikely. This, in turn, will lead to the inevitable drifting down of the share price, as no dividends will be paid in the future.
2 Likes
As long as dividends aren’t paid, even Catman won’t get any income stream from this, and death will inevitably take its toll at some point. Citycon is able to sell its assets close to NAV, so I see no reason to sell my own shares at more than 50% below NAV.
8 Likes
I would dismiss that AI analysis as completely worthless — starting with the deadlines, it is full of misinformation.
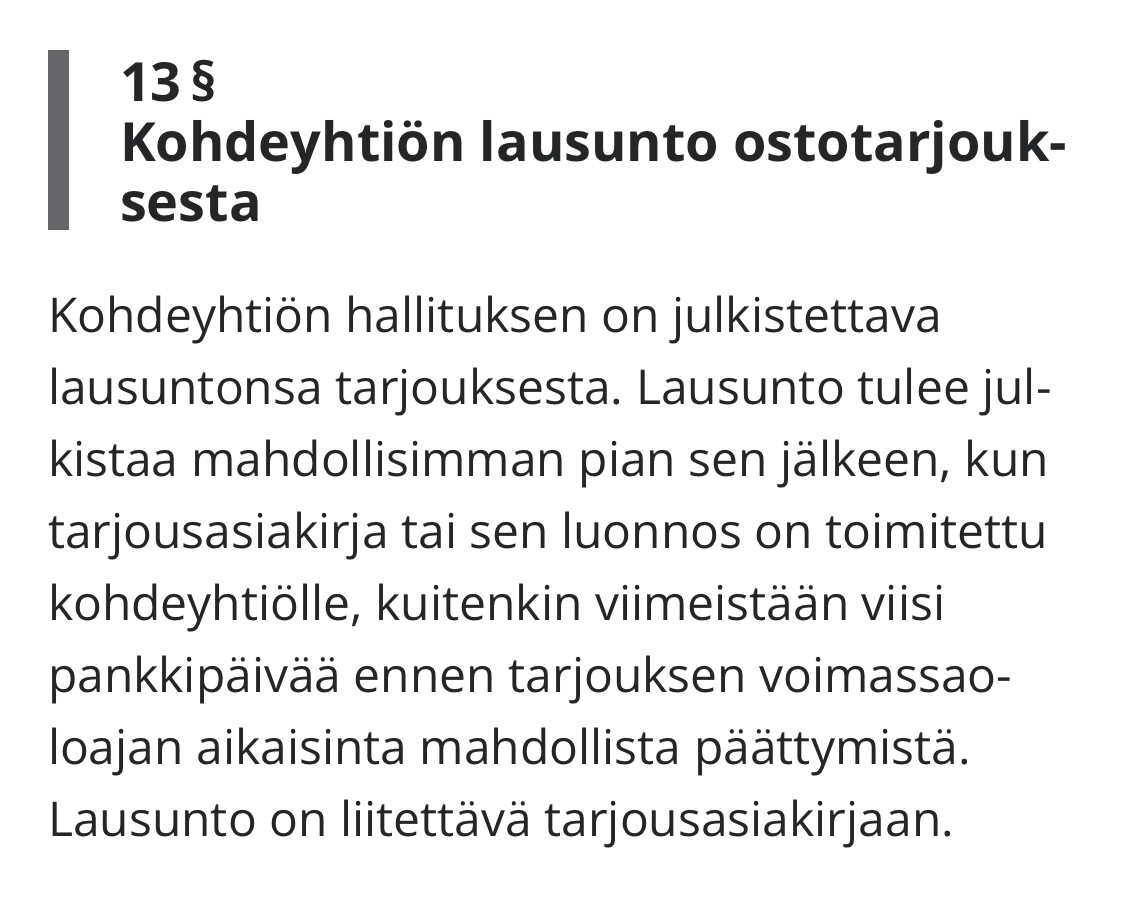
I would rather suggest looking at Chapter 11 of the Securities Markets Act and the Takeover Code, especially regarding recommendations 4 and 5. The Takeover Code in particular is easy to read, even if you don’t usually delve into legal jargon. The Takeover Code can be found here: https://www.cgfinland.fi/wp-content/uploads/2023/05/ostotarjouskoodi-2022-fin-2.pdf
17 Likes
Citycon is paying a “dividend”? Why on earth right now when there is a tender offer ongoing?
Does this reduce the €4 redemption price, or is the dividend paid on top of it?
7 Likes
Is there an arbitrage opportunity here to buy Citycon today as long as the share price is below 3.99 + (0.2 - your personal dividend taxes)? I buy the share at €3.99, receive a €0.2 dividend, and sell the share to the €4.00 tender offer?
And if so, is it expected today that the share price will jump to around the €4.15 level until that dividend is paid?
EDIT: And could the motives for such a move be the following:
A: The Catman (Kissamies) gets more liquidity. A flagship was sold at book value, and the funds are being redeployed so that more shares can be bought at 50% of book value.
B: More people might let go of their shares now if there is a roughly 5% increase in price, which is still blatantly below book value.
1 Like
There is no arbitrage. Typically for tender offers, this also includes the clause shown below. The motive here is likely that through dividend payments, G City needs less external financing for the funding requirements arising from the tender offer.
Should the Company increase the number of issued and outstanding Shares from the date hereof as a result of a new share issue, reclassification, share split or other similar arrangement, or should the Company distribute dividends or otherwise distribute funds or any other assets to its shareholders, or should the record date for any of the above be before the settlement of the completion trades (either after the expiration of the offer period or during or after a possible subsequent offer period), the Offeror reserves the right to adjust the Offer Price for the Shares and the Offer Prices for the Stock Options payable by the Offeror on a euro-for-euro basis.
12 Likes
G City corrects its tender offer for Citycon | Kauppalehti
The redemption price is €3.80, not €4.00.
6 Likes
This is ingenious. You launch a tender offer for a company under your full control at a price of 0.5 P/B → sell assets from the company at book value/or even close to it → distribute funds, which reduces the tender offer price on a 1:1 basis, and at the same time, the distribution you receive helps finance your mandatory tender offer. After such transactions, you are in a situation where you have managed to push the tender offer price down by 1.0 P/B, in a sense, even though your offer is 0.5 P/B. Quite a contradiction, then. Rinse and repeat: the larger the distribution of funds in this situation (and thus the adjustment of the offer consideration), the further the calculated offer for the remaining real estate portfolio weakens in P/B terms. In an extreme scenario, you could sell half of the real estate portfolio at book value, which would mean getting the other half for free as the offer consideration is adjusted to zero.
41 Likes
Headline quote from Arvopaperi. In my opinion, a somewhat “depressing” analysis. Hard to decide. I have enough of these shares that maybe a more certain return could be found elsewhere. One less worry. If we stay in, the “cat man” manages the company almost however he wants. Who would then buy those on the exchange at a reasonable price? Therein lies the problem. The shareholders’ only chance would be demanding a minority dividend. Not much else, well, attending the annual general meeting once a year.
A few days left to decide. Correction. There is still time until February 20th.
More than a month left, the offer period ends on February 20th.
5 Likes
Arvopaperi:
The offer period is extended until 6 March 2025 at 4:00 p.m., unless it is discontinued in accordance with the terms and conditions of the tender offer.
Due to the extended Offer Period, Citycon’s shareholders and holders of Option Rights have the opportunity to evaluate their participation in the Tender Offer also after Citycon’s 2025 financial statements have been published.
Citycon will publish its financial statement release for 2025 and its audited consolidated financial statements for the financial year ending 31 December 2025 on 26 February 2026.
“Due to the extended offer period, Citycon’s shareholders and holders of Option Rights have the opportunity to evaluate their participation in the tender offer even after Citycon’s 2025 financial statements have been published,” the release explains as the justification for the extension of the offer period.
2 Likes
That would indeed be quite an evil plan, but I don’t doubt for a second that it’s possible… Still no comment from the independent board regarding the takeover bid? Personally, I’m sitting on my hands since my shares are at book value, so these -50% offers aren’t exactly very tempting…
4 Likes
So, should this be interpreted as a disastrous result coming up, which will then motivate the rest to accept the offer? It’s hard to believe that any benevolent transparency would actually be the reason for it.
8 Likes
“Citycon’s Board of Directors will process the mandatory tender offer by members independent of the offeror and the tender offer as required by the Securities Markets Act and other applicable regulations, and expects to publish a statement on the mandatory tender offer within the coming days.”
That’s probably what’s taking so long: trying to figure out who can legally put their name on the paper and who has the nerve to write the document with a straight face.
The awkward thing here is that shareholders do not HAVE to sell their shares if G City does not reach 90% of the shares. Private investors would have a much better hand if, for example, Ilmarinen had increased its stake to 10% and publicly announced that they are not going to let the squeeze-out happen at such a low price.
3 Likes