Here are Lucas’s comments on how Björn Borg has entered into a three-year strategic partnership with Åhléns and Inno to expand its lifestyle categories in the Swedish and Belgian markets. 
Lucas has written a company preview for Björn Borg, which will publish its Q1 results on Wednesday, April 29th.
We have lowered our short-term forecasts to reflect softer end-market demand than previously expected. Although we are also taking a more cautious view in our medium-term forecasts due to weakened general consumer confidence, we leave our long-term forecasts largely unchanged. As a result, we maintain our target price of 67 SEK per share. However, the share price has risen nearly 20% since our last report, and we believe the valuation is stretched based on actual earnings. Consequently, we are lowering our recommendation to Reduce (prev. Accumulate).
And here are Lucas’s comments on BB’s Q1 result.
Björn Borg’s Q1 revenue growth was better than our expectations, which together with increased gross margins led to a strong earnings beat. In our view, we are positive about the sports apparel category continuing its double-digit growth, but there were no clear signs of a general turnaround in the footwear category yet, which we believe will be key in accelerating the company’s revenue growth in the future.
Here is the company report on Björn Borg after Q1, written by Lucas.
Björn Borg’s Q1 result exceeded our expectations, and we consider the share price reaction following the report justified. Although we have raised our short-term forecasts following the Q1 beat, our medium- and long-term forecasts remain largely unchanged. In our view, given the continued uncertainty in the business environment and the lack of clear evidence that the company can successfully scale its footwear segment, we believe the stock is already fairly priced based on its expected earnings growth (2026e P/E: 17x). As a result, we reiterate our reduce recommendation and 67 SEK:
2 Likes
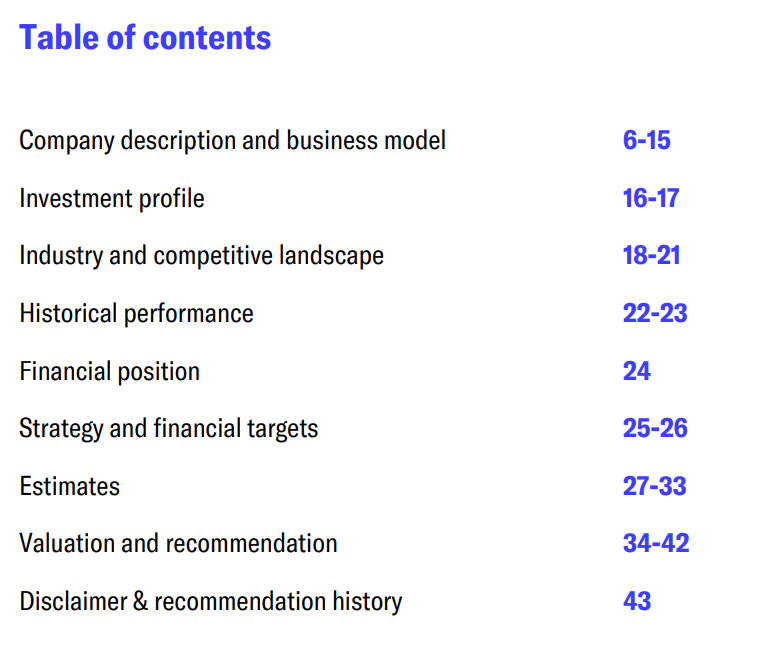
Here is an extensive report on Björn Borg written by Lucas, and like other extensive reports, it is free of a paywall. The report is in English.
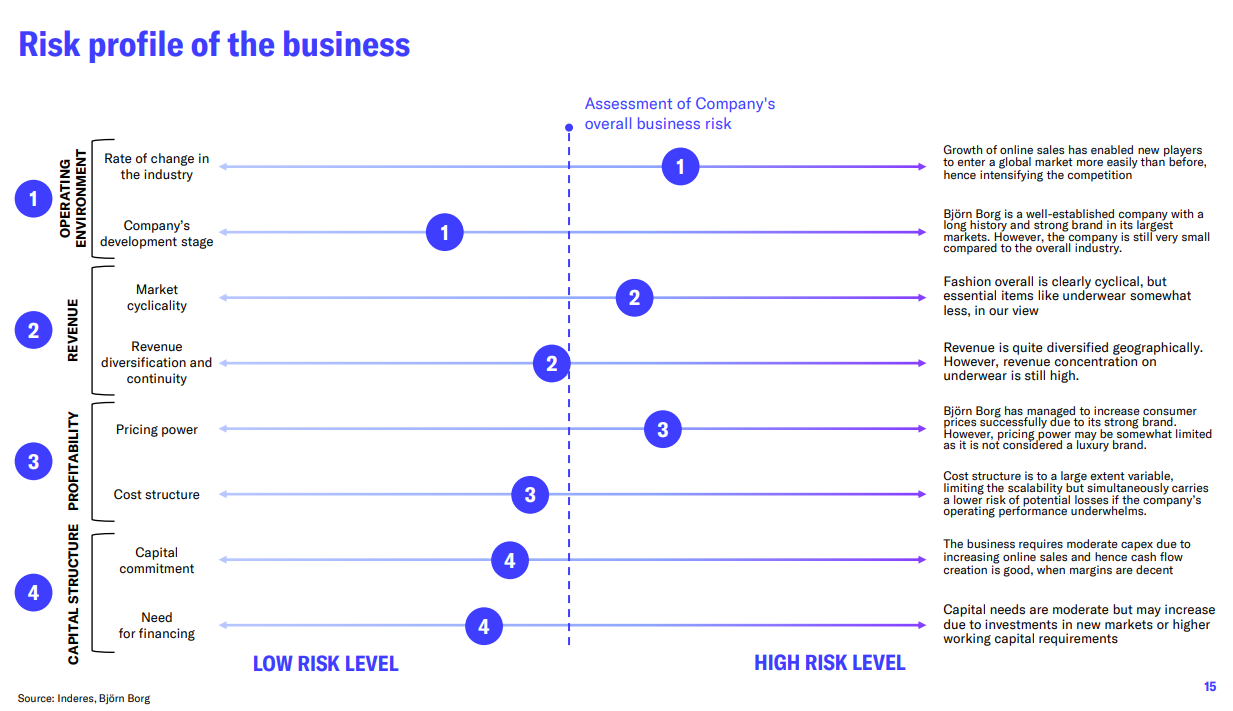
We are raising the target price for Björn Borg to SEK 69 (previously SEK 67) per share based on slightly higher long-term forecasts. In our view, Björn Borg has made good progress in executing its strategy by expanding its core product categories and its own e-commerce channel, which we expect to continue driving profitable growth. We continue to see Björn Borg as an interesting long-term investment, as the company has the ability to create solid value. Following the recent moderation in valuation (the share price has fallen by approximately 10% since our last update), we also believe the short-term return expectation has strengthened. As a result, we are upgrading our rating to “add” (previously “reduce”).
Excerpts from the report:
We expect continued good sales in 2027-2029 as the general economic situation improves and demand for sportswear remains strong, while underwear is expected to show moderate growth. We expect the growth of the footwear category to be higher than the group average, given our assumption of a successful integration of the distribution. Geographically, we estimate that growth will be driven more by markets outside the Nordic region, such as Germany. Overall, we expect an average annual growth rate of around 7% in 2027-2029.

2 Likes
Here are Lucas’s pre-release comments ahead of Björn Borg’s Q2 results next Friday
We expect the company’s revenue to grow steadily, driven primarily by the sportswear category and its own e-commerce store, while the underwear segment is normalizing after a strong Q1. We forecast profitability to improve year-on-year, supported by higher sales volumes and a favorable channel mix.
1 Like
Here are Lucas’s comments on Björn Borg’s Q2 results 
1 Like
Here is the company report on Björn Borg regarding Q2 from Lucas
Although Björn Borg’s Q2 report fell short of our expectations and our near-term forecasts have decreased slightly as a result, it does not have a material impact on our medium- to long-term forecasts. While we are monitoring the wholesale segment, which has been a drag during H1, we continue to see good opportunities for the company to get back on track and generate profitable growth and solid value creation. As a result, we still consider Björn Borg an interesting investment, given the attractive combination of expected earnings growth and dividend yield, and therefore reiterate our “Buy” (Lisää) rating and our target price of SEK 69 per share.
1 Like