Ambu - Revenio of Endoscopic Devices

Danish company Ambu is the world’s leading manufacturer of single-use endoscopes. Traditionally, gastrointestinal and urological endoscopies have been performed with reusable devices that are washed between uses. Ambu, on the other hand, has launched a single-use alternative that is more cost-effective and hygienic.

The market for single-use endoscopes is currently around USD 500 million per year and is expected to grow to USD 2.5 billion by 2024 as single-use devices gain market share from reusable ones. In this sense, the company has many similarities with the highly interesting Revenio, which also benefits from a situation where a better technical solution displaces an older one.

Much like in the case of Revenio, there were news that competing measurement technology had caused coronavirus infections. Similarly, there have been concerns about the risk of infection with reusable endoscopes. The coronavirus crisis has indeed accelerated the demand for Ambu’s endoscopes even more rapidly.

Currently, there is practically one significant competitor in the market, the American company Boston Scientific. The market is so large that there is room for both, and Handelsbanken, at least, estimates that competition is primarily good as it accelerates the development of the entire market and the shift to single-use products.

Ambu also has two other business areas (Anesthesia and Patient Monitoring), but the most interesting segment is the visualization segment, which manufactures single-use endoscopes. Ambu’s other segments have suffered somewhat from the coronavirus crisis as non-urgent surgeries have been postponed. In the long run, these are also in growing industries.

The company has a somewhat unusual fiscal year ending in September. For the next fiscal year 2020/21, revenue growth is expected to be 16%, but accelerating thereafter to 24% in the 21/22 fiscal year. For the fiscal year 20/21, EV/sales is 11.6x and EV/EBITDA is 63.2x.

The stock’s valuation multiples are therefore high, but the outlook is very attractive. The share price at the time of writing is DKK 193.5.

More information and the company’s presentation can be found here:

35 Likes

Interesting tip. The very Revenio-like acceleration might be behind us already, but the outlook seems promising. Based on a quick look, North America is lagging behind in utilizing this technology, or they are using Boston Scientific’s offerings. In any case, that market for these solutions is certainly considerable. A small batch acquired, we will monitor the situation’s development.

2 Likes

Just a quick comment before I build a longer one and start looking into the company. In the medical field, in hospitals and ambulances, “ambu” is commonly known as a resuscitator bag. :slight_smile: The term “ambu” = resuscitator bag. It doesn’t matter if it was made by a competitor or not, people always said and still say, for example, “Give me the ambu” or something similar. :slight_smile: So there’s no lack of recognition, at least.
3 Likes

At the beginning of the coronavirus crisis, the sales of these bellows also jumped, and MIT researchers even developed an improvised ventilator from them.

However, the surge was temporary, and the demand for bellows under normal conditions is very stable.

Interesting company. However, the Q3/20 report was quite bad(?) and the share price reacted from 220 to 190. Has anyone looked into the reason? I haven’t had time to read the report in detail yet, other than skimming the numbers.

In connection with the Q3 earnings release*, the full-year guidance was narrowed to the lower end of the previously given range. Revenue growth is expected to be ~26% (previously: 26-30%) and the EBIT margin ~12.5% (previously 12-14%).

*Note: the financial year ends on September 30

3 Likes

This would fit perfectly into my portfolio in terms of industry diversification! I tried to dig into how the market for single-use devices is divided. Boston Scientific is a big competitor, but who else is active in the market, and are there competitive factors leaning one way or another? Ambu seems to have quite a few new device launches coming up.

Last week, Ambu announced that its single-use cystoscope had received regulatory approval for the European market. This is one of the 12 devices that Ambu has promised to bring to market by 2022.

Tomorrow, the quarterly report will be released. The impact of the coronavirus brings a lot of uncertainty to this quarter’s figures.

1 Like

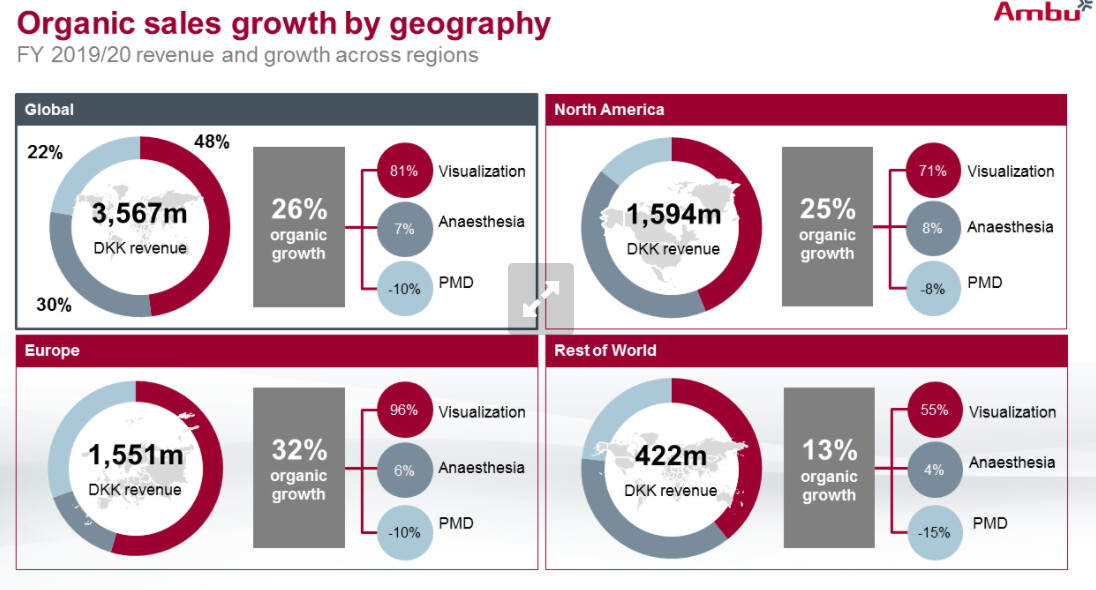
Today, the Q4 interim report for FY2019/20 was released. The endoscope business grew by 81% and accounted for 48% of the company’s revenue during the fiscal year.

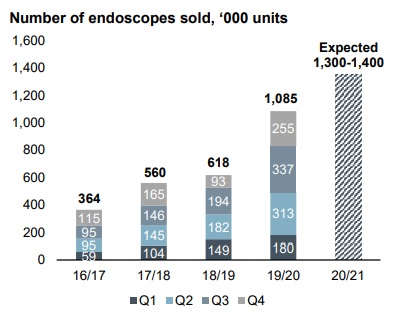
Growth is expected to continue at a good level. In terms of units, 1.085 million endoscopes were sold, and sales of 1.3-1.4 million units are guided for the next fiscal year.

The biggest disappointment was definitely the profitability guidance, which is expected to remain at the level of the past fiscal year or decrease (EBIT margin 11-12%).

4 Likes

Elisa’s share price reaction was significantly negative, and I added it to my portfolio during the day when the price was around -6% (approx. DKK 190), because in my opinion, nothing in the outlook has fundamentally worsened compared to before. The demand outlook for products in the market is developing favorably, the company’s growth continues strongly and requires investments, so it is clear that this will reflect on the development of relative profitability.

Today, it’s sailing at +6% (approx. DKK 210) on a daily basis, meaning it returned to the level before yesterday. What’s behind it, I haven’t come across any new news yet. One cannot always understand market reactions.

What’s been moving Ambu for some time now? It’s hovering around 260 DKK but I can’t find anything new in the English announcements, at least.

Ambu’s results will be out tomorrow. The valuation level is certainly dizzying. With the numbers for the 2021E financial year ending in September, the EV/EBITDA is 89.4x. If there is a disappointment tomorrow, the drop could be significant.

1 Like

Any thoughts on Ambu’s volatility today and perhaps the company itself…?

Q3 was released a few days ago: Investor Relations

Still seems expensive. Growth has stumbled a bit this year. It would be interesting to know more precisely why, and whether the problems are temporary.

1 Like

Salkunrakentaja has an article about this:

The article refers to Handelsbanken’s analysis.

1 Like

Since the thread has been dead for years, I dare to ask silly questions even with shaky knowledge. Has anyone more knowledgeable followed the endoscopy market in recent years? What does the competitive situation look like now that healthcare has returned to normal times? When I looked at the interim reports, tariffs and currencies have caused headwinds. Growth has also slowed down, but is the situation as bad as the stock price suggests, 5y -75%? In their own opinion, the products are of course very advanced, like everyone else’s, yet they only forecast 10-13% organic growth for this year.

3 Likes

However, even this company made its biggest profit ever in 2025 (it probably increased by about 2.5 times from 2024), and revenue is growing very predictably (year after year). I think the decline experienced in the stock is just a correction of the high valuation of previous years. The P/E ratio, however, used to hover around 200-300 for a long time. Now it has come down to more reasonable levels. Below is the P/E ratio history from Tradingeconomics.

3 Likes

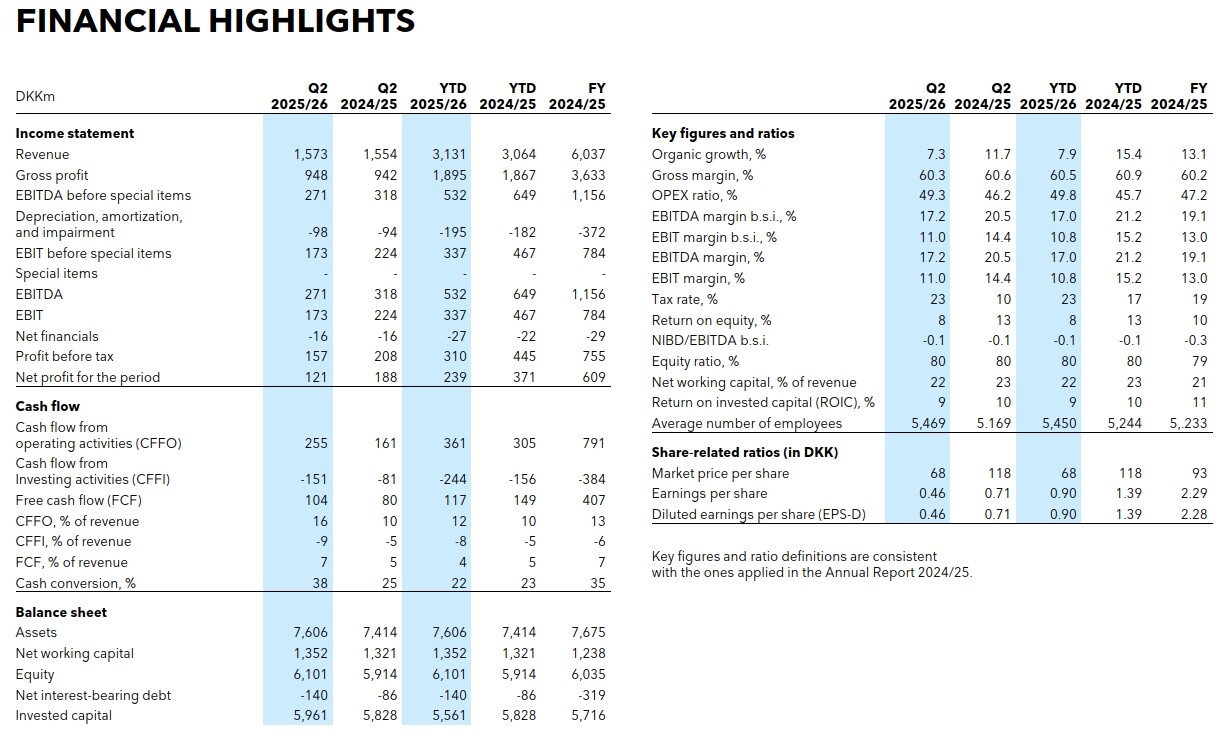
The markets didn’t like it; down nearly -5% today. Revenue growth slowed and operating profit decreased—pretty sluggish figures. I considered buying several times, but luckily I didn’t hit the buy button. Their performance isn’t convincing when, according to them, there should be a large market for single-use products, yet sales aren’t gaining traction.

2 Likes