I went through Aallon Group with Ate on video. I didn’t ask too many difficult questions, but I did raise a few question marks.
https://www.inderes.fi/fi/videot/aallon-group-houkutteleva-arvostus-kompensoi-riskeja
I went through Aallon Group with Ate on video. I didn’t ask too many difficult questions, but I did raise a few question marks.
https://www.inderes.fi/fi/videot/aallon-group-houkutteleva-arvostus-kompensoi-riskeja
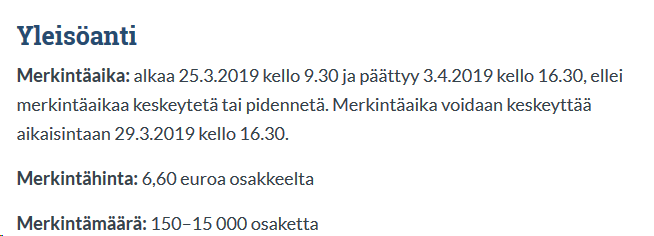
How does that valuation work, when Inderes has set the fair value at 21 million euros? It is now being offered at 17 million euros, where the share price is 6.60 euros.
Currently, they own 2.6 million shares and are not selling.
New shares in the public offering: 140,000 shares. To staff: 200,000 shares, and to institutional investors: 460,000 shares, totaling 800,000 new shares.
Total shares: 3,400,000.
With a 17 million euro valuation, the price per share is 5 euros/share.
With Inderes’ estimated valuation of 21 million euros, it is 6.18 euros/share.
The offer price is thus 6.60 euros/share.
Are these calculations correct and relevant information, and if so, should they be better explained and clarify why 6.60 euros is a reasonable price to buy? The starting price of 6.60 euros has 42 cents, or 6.8%, of expectations baked into it.
Our valuation’s fair value of EUR 21 million is an estimate of the company’s value before the share issue. Currently, the company has 2.6 million shares, meaning the company’s market value before the share issue is EUR 17.16 million at a share price of EUR 6.6.
We will only take into account the funds raised from the offering and the increasing number of shares if and when the offering is realized. So, if you already want to calculate the company’s market value after the IPO, you should add the net funds raised from the offering (approximately EUR 4.3-5.3 million) to our estimated share capital value of EUR 21 million, depending on whether the additional 150,000 shares mentioned in the terms of the offering are also offered.
Therefore, Inderes’ valuation at fair value before the share issue is €21 million / 2.6 million shares, or €8.08 per share.
After the issue, the market value dilutes to €21 + €4.3 million, or €25.3 million / 3.4 million shares, which is €7.44 per share. Reason: 800,000 shares bring an additional value of €4.3 million, or €5.375 per share.
The question still is: should the analyses more clearly show the (per-share) market value after the share issue, specifically with the new planned number of shares?
Can anyone tell me why the “download report” button in Ate’s link doesn’t work on my phone? My internet connection is fine, and it’s not a Premium publication, is it?
Inderes’ estimate of fair value is €21M (20-23.7) and Aalto’s listing price is €17.2M (market value). The company currently has 2,600,000 shares due to its new organizational structure. In the issue, the Company receives cash in exchange for shares, so ownership is not diluted (unless one considers the company to be more valuable than €6.60 per share).  <–This applies to old shareholders, not us. A maximum of 800,000 new shares are offered in the public, institutional, and personnel offerings.
It worked for me at least and @lullaby
Additional Share Tranche: If the IPO is oversubscribed, the Company’s Board of Directors has the right to increase the number of shares offered by a maximum of 150,000 new Company shares.
Juu`u 950 000 shares, so with that, the company gets net assets of 5.3 million euros and can go shopping for other companies. In these markets, however, there are already enough buyers…
When I went to the page via Google, it worked, but not via the link posted in the thread, even though I tried about ten times. Mysterious… well, the main thing is that I can read it one way or another.
Aallon had 210 employees at the end of 2018. The revenue was (pro forma) EUR 15.4 million. 15,400,000/210 = EUR 73,333. Even for an auditor, it won’t be over EUR 80,000…
Why is the revenue per person over EUR 80,000 in the report?
The figures can also be found in the brochure and are calculated using the average number of personnel for the financial year.
That’s why it’s worth calculating it that way if you want the smartest number…
I couldn’t find it, though. Could you provide the page? It’s always pretty easy to find it in Talenom’s quarterly reports, but I couldn’t find yours or the company’s prospectus with any smart search term.
“To enable growth, the company strengthened its group management and organization in late 2018 and early 2019, and the costs incurred have not yet fully reflected in the 2018 results.”
How many highly paid individuals have been hired, and what do you anticipate their impact on the 2019 results will be? How many accountants have been recruited, and how many of those expensive individuals?
It’s really difficult to distinguish the total amount of those costs from the diagram; the trend seems to be upward.
Personnel costs account for over 60 percent of expenses, so I’d be interested to know more.
The average number of employees has not been explicitly stated in the prospectus, but if calculated from the employee/year figure, the rounded average number of employees during the fiscal year has developed as follows:
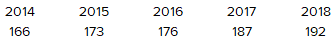
Comparing the average figure to the year-end 2018 figure (210), it is evident that a relatively high number of new employees were recruited towards the end of the year.
Personnel costs for 2018 were approximately EUR 9.6 million. This includes EUR 0.3 million in one-off project-related personnel costs, which were reflected as an equal positive amount in other operating income. In our forecast model, personnel costs are expected to grow to approximately EUR 10.2 million this year. In other words, adjusted for that one-off project, we expect operational personnel costs to increase by approximately EUR 0.9 million this year. In my opinion, this already includes a buffer for management team growth and recruitment of new accountants.
This thread has gained a lot of participants, so let’s have a weekend poll.
I’m voting for “I don’t know yet.” Maybe I’ll be wiser after the public event. I’m concerned about the new group structure highlighted in Inderes’ analysis. I’d be interested to hear from the management about their vision for future group-level operations. What will be done at the group level, what will be left to be done regionally, etc.? How will the operating methods and decision-making of six different and traditional companies be combined? A big undertaking, but one would think it has already been considered. The second point is that if the future strategy relies heavily on acquisitions, there doesn’t seem to be any evidence of expertise in these and in integrations. I suspect that success in these requires more than just money and listed shares as exchange instruments.
In a way, I’m critical, but on the other hand, I’d still like to like it.
Signed, Undecided
I’d be interested in an assessment of other potential accounting firm IPOs. What about potential candidates from the group of Aallon, Azets, or similar firms?
It can be difficult to compare these private equity-owned entities with this one, given their current financial figures.
However, I would have hoped for a slightly better peer group, as currently, the only relevant comparison there is Talenom, and the others can be skipped. Sometimes you’ve sought peer support from abroad, but not this time?
It would be preferable to have a good peer group for Aalto, but relevant peers are hard to find even abroad. Juha has written about the same topic in Talenom’s comprehensive report. Fortnox is available in Sweden, but it profiles itself more as a software company, and its valuation multiples are consequently in a completely different realm.
In Aalto’s case, the valuation multiples are absolutely low at the listing price, so I think it’s positive that the valuation doesn’t even need to rely on the multiples of peer companies.
True, this can be evaluated without a control group. I just felt like face-palming when I saw that the comparables included IT consulting, an advertising agency, and other things…