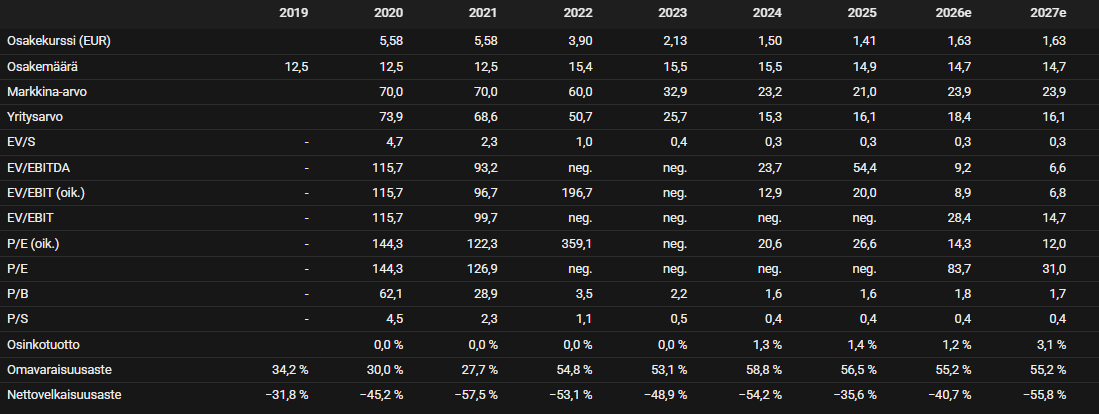
According to Witted, the outlook still appears to be heading in a positive direction, looking at macro factors and client demand. We no longer really need to wait for a turnaround, but rather the turnaround is underway – and perhaps people are just waiting for it to continue. The company has grown quite briskly in previous years, so chasing higher growth is not necessary, nor is it the main role.
The company may have missed expectations (Q2), but missing expectations doesn’t mean that the company’s performance has been poor – even a bad company can beat expectations by going bankrupt later than expected, for example. Profitability has taken brisk steps forward, and the company will likely push ahead organically.
Witted’s profitability has improved thanks to efficiency measures and better margins, not because of any shady tricks. Software Sauna is operating profitably and will likely increase its role, which will be reflected more clearly in the company’s figures going forward. Norway is also doing better than before, and as I understand it, the entire company now operates more sensibly. So the turnaround appears to be underway. Witted is still considered riskier than its competitors and is valued significantly cheaper, which may limit the downside. Based on my impressions and what I’ve read, looking to the future, Witted might get a value driver from artificial intelligence, while some more “boomer” types use a value calculator. Witted isn’t a big deal in the public sector (cough… well, except it won the Yle contract)  and pent-up demand is being released in the private sector.
I’ve been thinking myself, and recall reading, that the sector might polarize into outperformers and withering companies, and I think Witted is on the side of the outperformers—some will fall behind while others strengthen at the same time.
The turnaround is of course at an early stage and not yet “confirmed,” so macroeconomic cycles have a moderate impact on a company in a delicate state. In addition, the company still needs a little time to prove that the turnaround won’t stall. Consulting work doesn’t sound all that glamorous in the long run, and we must remember that investors may still be overly pessimistic about the company, which could be reflected in the valuation for longer, even if the company might otherwise deserve a better valuation. Shorter-term market pessimism certainly offers a buying opportunity, but if that attitude becomes chronic until the next problems hit, you can’t rejoice over cheap buying opportunities… well, that was a lazy take too. 
What would be the clearest signs to you that Witted can maintain its improved profitability and momentum over the longer term as well? How do you believe the company will perform relative to its Finnish competitors? 
Thanks in advance for your well-reasoned thoughts!


 Revenue EUR 4.4M (forecast the same) and number of consultants 341 (forecast 342)