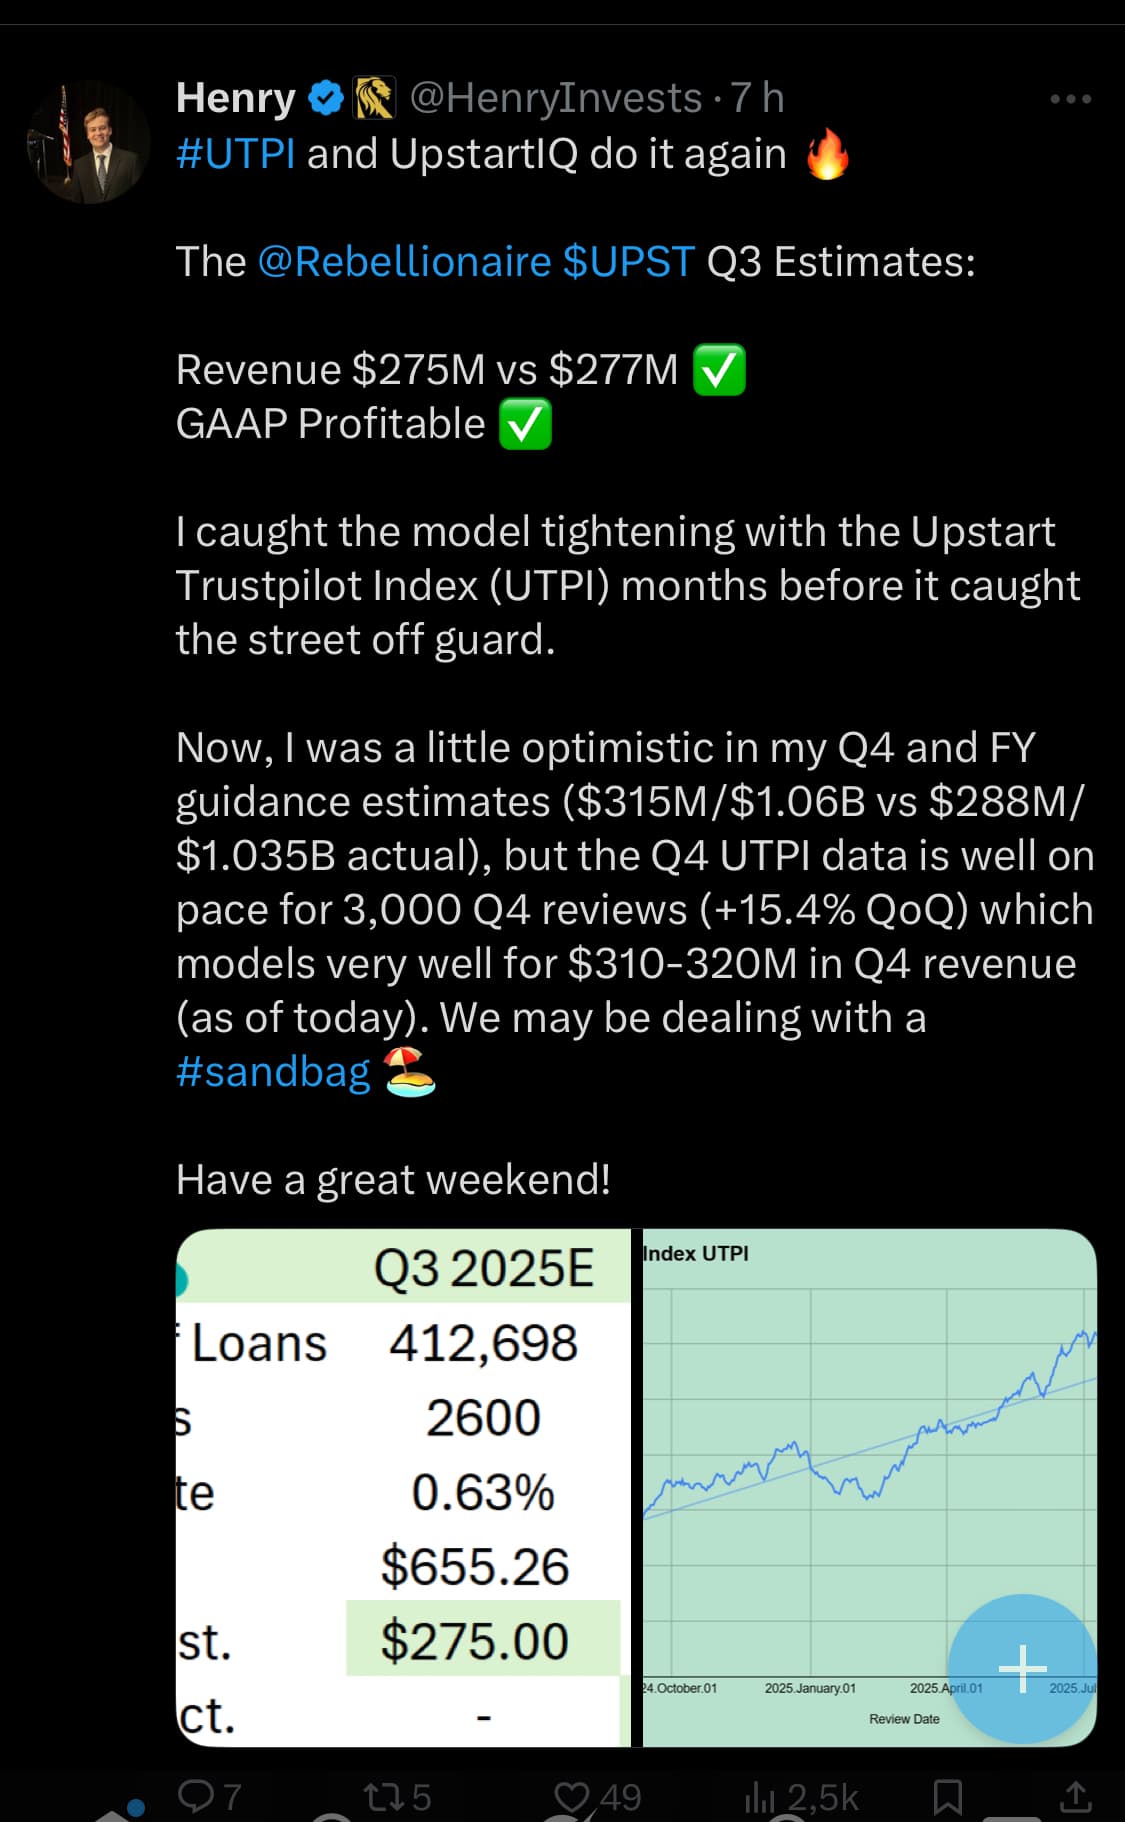
By the way, you should follow HenryInvest on X if you’re interested in Upstart. Really good insights that help understand where the company stands. No hype, but well-argued stock research.
4 Likes
https://x.com/davegirouard/status/1986854533981708508?s=46
Even though I’ve been disappointed by the empty promises of the management of a certain unnamed Voxtur, this somehow still resonated. Let’s hang in there!
I was once interested in this company too and thought it could replace banks and be a part of it. New AI and a so-called way of operating.. but…
The number of shares is constantly growing rapidly, because management is rewarded with new shares. Which dilutes other investors’ ownership.
One can still somewhat understand this, but when management is constantly selling shares at a high premium, I think it’s a bad signal. Because of this, I sold my holdings a year ago.
A lot of volatility in the stock price and I was left a bit unclear about the company’s product or what makes it the best, its competitive advantage?
Banks themselves can utilize almost free AI for scoring and their own customer data.
Does Upstart have some better customer data or a classification formula? Than current banks.
If there is a smarter concept, then normal banks would be sidelined and there would be a brilliant future?
2 Likes
If I understood this correctly, they’ve finally been buying there.
2 Likes
UPST is constantly trying to develop that better understanding of the customer base. And at the same time, software suitable for the process is being developed so that the entire process (applying for credit, granting it, acquisition, etc.) would be as efficient as possible. Time will tell…
1 Like
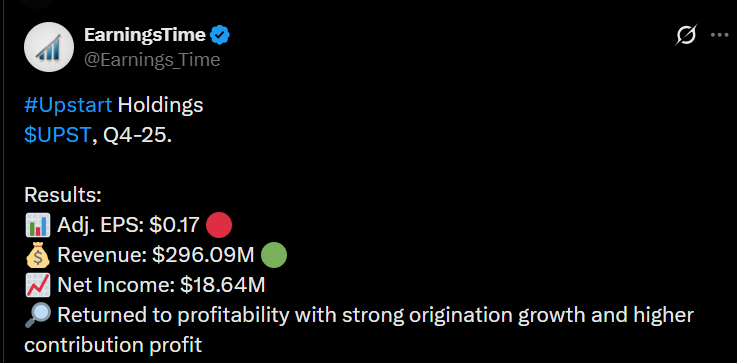
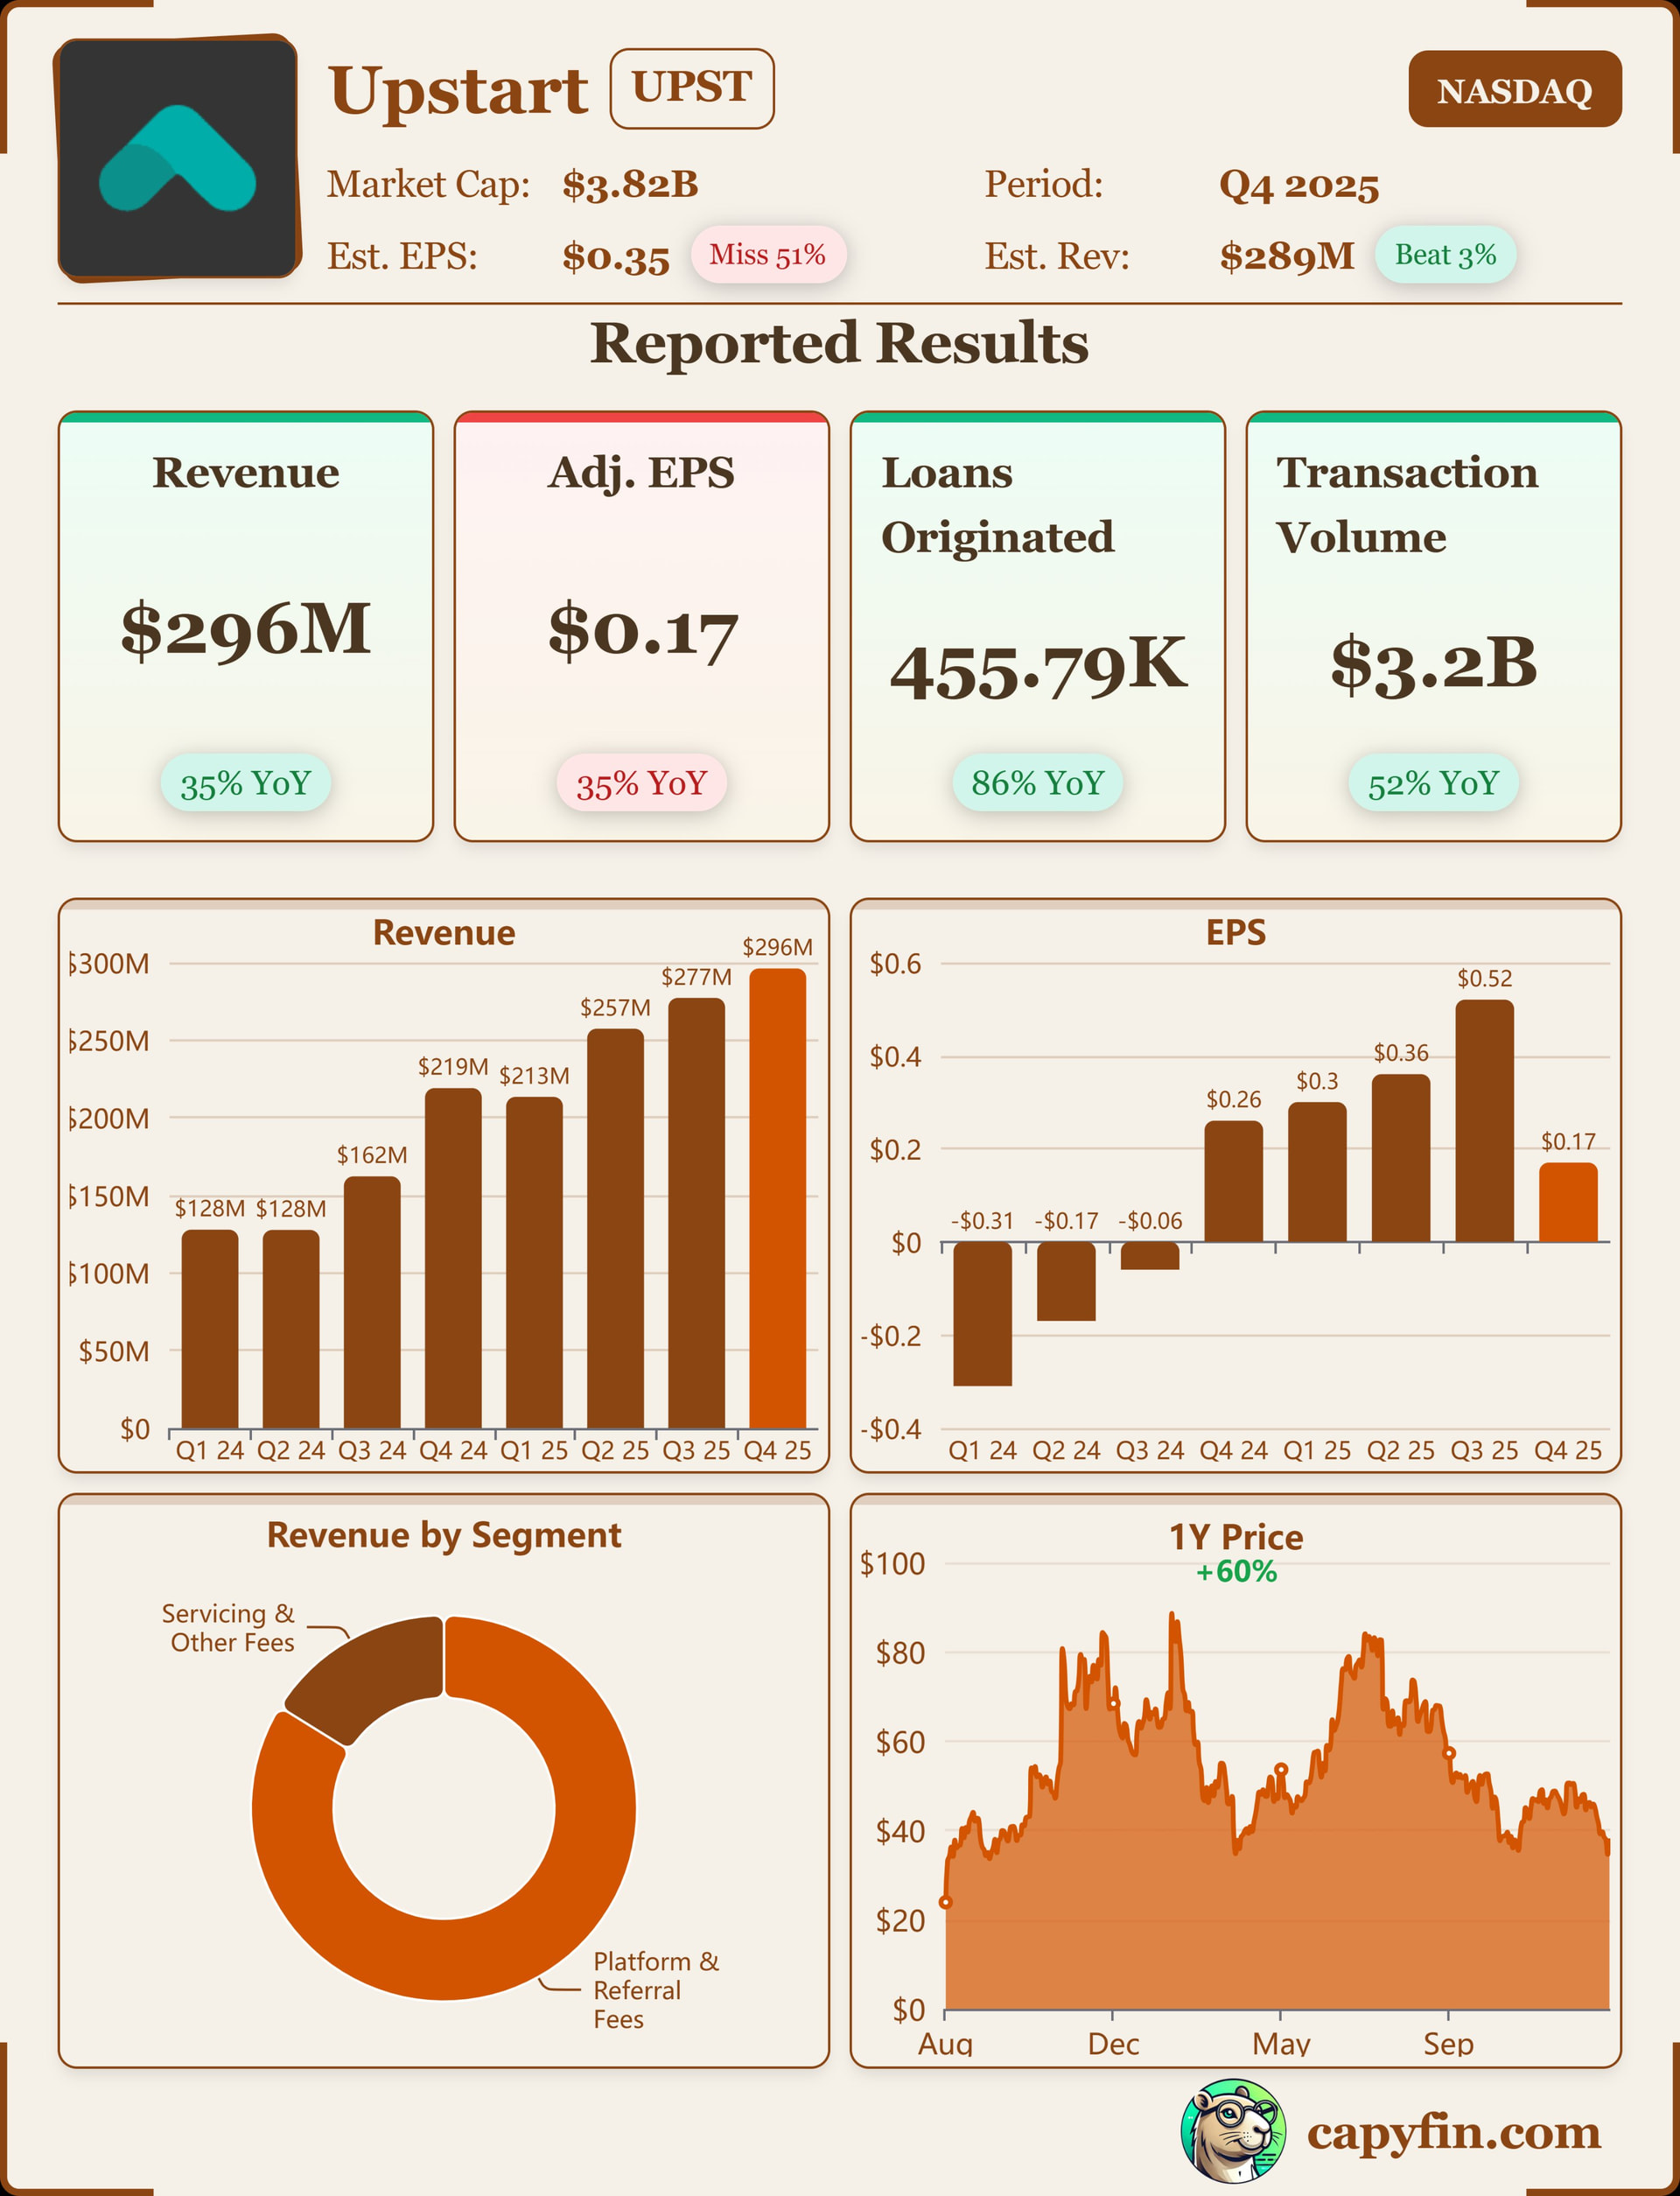
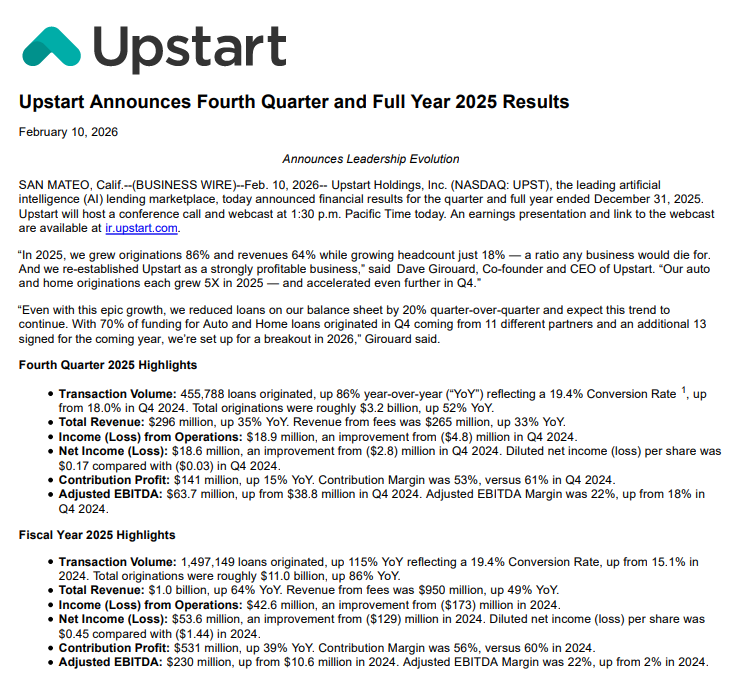
The company’s end of the year went quite well, and growth expectations were significantly exceeded.
Earnings turned positive, and significantly more loans were issued than before, aided by AI; in addition, the future outlook also appears strong. Winds of change are blowing at the company in other ways as well, as management will change in the spring and reporting will be made clearer. Going forward, the company will focus even more strongly on long-term goals and more transparent communication than before.
https://x.com/Earnings_Time/status/2021341048501637566
Company’s own materials
5 Likes
And the guidance is quite ambitious:
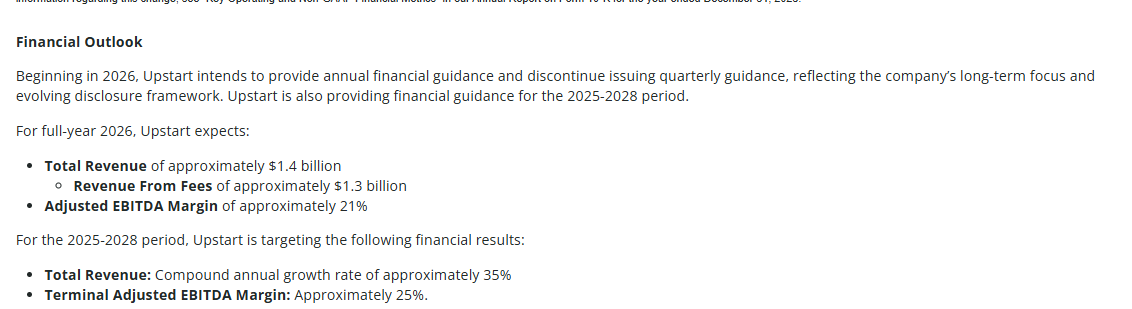
revenue of $1.4 billion for 2026 (well above analysts’ expectations of 1.27 billion), and a long-term growth forecast of 35% CAGR until 2028.
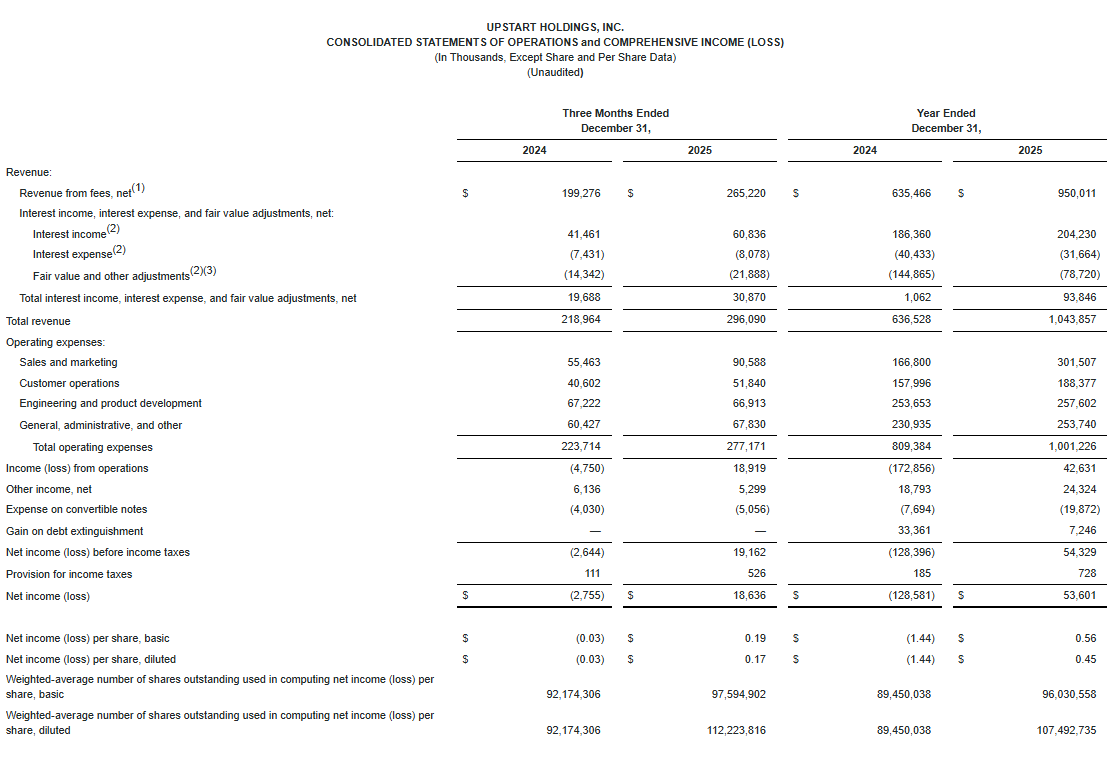
”WASHINGTON (dpa-AFX) - Upstart Holdings, Inc. (UPST) on Tuesday reported fourth-quarter net income of $18.6 million or $0.17 per share, compared to a net loss of $2.8 million or $0.03 per share last year.
Revenues for the quarter were $296.1 million, compared to $219.0 million last year.
For the full-year 2026, Upstart expects revenue of approximately $1.4 billion and an adjusted EBITDA margin of approximately 21%.
For the 2025-2028 period, Upstart is targeting a total revenue growth rate of approximately 35% and a terminal adjusted EBITDA margin of approximately 25%.
3 Likes
In addition to the previous ones, a few of my own observations and some picked up from X:
- Growth is increasingly focused on lower-margin auto and HELOC (Home Equity Line of Credit) loans. To reach the revenue growth guidance for the next three years (35% CAGR), funding partners must be acquired at an accelerating pace. In Q4, 30% of auto and HELOC loans were funded via Upstart’s balance sheet. I.e., 100% confidence in these products has not yet been established among funders.
- Margins on auto and HELOC loans could improve as confidence in Upstart’s underwriting grows.
- Fixed costs grew only 11% Y/Y in Q4, even though loan volume increased by 52%.
- Sales and marketing expenses grew 63.5% and were approximately 30% of revenue, compared to 25% of revenue in Q4 a year ago. This explains why net income decreased compared to Q3.
- Loans were sold from the balance sheet at a small loss of $13.7M. The loan portfolio on Upstart’s own balance sheet decreased by approximately $250M, or 20%.
- 2026 guidance regarding growth is bueno, but adj. EBITDA % is estimated to decrease from 22% to 21%.
- Going forward, Upstart will report loan volume development on a monthly basis.
- Upstart’s UMI indicator is on a downward trend, signaling an improving macroeconomy and financial conditions.
3 Likes
Upstart is progressing a bit bumpily. A few highlights from the earnings slides:
Upstart’s stock market journey, which started well, went into a slide in 2021 when financial institutions tightened funding and UPST was forced to act as a bank itself. This was rightly poison for the market; UPST is an AI company at its roots. In the past quarter, UPST reduced its role as a lender by 300 million; this is the right direction.

The company’s management promises strong 35%/year growth:
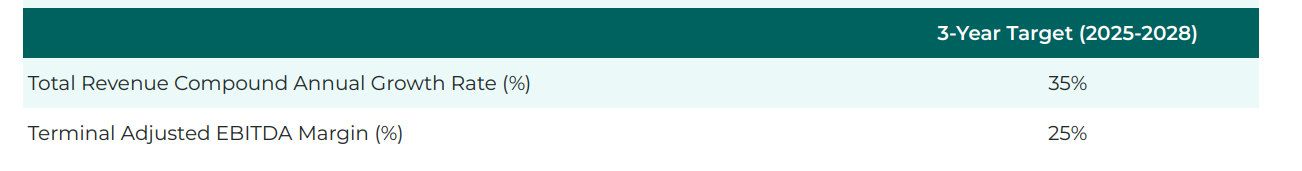
In my view, this is clearly an aspiration, but performance is growing towards it; below are some significant growth figures for different loan types:
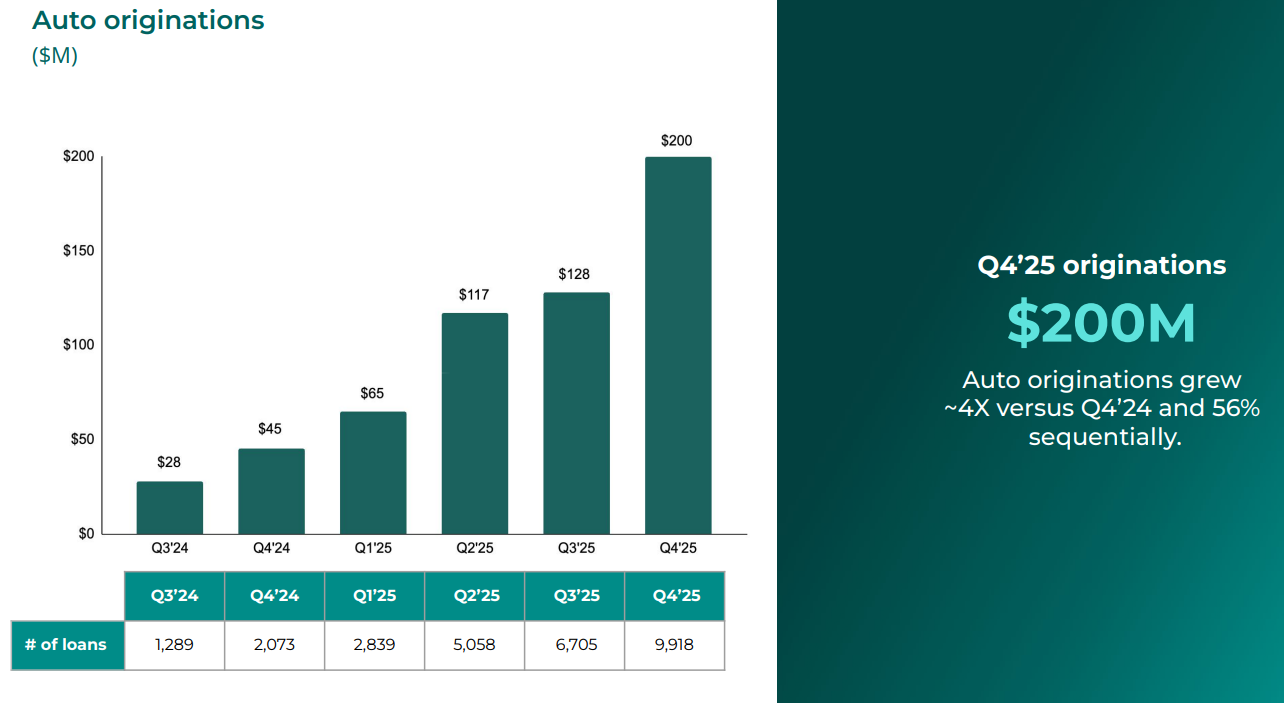
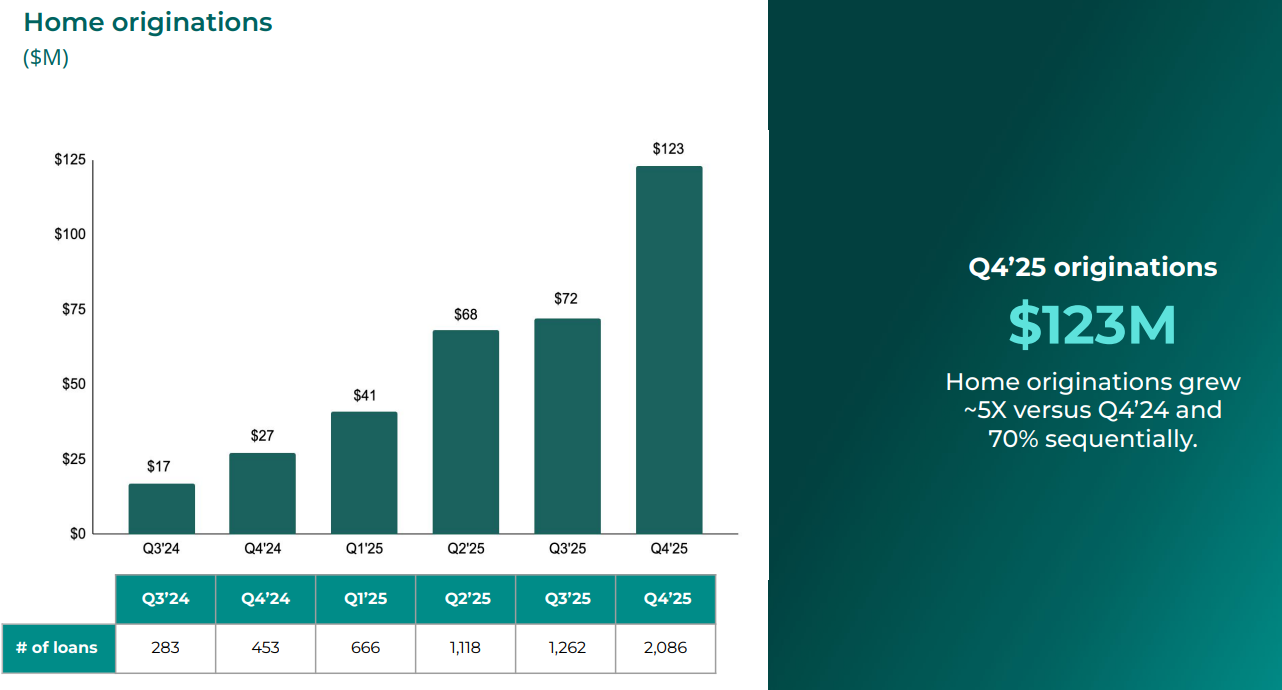
So UPST has started to “attack”—the macro environment is okay enough for that. The attack is being executed by increasing marketing expenses, as @Float noted above regarding the growth in marketing costs. But since cash flow and profit have turned positive, the growth in marketing is fine. UPST is likely balancing margins because the desire for growth is strong and there is potential for growth in at least the aforementioned loan types.
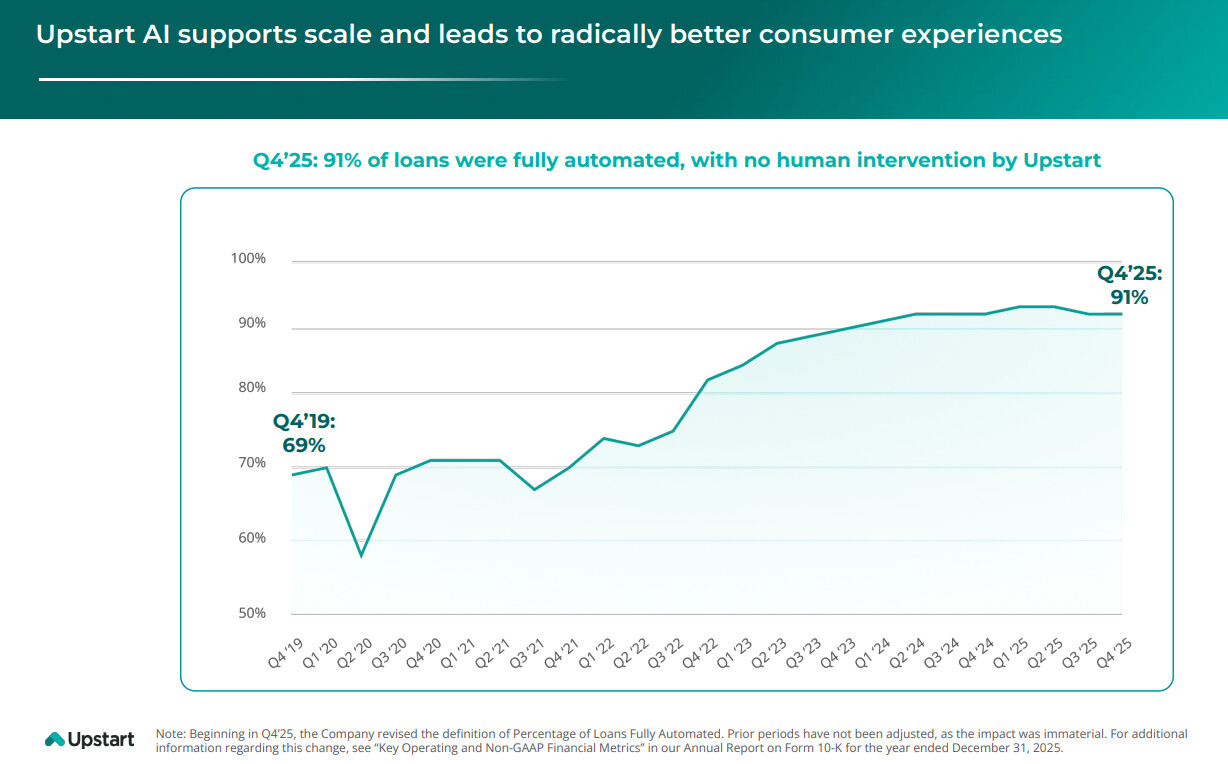
UPST is an automator of the loan market. This is illustrated by the following image, which shows a good direction:
4 Likes
To correct myself slightly: According to management comments, UPST has not taken the full take rate on auto and HELOC loans, but has instead left a portion of it for customers—i.e., customers have received loans at a lower interest rate. For this reason, EBITDA is guided to decrease by 1 percentage point compared to 2025. The strategy is to properly capture the market now and play the long game. According to management, the 2028 EBITDA guidance of 25% can be significantly exceeded. In other words, they are prepared to trim margins even in the long term.
Part of the reason for the share price decline, besides poor sentiment, is doubt regarding the sufficiency of funding/funding partners, which is considered a bottleneck for growth. UPST appointed its former CFO as Chief Capital Officer, whose role consists solely of recruiting funding partners.
I personally like the company’s direction and believe it belongs among the winners in the fintech sector. I understand, of course, that the valuation based on this year’s earnings is tight, given the macro uncertainties and funding sufficiency. However, I am betting that the Fed will cut interest rates at least a few times this year, which will play into UPST’s hands.
For your information, direct peer Pagaya announced that they are starting to pull back on growth this year because funding partners are somewhat concerned about macro uncertainty. My understanding is that they do not have such advanced AI in underwriting, which is why they have to make major lending policy decisions manually. UPST relies 100% on AI, which, for example, slowed down lending in Q3.
3 Likes
https://ir.upstart.com/news-releases/news-release-details/upstart-repurchases-100-million-shares/
Repurchased shares for 100 million. 122 million still left in the buyback program.
3 Likes
Financing arrangements for auto loans.
4 Likes
Cleaning up the balance sheet. Building for the future. And the market imagines that Anthropic will come and blow all SaaS companies—and this AI company too—out of the water. This is just how the stock market is sometimes.
3 Likes
Upstart has secured a $1 billion agreement with Eltura Capital Management and Aperture Investors for consumer loan financing.
Upstart is reportedly strengthening its funding base and automated lending operations through the agreement. The partnership also deepens the relationship between the parties and supports Upstart’s goal of diversifying the secondary markets for its loans.
The 12-month agreement involves Eltura Capital Management, an alternative investment manager focusing on asset-based finance, and Aperture Investors, an alternative asset manager that is part of Generali Investments. The arrangement represents the first forward-flow agreement of this scale between Upstart and the investor group.
5 Likes
Upstart stock rose as the company reached an agreement with Neuberger Specialty Finance to continue their partnership.
Neuberger commits to purchasing $600 million worth of consumer loans originated on Upstart’s AI-based platform. The agreement strengthens Upstart’s funding base and further helps provide more affordable loans to consumers.
3 Likes
Results are out, and we saw strong growth. However, full-year guidance was lowered.
What does @karhulalainen say?
1 Like
The investor presentation slides look good, and I would have dropped a few images here, but there was a technical glitch, so here are just my verbal observations. The company is on a steady, solid growth trajectory. Contribution profit is continuously improving, and margins are expanding. GAAP net income has already been achieved across multiple quarters. The investor slides show that Upstart’s core rationale works: AI improves credit targeting, providing lenders with better accuracy than traditional models. This has, of course, been quite obvious all along.
The macro environment is likely weighing on UPST’s valuation as well. It feels like the stock price and the company’s performance barely correlate. I suspect the relatively large net debt is dragging down the valuation, meaning the market isn’t willing to grant high multiples. In my view, the company is certainly not in any acute crisis. And it has shifted toward generating cash rather than burning it.
In short, this is a company whose AI innovation actually works. The growth rates are decent. However, in the current macroeconomic climate, the company gets lost in the crowd and doesn’t seem to be getting the somewhat higher AI-company valuation premium it deserves.
4 Likes