Shopify performed quite well; revenue grew significantly and commerce on its platforms picked up.
Management emphasized that they are focusing on developing services and accelerating + assisting the success of various players, from small entrepreneurs to large brands (win-win).
Growth and profitability were at a good level, which also builds confidence for the future.
Datadog grew strongly; revenue exceeded expectations, the customer base expanded, and overall user numbers increased. Order backlog and billing grew significantly, and the company raised its full-year outlook.
Profitability softened slightly, but earnings per share were clearly better than anticipated. Costs remain under control, investment in product development continues, and the market still interprets the direction as strong.
Here is a tweet about ServiceNow, which some consider a bit dull and gray; the tweeter has highlighted the company’s sharply fallen stock price, but also the fact that the company’s figures are otherwise strong, and AI does not seem to be unsettling the company, and he has emphasized the company’s stable performance.
Shopify laid off a small number of employees, “cutting layers” to streamline operations.
According to the company, the goal is to remain agile and focus specifically on long-term growth, at the same time as AI expertise has reportedly become the new norm for employees.
ServiceNow is negotiating to acquire security startup Veza for over a billion.
Veza develops and builds identity security, which also monitors AI agents’ access to data.
A potential deal would further strengthen ServiceNow’s investment in AI and cybersecurity services. Veza was recently valued at approximately $808 million.
Here’s a story about how Shopify’s backend systems crashed on Cyber Monday, which messed up many merchants’ day.
Some couldn’t log in and others lost access to their point-of-sale systems, i.e., “quite” important tools. The company quickly fixed the issue… at least mostly, and stated that the situation was already recovering, although minor disruptions might still be visible.
The outage unfortunately hit on a day when online purchases are expected to rise to over $14 billion in the United States.
Sprinklr increased its revenue, and its subscription business, in particular, progressed nicely. On the other hand, the result was slightly weaker than a year ago, but adjusted, the company nevertheless improved its performance. Cash flow remained strong.
Management said that the change is progressing in the right direction and that more momentum is being sought for the end of the year as a basis for growth in the coming years.
Snowflake had another great quarter; revenue and especially profits grew significantly compared to a year ago, and customers are using the service more extensively than before.
Management emphasized that Snowflake is a key tool for many companies in leveraging data and AI, meaning there is at least faith in the future in their words, as English-speaking executives always seem to have in abundance.
The new Snowflake Intelligence AI solution has gained significant momentum, and partnerships with major model providers and cloud platforms further strengthen the overall offering.
ServiceNow neuvottelee Armis-kyberturvayhtiön ostosta jopa seitsemän miljardin dollarin kauppahinnalla.
Listautumista harkinnut Armis suojaa verkossa olevia laitteita ja sen asiakkaina ovat esimerkiksi yli 40 prosenttia Fortune 100 -yhtiöistä.
Demand has been surging for advanced digital security services after a series of cyberattacks that cost billions in monetary losses and data leaks across the globe this year alone. Lawmakers have been calling to make cyber-resilience a board-level priority.
The markets didn’t really react positively to this acquisition news.
The acquisition corresponds to about four percent of the market value. Additionally, the tweet reveals that high interest rates generally weigh on technology companies’ valuations and increase caution among investors; the tweeter emphasizes that this still doesn’t change the fact that the company is high-quality, etc.
Snowflake shares slipped following news that the company is in talks to acquire the startup Observe for approximately $1 billion, which would mark the company’s largest acquisition to date.
The deal would move the company into the “observability” market—tools used to monitor application performance and outages—thereby intensifying competition with Datadog and Splunk.
Observe is already closely integrated into the Snowflake ecosystem, and the estimated purchase price is considered to be financially well within Snowflake’s reach.
Snowflake CEO Sridhar Ramaswamy says that AI models are becoming cheaper and more common, so the “best model” is no longer enough – common standards/the “HTTP moment” for agents and systems that learn from feedback are becoming more important. AI adoption often spreads through employees, which is when judgment and prioritization are emphasized.
And here’s the part enterprises won’t like: AI adoption isn’t coming from CIO roadmaps. It’s coming from employees quietly using tools that make them faster today.
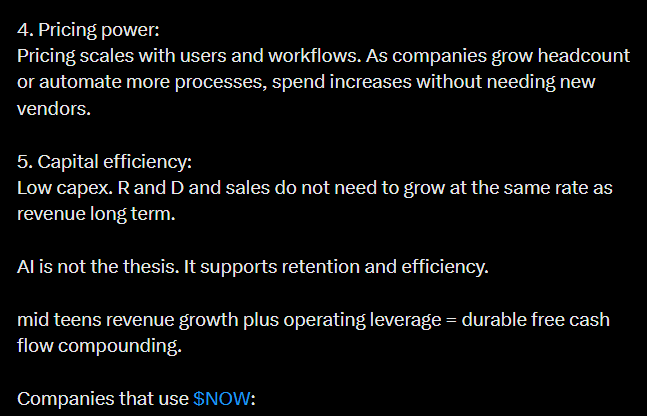
The tweet explains why ServiceNow’s business model works, because for example, cash flows are high-quality and predictable (subscription-based and multi-year contracts + “customer expansions”), the cost structure scales well, software switching costs are high, and there is pricing power.
Snowflake is acquiring the company Observe, which provides an “observability” solution, i.e., tools for monitoring software and “data streams”; they help identify various performance issues and bugs early. The deal was announced today, but it still requires regulatory approval.
The goal is to integrate Observe’s product into Snowflake so that customers can collect logs, metrics, and traces, among other things, in one place and more easily see where a fault originates. The purchase price has not been publicly disclosed, but market estimates put it in the billion-dollar range.
There was already some talk about this earlier, but now the deal seems more certain.
This deal could be a sign that data company consolidation will continue in 2026. Snowflake has been particularly active, completing and announcing several AI-related acquisitions in 2025, including Crunchy Data and Datavolo, and Select Star, a data governance and metadata management platform that helps organizations understand and trace their data at scale.
I came across this tweet analysis of ServiceNow online and thought I’d share it here, as it provides a good, comprehensive deep dive and then some.
The thread covers the strength of the company’s balance sheet, return on capital trends, growth drivers, and how current valuation relates to expected future earnings and cash flow growth.
Finally, the author considers at what levels the risk-reward profile would look attractive.
ServiceNow and OpenAI are launching an extensive partnership according to the article below, which is expected to integrate cutting-edge AI capabilities directly into ServiceNow’s software.
Going forward, companies will be able to use AI for tasks such as text summarization and streamlining customer service without the need for complex coding. This is seen as a significant step that could potentially strengthen ServiceNow’s market position and help companies leverage AI in their daily operations more easily and efficiently.
ServiceNow grew strongly; for example, subscription sales and total revenue rose briskly. Additionally, the “remaining performance obligation” (backlog) accumulated significantly more than before. New large deals reportedly came in at a fast pace, and the number of large customers increased.
Management noted that the quarter beat expectations, and exceptionally strong guidance was provided for next year. Further share buybacks are planned to curb dilution, and AI products are reported to have gained good traction.