Foreign serial acquirers

Foreign Serial Acquirers

A dedicated thread for Swedish serial acquirers has long been wished for, so I decided to open a new one, even though I don’t know much about them myself. These companies have been discussed on this Forum for at least a couple of years, and the establishment of a thread for less than a month, so I thought I’d get things started. Verneri (or Johannes/analysts) can correct my opening post if necessary, or add their own insights after my initial post.

@TheTurunen asked why limit it only to Swedish companies, so I slightly changed the title and the text of the opening post – why limit it unnecessarily? So, in this thread, you can discuss serial acquirers from Sweden or other countries.

Serial Acquirer:
A company that allocates a large portion of its capital to corporate acquisitions and thus aims to create value. The word ‘compounder’ probably describes a serial acquirer quite well; in stock market language, it refers to a company with a high return on invested capital, which seeks to find new profitable companies that generate cash flow. In this way, the company creates a compound interest effect.

Below are various Swedish serial acquirers:

Indutrade
A large serial acquirer, has grown revenue by 9 percent for 12 consecutive years, revenue over 2 billion, and return on invested capital of 20 percent.

Lifco
Revenue of 1.8 billion and an operational profit growth of 21 percent over eleven years.

Addtech
Revenue well over a billion, operational profit growth averaging over 10 percent in recent years.

Lagercrantz
Revenue of approximately 0.5 billion, operational profit growth averaging over 10 percent in recent years.

Fasadgruppen
Is a relatively recent listing, approximately 20 acquisitions in 2021, and revenue of approximately 300 million in the same year.

This Inderespod episode discusses serial acquirers very broadly, including Swedish companies.

Joonas has also mentioned Lagercrantz on the Forum:

He has also written about Lifco:

Likewise about Indutrade:

If you want to generally understand serial acquirers, the Boreo thread also discusses other serial acquirers besides Boreo itself. Then you should check out, for example, Boreo’s comprehensive report, which is available for everyone to read.

I apologize that the opening post isn’t better, but I wanted to start the discussion now before summer arrives, as the Forum always quiets down then.

This thread will surely be of high quality, so please start discussing Swedish serial acquirers, thank you!
:slight_smile:

EDIT:

I changed the title and text a bit, because why limit it? :slight_smile:

EDIT:2
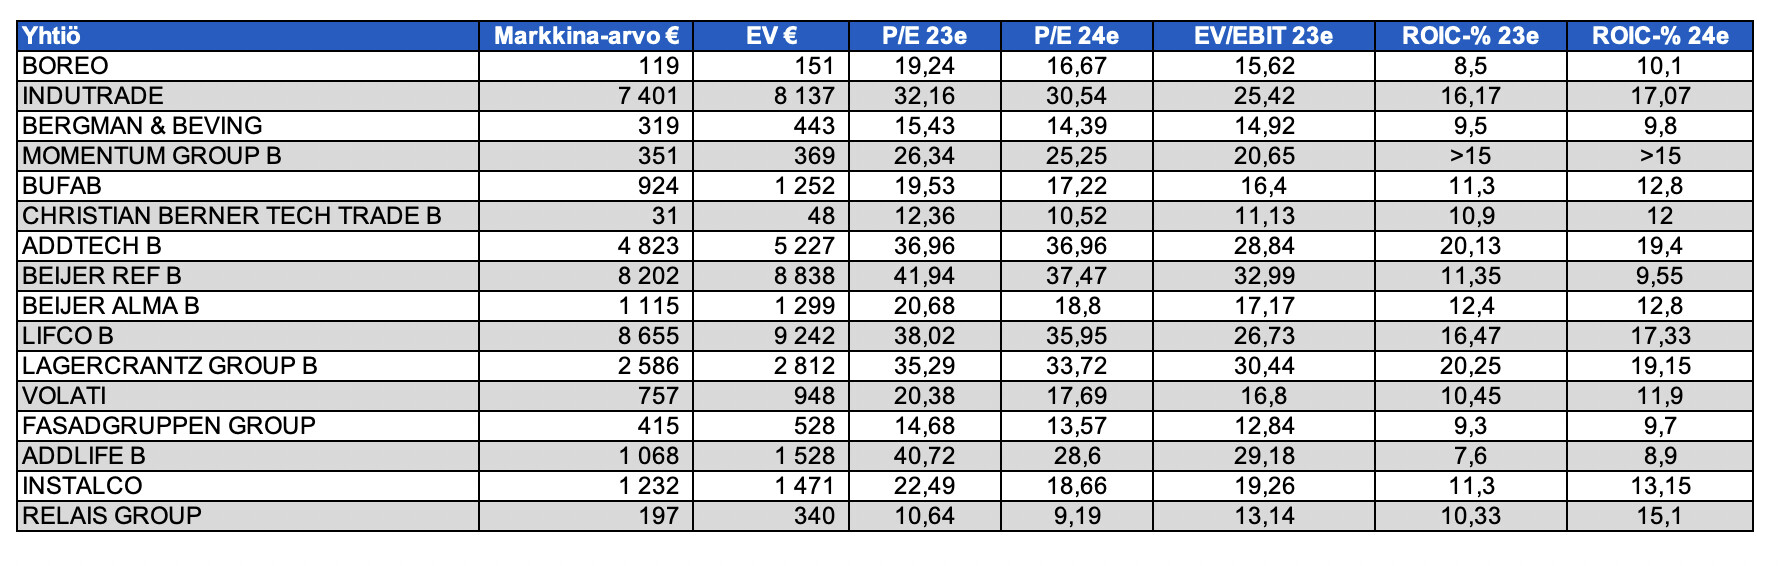
@Eemeli_Oikarainen has made a great comparison table of serial acquirers. :slight_smile:
35 Likes

Interesting topic. Just a thought, why limit the thread to only Swedish serial acquirers? There are plenty of interesting companies in the same genre to be found elsewhere as well.

9 Likes

If you’re comfortable with Swedish, here are some views from a Swedish analyst regarding these serial acquirers:

And a slightly more exotic one from across the pond – U.S.-based OneWater Marine, which buys up boat dealerships and lets them continue as independent businesses. The industry is extremely fragmented, so there will be plenty to buy, and they have already bought a lot.

5 Likes

I recommend checking out the serial acquirers event recently organized by Red Eye. The participants were mainly Swedish firms, but also the domestic Boreo as well as Judges Scientific from England. Röko was also present; there have been rumors about their IPO for a while now, and it’s on my own watchlist.

Red Eye also regularly writes articles about serial acquirers.

Especially in Sweden, there are a lot of serial acquirers who seem to use pretty much the same playbook. This presents its own challenge for the investor in figuring out which ones to get involved with. Below are a couple of other links on the subject that are worth checking out if you’re interested in the topic.

https://www.scuttlebutt.co/p/sidecar-investing

https://assets-global.website-files.com/5f90407432ecf3e31124a6d9/622128e2a5980d400e990051_Serial%20Acquirer%20Primer.pdf

11 Likes

Bastide Le Confort Medical SA

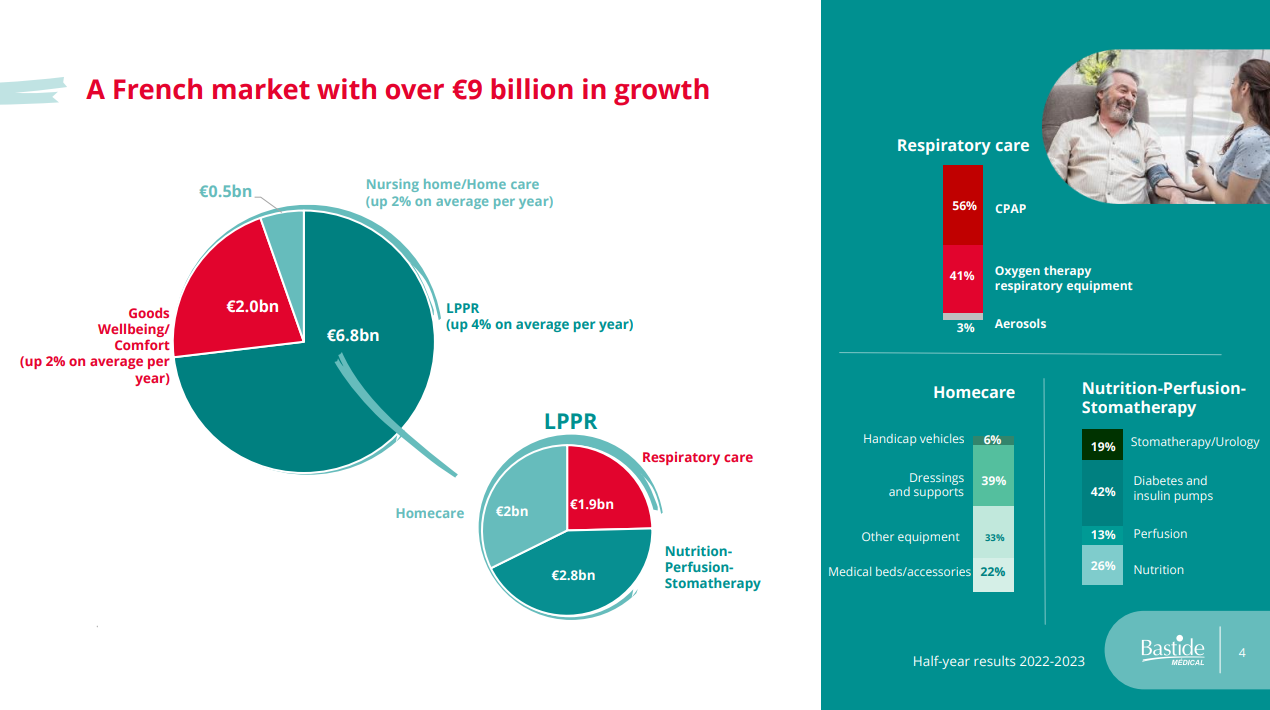
Since I’m getting a bit tired of hearing about Lifcos and Constellations, let’s have some variety for a change. This is a French healthcare “serial acquirer” whose business involves home care equipment and other medical devices (insulin pumps, blood pressure monitors, etc.). These are sold/rented to both consumers and professionals. It currently operates in 7 countries, and approx. 18% of revenue comes from outside France. According to the company itself, the French market is around €9bn and is growing at a moderate pace of 4% p.a. Megatrends like the aging population guarantee that the market is unlikely to suddenly disappear.

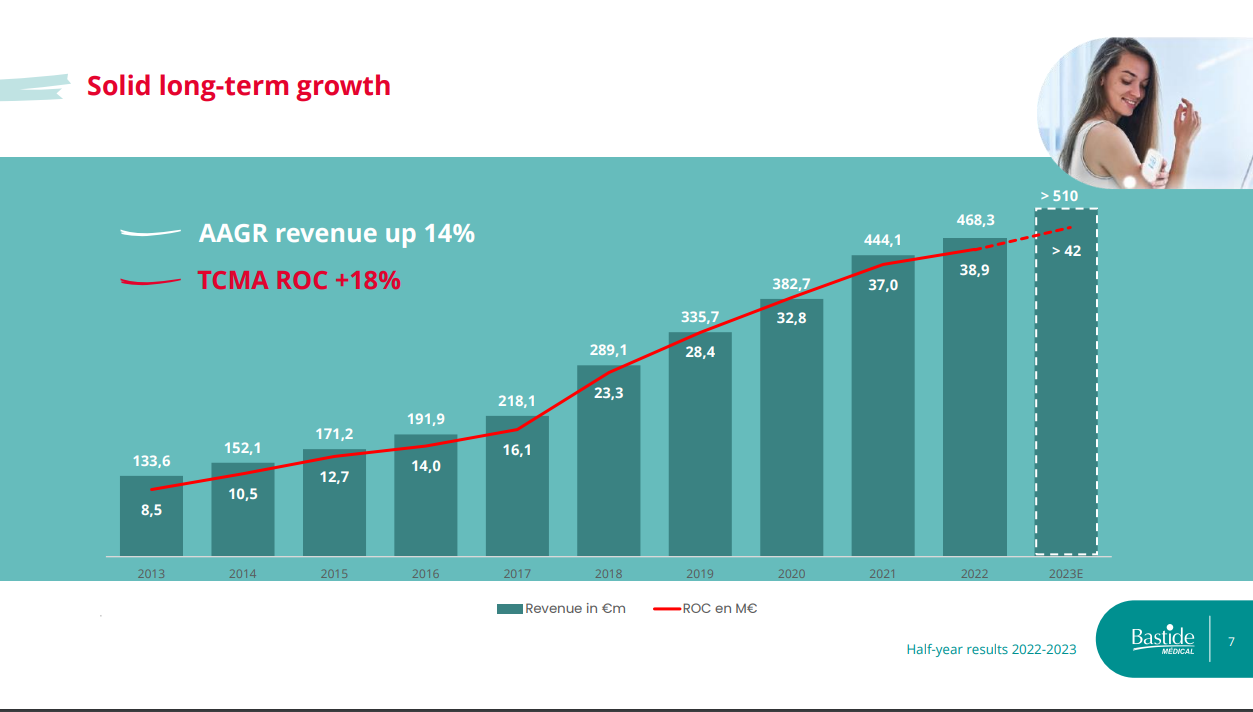
The business benefited strongly from Covid, and now it is returning to a path of organic growth supported by acquisitions. Unfortunately, this is limited by a high level of indebtedness at 3.88 net debt/EBITDA, sacré bleu! However, about 80% of the debt matures within 3 years, which reduces the threat of a worst-case liquidity crisis.

There are risks, but the valuation is also moderate compared to its peers. A family company is the largest owner with a 53% stake, and they haven’t had a habit of window-dressing reported figures, nor do they dilute shareholders under the guise of growth. EV/EBITDA is 6.2 at a price of €27.75, and once depreciation etc. are stripped out, the company generates strong cash flow. In the coming years, however, it will increasingly have to be channeled into reducing the debt burden.

12 Likes

Serial acquirers certainly interest many on this forum, so let’s set a challenge to find one that absolutely no one is interested in. Yes, let’s dig all the way into the Canadian stock market - Terravest Industries.

It is a small-cap company (MCAP approx. 450 million CAD) that combines a truly low-profile operation with a culture of high-quality capital allocation. The sectors are quite diverse, but the common denominator is the energy industry - there are services and equipment manufacturing related to energy storage (oil tanks and such), heating equipment, maintenance services and supplies for oil fields, energy distribution and transport equipment… I can already imagine the reader falling asleep! Like many other serial acquirers, Terravest looks for niche players and buys them from retiring sellers at multiples so low that even value investors from the early 1930s would be green with envy. The company’s businesses have very low margins (approx. 20-25% gross margin), but when the purchase price is on average 5x EBITDA and approx. 0.6x revenue, one shouldn’t expect too much anyway.

Operational performance is well-demonstrated by the growth in free cash flow and a steady ROIC: between 2018-2022, free cash flow has slightly more than doubled and ROIC has hovered around 16-17 percent. Free cash flow has, of course, been skillfully directed back into acquisitions, but the firm has also taken on quite a bit of debt to finance the large acquisitions made last year. At the same time, one rather large concern in the business can be highlighted: there hasn’t been much organic growth, although last year’s movements in the oil market propelled the firm’s figures into insanely high growth. The three years prior to that, however, were negative in terms of organic growth - so the entire story practically relies on acquisitions.

The management team, led by CEO Dustin Haw and Chairman Charles Pellerin, is excellently committed to the firm, and insiders hold all the power, might, and glory in this company. In addition to the success of the acquisitions, it can also be noted that in the 2010s, capital allocation has hit the mark from practically every angle - the firm distributed a special dividend equal to its market value in 2011, bought back over a third of the shares for cancellation at a price level of 4 CAD, and has since bought 10 percent more of the shares at about half the price of the current level. Not a bad performance, and investors have been royally rewarded for being involved. However, the management team will not go out of its way to tell investors this, because oh boy, how little noise this company can make about itself. No presentations, nothing extra on the investor relations pages, just execution. That isn’t a bad approach either.

The current valuation level is approx. 10x TTM net profit, which is quite a modest level for a serial acquirer. However, I am a bit wary of last year’s spike: no matter how much the company has diversified its business away from the cyclicality of the oil industry, some kind of normalization is likely to be expected. In addition, the debt ratio is approaching 3x CAFD (cash available for distribution, which Terravest, as an excellent company, reports itself in its reporting), which limits M&A activity in the future. And since practically all growth will depend on acquisitions and capital allocation, that debt burden could start to become a major problem. Therefore, I haven’t taken a position, although the firm remains on my watchlist.

Finally, a link to a more extensive presentation of the company, which I utilized while writing this message (highly recommended reading): TerraVest Industries (TSX: TVK) - Deep Dive Research Report

15 Likes

If we’re talking about a company that doesn’t really interest anyone anymore, it’s definitely The Middleby Corporation (MIDD). It’s a serial acquirer focusing on commercial kitchen equipment, etc. It has grown fairly steadily from decade to decade.

8 Likes

Here is (thanks @Eemeli_Oikarainen!) a comparison table for serial acquirers. The table shows at a quick glance a handful of serial acquirers, their market and enterprise values, valuation by my favorite metric, the P/E ratio, and of course, the return on invested capital, or ROIC. I believe these are based on consensus estimates; I still need to confirm this with Eemeli. ROIC was missing for Momentum, so I threw in my own estimate for the coming years. :smiley:

Perhaps @Sijoittaja-alokas could even add this to the opening post? Of course, the table will need to be updated every now and then. :frowning:

The basic idea of serial acquirers is, of course, to allocate cash flow from existing holdings into new acquisitions to create shareholder value (i.e., the return from the acquisition exceeds the investors’ required rate of return. In layman’s terms: if the return on an acquisition remains at the level of index returns, it doesn’t create value for investors who could get the same return by simply investing in an index).

But they can also allocate cash flow within the portfolio to companies with the most promising organic growth prospects. The larger and more diversified the portfolio, the more opportunities there presumably are to also invest in organic growth.

Nordic serial acquirers serve our Nordic industry, and the Nordic industrial sector is actually surprisingly vibrant. Nordic economies are stable, democratic, and highly competitive in many sectors. Through these companies, one can potentially gain very profitable exposure to this juicy market.


From that group, my own portfolio includes Boreo, Momentum, and Christian Berner. Momentum is already profitable (EBITA % >10, ROIC >15 %), whereas Boreo has a lot of work to do to reach its profitability target (ROCE >15 %), as does Christian Berner (EBITA under 5%, target 9%).

Boreo was on ROAST in March; it’s worth a watch.

15 Likes

Added it. Great table! :sunglasses:

The moderation team is free to edit my opening post. :slight_smile:

5 Likes

Handy table, thanks! But I wonder if it’s still quite up to date? For example, Relais’ market cap and P/E are clearly lower than in Inderes’ own table.

My own portfolio includes Boreo, Relais, Embracer, and Christian Berner. Bufab has been on my watchlist, but I haven’t pressed the buy button yet. What fascinates me about serial acquirers is the idea of long-term ownership, where the company actively invests capital while I can remain passive.

6 Likes

I don’t think anyone has posted about the UK’s SDI Group here yet, so I’m sharing it for your information. I came across it on Twitter; I haven’t looked into it in detail, but at a glance, the numbers and performance look strong. Here are some materials on the company if you want to check it out.

https://twitter.com/quartr_app/status/1612448398522871814?s=61&t=1gbb9j3272Aqcflm5qImxQ

8 Likes

Nonniin. :smiley:

Continued high levels of customer activity, favourable demand and acquisitions all led to an increase in revenue of 26 per cent in the first quarter compared to the previous year, including 10 per cent attributable to comparable units. Growth combined with good cost control led to increased margins and an increase in EBITA of 36 per cent compared with the first quarter of the preceding year.

First quarter 2023

  • Revenue increased by 26 per cent to SEK 502 million (399), of which 10 per cent was for comparable units.
  • Operating profit rose by 49 per cent to SEK 55 million (37), corresponding to an operating margin of 11.0 per cent (9.3).
  • EBITA increased by 36 per cent to SEK 60 million (44), corresponding to an EBITA margin of 12.0 per cent (11.0).
  • Profit for the quarter increased by 50 per cent to SEK 42 million (28), corresponding to earnings per share of SEK 0.85 (0.55).
  • The return on working capital (EBITA/WC) was 62 per cent (62).
  • The equity/assets ratio was 43 per cent (50) at the end of the period.
  • As of 31 March, the number of repurchased Class B shares totalled 1,259,624.
  • Acquisition of Hydmos Industriteknik, which has a lead-ing position in advanced hydraulic and gas systems for use in high-pressure applications.
  • Acquisition of LocTech, a comprehensive supplier of seals for rotating and static applications.
  • Acquisition of Agera, a supplier-independent reseller of components and services to industrial customers.
15 Likes
CHRISTIAN BERNER TECH TRADE

Published 4/27/2023 | 12:00 PM

Interim report Q1

The first quarter of the year saw strong growth and increased earnings. The year started on a high level with strong development in both business areas, Technology & Distribution and Energy & Environment. The trend in earnings and growth reflects good order intake in a market that is growing locally despite geopolitical and market causes for concern globally. The Group’s offerings address key societal challenges in their respective markets.

First quarter 2023
• Order intake amounted to SEK 237.8 (215.0) million, an increase of 10.6 per cent.
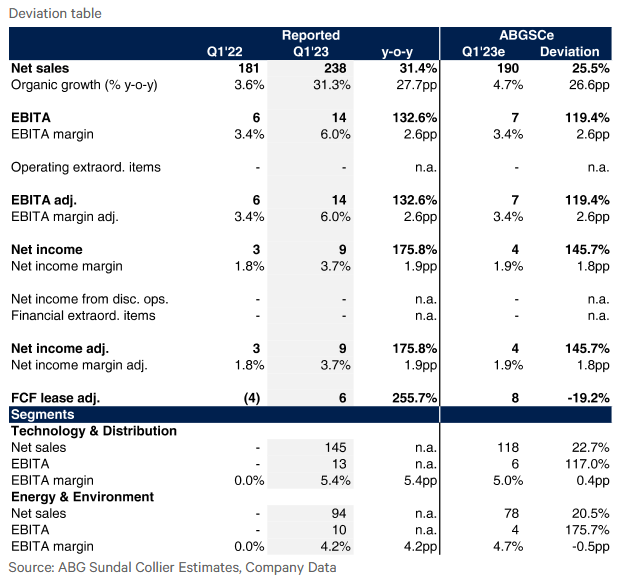
• Net revenue for the first quarter was SEK 238.3 (181.3) million, an increase of 31.4 per cent, of which organic growth amounts to 31.3 percentage points.
• EBITA was SEK 14.3 (6.2) million, an increase of 132.6 per cent. The EBITA margin amounted to 6.0 (3.4) per cent.
• Earnings per share before and after dilution were SEK 0.47 (0.17).
• Cash flow from operating activities was SEK 14.7 (3.2) million. Total cash flow for the period was SEK 6.1 (-3.9) million.

Significant events during the reporting period
• The financing agreement with the Group’s main bank was renewed during the quarter.
• Managing director of subsidiary Bullerbekämparen, Katarina Munter, took office on 1 January.
• During the quarter, extensive work was carried out to implement a new ERP system, with five of the Group’s companies estimated to go live during the second quarter.

Significant events after the end of the reporting period
• There were no significant events after the end of the reporting period.

MESSAGE FROM THE CEO
We are beginning to see the results of our work
The first quarter got off to a strong start for the Group. Good order intake in the autumn were translated into revenue, and earnings are moving in the right direction. We still have more to do, but it is gratifying to see the results starting to come. Our business operates at the heart of major societal challenges in energy, infrastructure, water, sewage, and general industry, which provides an ability to decrease vulnerability during times of external fluctuation.

The Group’s business model provides a great opportunity for a healthy return and we are working to get back to this position after the years affected by the pandemic and disruptions to logistics. The reorganisation at the end of the fourth quarter has reduced internal administration, while enabling better transparency. The increased focus on decentralisation unleashes the strength within our ambitious and knowledgeable employees. The disruptions to logistics have begun to ease and we are starting to work our way back to more efficient working capital management again. Our aim is to reestablish a more efficient, fast-moving organisation while maintaining a high level of service to our customers.

Higher revenue…
Revenue in the quarter increased by 31 per cent compared to the previous year. However, the order intake increased by only 11 per cent, but the level as a whole is acceptable and partly reflects strong comparative figures. In addition, the order intake was somewhat affected by the fact that one of our largest subsidiaries was preparing for a change of ERP system at the end of the quarter, which had a temporary effect on their order intake. We are already beginning to see the energy that is being freed up by having more efficient and modern business support and look forward to being able to achieve even more leverage during the year.

… and higher profits
EBITA in the quarter more than doubled and the margin increased to 6 per cent. We are pleased with the increase, but the financial margin target we have set is higher and we still have more to do. We are continuing our work to establish a higher and more consistent level of earnings than we have achieved so far.
It is gratifying that both business areas show a strong trend in both growth and margin. At Group level, the quarter was somewhat affected by some minor one-off effects, including writing off older systems that is retired in connection with ERP system changes.

During the quarter, we also extended our existing financing. Together with our focus on increasing the Group’s own cash conversion and our new organisation that more easily enables the integration of new acquisitions, we look forward to being able to continue our acquisition strategy.

9 Likes

The turnaround is progressing promisingly and rapidly. I don’t know if the company’s 9% EBITA margin is an easy target (it has never been reached), but at least progress is being made in that direction.

6 Likes

Yes, it looks quite good. :blush:

By the way, did you find an investment analysis on Christian Berner, or did you do all the stock research yourself?

The serial acquirers table you posted had valuation multiples/forecasts for this and next year. Do you know where they were taken from?

6 Likes

I wonder if we’ll reach around the ten mark on an earnings basis at current prices by the end of the year? There seems to be some seasonality in the business, as Q2 and Q3 have traditionally been quite strong.

3 Likes

At least ABG has some analysis, it can be found here https://cr.abgsc.com/foretag/christian-berner-tech-trade/Equity-research

:slight_smile:

6 Likes

Thanks Verneri, this was a useful link. The latest report didn’t open on my computer yet, but I looked through the previous reports.

The company clearly exceeded ABG’s expectations.
Before the report, the analyst’s fair value for the stock was 30-40 SEK.

The EBITA margin has improved by 2-3% in the previous quarters. It will be interesting to see if a similar improvement carries through for the rest of the year.

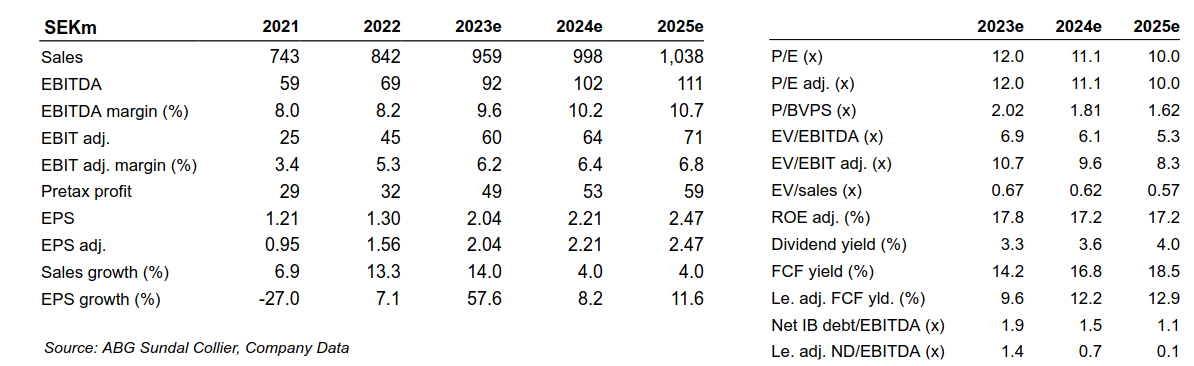
EDIT 28.4.2023

Here is ABG’s updated forecast table based on Q1, with the stock price at 24.60 SEK.

4 Likes

Announcement begins.

https://lifco.se/investors/financial-reports/interim-report-january-march-2023/

Lifco is still in absolutely incredible shape. Revenue growth in Q1 was 18%, organic 8%. EBITA grew by 31%, because why not. ROCE is hovering around the 23 percent level.

A P/E of over 30 is a wild price to pay for a company whose business model doesn’t exactly scream strong, scalable competitive advantages. But gradually I’m starting to get the same feeling about this as with our domestic Gofore: at some point, you just have to accept that companies of this quality shouldn’t be priced like mere mortals, even if the idea is frightening in principle.

Announcement ends. Lifco: not (yet) in the portfolio.

11 Likes