New investor material related to the previous Investors Day event.
A transcript or presentation would be useful here..
https://static.seekingalpha.com/uploads/sa_presentations/634/81634/original.pdf
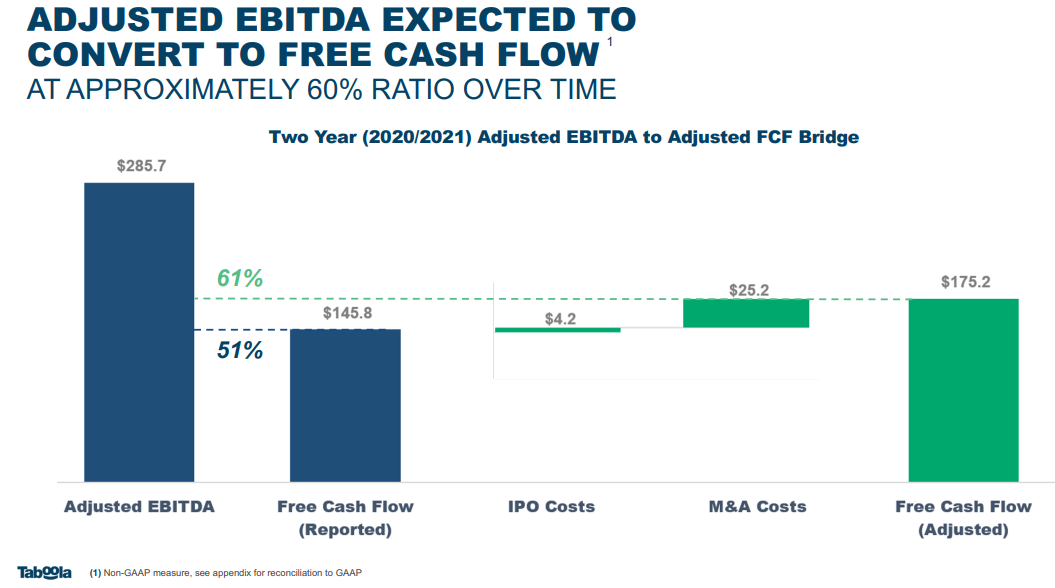
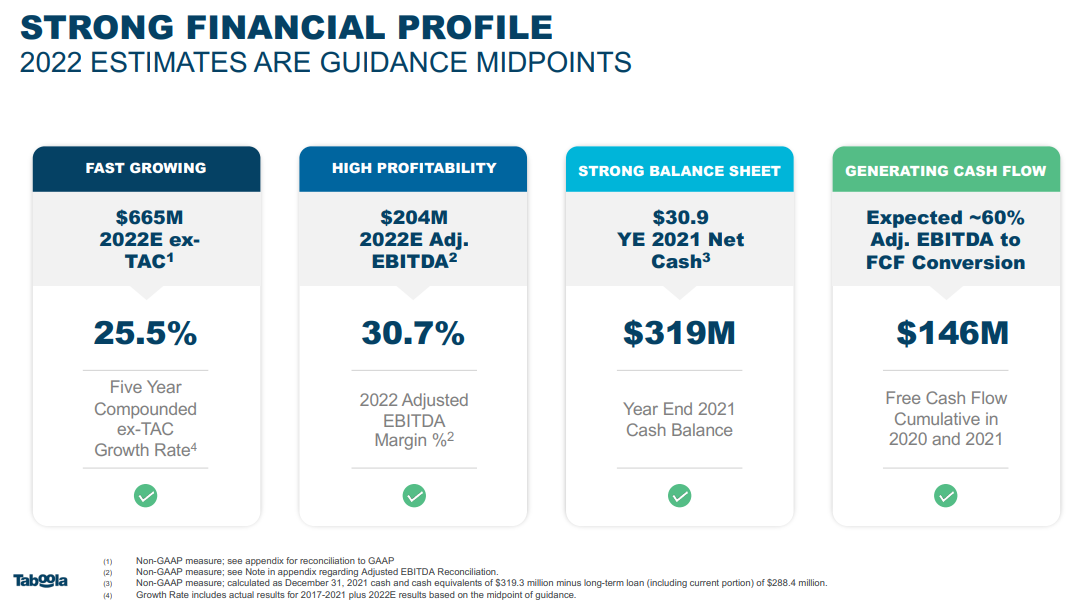
A couple of picks from the slides at the end
New investor material related to the previous Investors Day event.
A transcript or presentation would be useful here..
https://static.seekingalpha.com/uploads/sa_presentations/634/81634/original.pdf
A couple of picks from the slides at the end
Forward-looking PS ratio already well below one, at 0.63. Gross margin, of course, a weak 32% but not at all murderous. But still, by trimming the company, you could probably get a PE of 10. I could also imagine that as an affordable AdTech firm, it would be an attractive acquisition target at current multiples.
Bad reputation → the junk ads screenshotted above do not inspire confidence.
I went to YouTube to watch user experiences. Like, we set up an online store and advertised it like this. It seemed that ads through Facebook and Google performed better and allowed for more precise targeting. On the positive side, you could think that Taboola was still an alternative to these true advertising mega-giants.
I listened to the CEO’s interview on the Business Breakdown channel: Spotify
Not on the level of Musk, Jobs, Karp. But in my opinion, clearly better than Zuck. I liked that he had a clear vision.
The PS ratio combined with growing revenue makes my finger twitch to hit the buy button.
Q1 figures out:
https://investors.taboola.com/news-releases/news-release-details/taboola-reports-q1-2022-results
Strong growth continues, EPS just barely in the black. Free cash flow also positive 
- Beat Q1 guidance on both of the non-GAAP metrics we primarily focus on, ex-TAC Gross Profit and Adjusted EBITDA.
- Revenues of $354.7M grew 17% over Q1 2021.
- Gross Profit of $112.0M grew 25% and Ex-TAC Gross Profit of $138.2M grew 31% over Q1 2021 and 8.4% pro forma with Connexity**.
- Generated net income of $3.9M, Non-GAAP Net Income of $21.9M and Adjusted EBITDA of $34.9M.
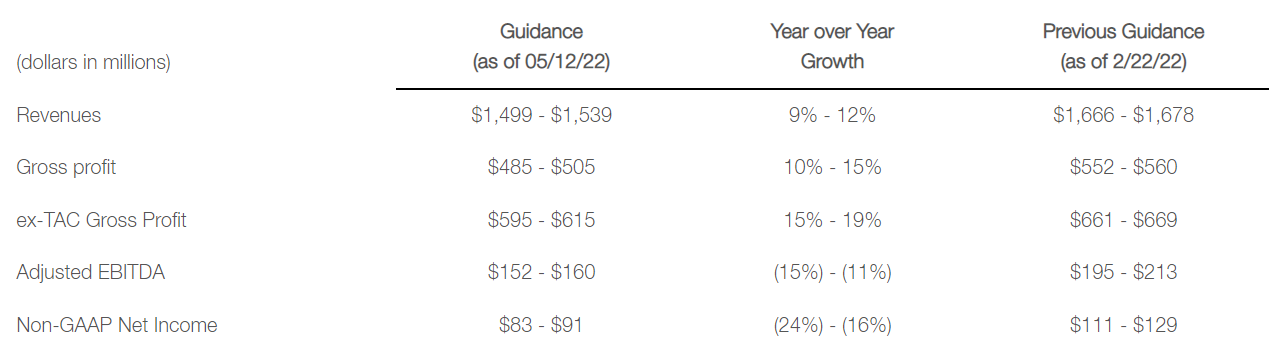
- Revising 2022 full year guidance ranges to Ex-Tac Gross Profit of $595M to $615M, and Adjusted EBITDA of $152M to $160M.
However, forecasts have been significantly lowered going forward; growth continues YoY, but is slowing down 
Gravity R&D’s core offering, Yusp, is used by leaders in retail, e-commerce, and digital media to provide personalized offers to customers to drive sales, increase average order sizes, build customer loyalty and create more positive user experiences. Yusp’s technology is built on proprietary algorithms that focus on deep learning for personalization – coupling contextual data and brands’ first party data to make recommendations for shoppers.
Gravity R&D was founded in 2007 by experts in algo, deep learning and data science. Its founders, which are still part of Gravity R&D today, had tied for first place for the Netflix Prize, a public competition to find a team to improve Netflix’s recommendation technology. Gravity R&D has customers in more than 20 countries and currently powers more than 35 billion recommendations each month for leaders in retail, e-commerce and digital media including N11, Kaunet, GoShop, La Vanguardia, and Deutsche Telekom Hungary.
Cutting costs
- Taboola (NASDAQ:TBLA) on Tuesday announced a cost restructuring program to ensure profitable growth and free cash flow in 2023 and beyond.
- TBLA expects this program to reduce operating expenses by $50M in 2023, with a significant portion translating to improved adj. EBITDA and free cash flow.
- The program includes restructuring teams primarily in lower priority activities, which will result in ~6% overall reduction of global headcount.
- TBLA will trim an additional $23M from 2023 discretionary expense budgets and reduce capex by an additional $15M in 2023.
- The program is expected to be largely completed by year-end.
- TBLA also reaffirmed its Q3 guidance and projected over $152M in 2022 adj. EBITDA.