Taboola - Adtech for OpenWeb - an online advertising alternative

Google’s ad revenue growth is truly strong. Similar news has been seen not only domestically but also internationally. I believe this will also be reflected in Taboola’s Q2 results :crossed_fingers:

The continuous dumping of growth stocks in the market tests one’s patience. I just need to keep trusting my vision and the return of valuation. Perhaps I’m a bit too heavily invested in this :thinking:

2 Likes

Oppenheimer adds to list: Outperform and $14

https://www.streetinsider.com/Analyst+Comments/Oppenheimer+Starts+Taboola+(TBLA)+at+Outperform/18755485.html

Q2 results will heavily determine the direction. Ad tech results have been strong in Q2, let’s hope the same continues for Taboola. :crossed_fingers:

1 Like

Taboola Q2 above expectations and raises guidance, which shouldn’t be a surprise given previous strong ad-tech results. The acquisition of Connexity on top of that in September certainly looks good :slightly_smiling_face:

Significant expenses from the listing/merger, which pulls EPS into negative territory. Primarily share-based compensation, but also admin expenses. Also invested in marketing and advertising to develop growth

https://investors.taboola.com/news-releases/news-release-details/taboola-beats-q2-guidance-raises-expectations-rest-year-and-2022

Second Quarter Financial Highlights

  • Q2 results exceeded guidance across all measures

    • Revenues of $329 million versus guidance of $315 to $320 million.
    • Gross Profit of $100 million versus guidance of $88 to $95 million.
    • ex-TAC Gross Profit of $117 million versus guidance of $108 to $113 million.
    • Adjusted EBITDA of $41 million versus guidance of $34 to $36 million.
  • Revenue grew $61 million or 22.9% year-over-year.

  • Operating expenses grew $87.8 million or 133.2% year-over-year. Excluding higher share based compensation of $76.0 million year over year, mostly triggered from going public, operating expenses grew $11.8 million or 18.5% year-over-year. This increase was driven by:

    • An $0.2M increase in research and development as increases in headcount were partially offset by lower depreciation related to timing of new server investments. We continue to invest in our proprietary, deep learning data engine as well as new products and tools to support our publishers and advertisers.
    • An $3.6M increase in sales and marketing expenses to support our business growth.
    • An $8.0M increase in general and administrative expenses related to public company investments and a partial return to more normal operations following the COVID pandemic.
  • Net loss of $61.4 million was $74.3 million lower year over year primarily driven by the higher share based compensation. Adjusted EBITDA of $40.8 million increased by $5.9 million year over year driven by the higher revenue.

  • Cash Flow from Operations of $23.1 million and Free Cash Flow of $6.9 million declined year over year driven by higher purchases of property and equipment and changes in working capital.

3 Likes

Following up on the earnings call transcript

https://seekingalpha.com/article/4448355-taboola-com-ltd-tbla-ceo-adam-singolda-on-q2-2021-results-earnings-call-transcript

  • Connexity and Taboola have really good synergy benefits, and this collaboration will be a big plus for the top and bottom lines over time :+1:

  • PIPE shares are still unregistered due to additions related to the Connexity acquisition. Coming to free float in September

Selected points from analyst questions

  • Connexity is now mainly in the US market. Global distribution through Taboola.
  • Many old contracts were made in advance in 2019 with poor margins or at a loss; now they are profitable and will be more profitable in the future. Scaling and growth investment are working as planned.
  • No new acquisitions coming immediately; integrating Connexity provides enough work for now.

Although the market dropped 6% after the release, I’m personally in for the long term, and the stock price will follow the fundamentals over time. The valuation is not high, and Connexity’s synergies should come through in a couple of quarters.


Edit:

Adding the Earnings call presentation

The Connexity acquisition, announced in July, has been confirmed. The synergies are significant, so after integration, we should start seeing rapidly increased new sales to existing customers. Assuming, of course, that the integration goes smoothly.

https://investors.taboola.com/news-releases/news-release-details/taboola-completes-acquisition-connexity-creating-powerful-e

1 Like

Xiaomi partners with Taboola, starting to get extensive additional visibility with content production:

Xiaomi will integrate these recommendations, as part of a long-term strategic partnership with Taboola, on the lockscreen of its more than 100 million overseas smartphones


Taboola gets a new follower from Credit Suisse

  • Credit Suisse analyst Stephen Ju initiated coverage of with an Outperform and $14 price target, implying a 53.5% upside.
  • Ju says that the recent $800 million Connexity acquisition helps to onboard e-commerce operators and retailers to give them access to Taboola’s inventory. It will speed up the company’s share gains into $35 billion in potential media spend.
  • As Taboola’s core product is the ability to recommend content, there remains the potential for the company to experience a more significant proliferation of its services into other forms of media, including connected TVs for video.
1 Like

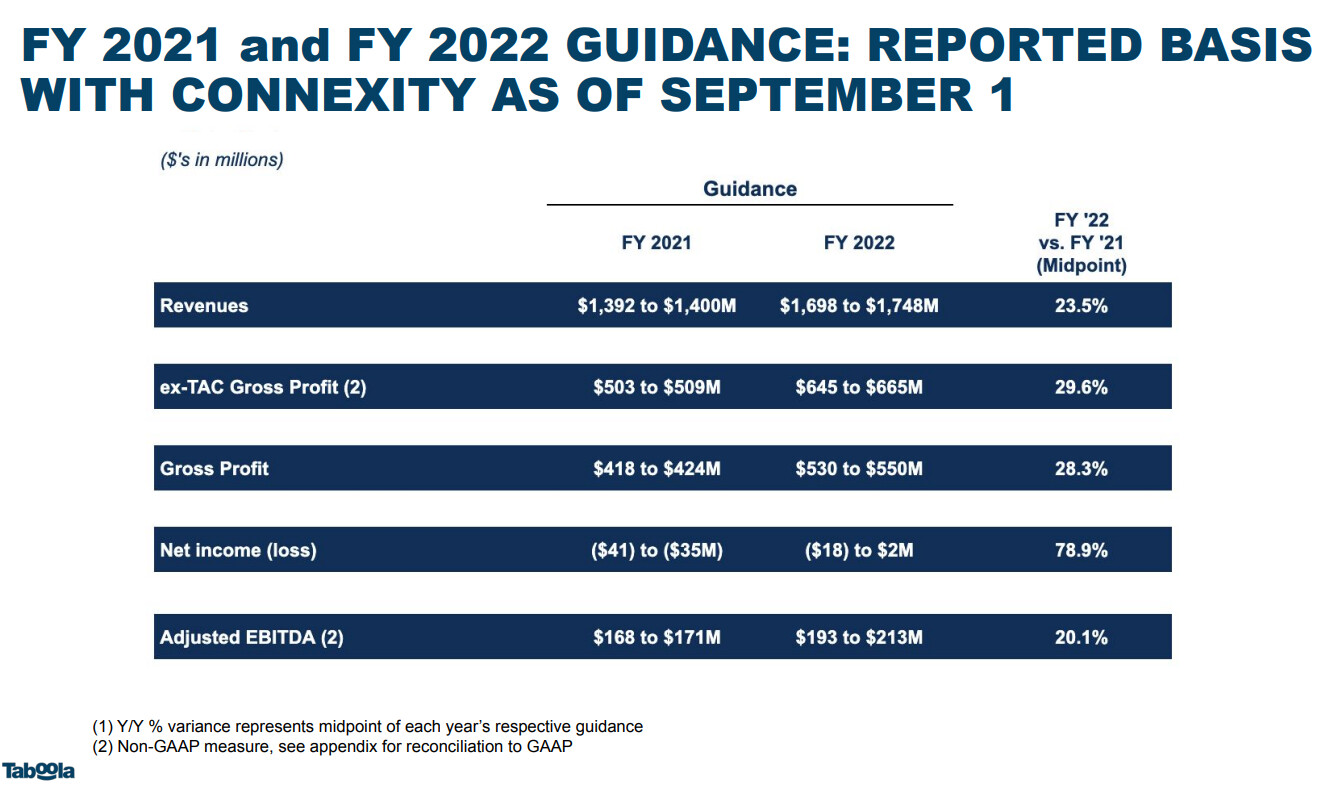
Connexity Deal Update to Forecasts

https://investors.taboola.com/news-releases/news-release-details/taboola-share-its-e-commerce-strategy-following-connexity

And new presentation
https://investors.taboola.com/static-files/41d0ff55-c65f-49bd-9c6a-32d8c1cb49ab

Reasonably impressive partnerships during the year

Quickly, compared to previous ones, the combined EX-TAC revenue seemed smaller than the previous ones. However, Connexity is only reflected in the figures for 4 months. This year’s figures should be chewed on deeper, but in the longer term, synergies and cross-selling are more essential

1 Like

Taboola’s founder was a guest on Colossus’s popular Business Breakdowns podcast. The episode, which is just under an hour long, covers pretty much everything essential about the company:

3 Likes

What a great link and interview :+1:

And those click numbers are really something incomprehensible :exploding_head:

This is how you change the world and build a profitable business in the long run. When things work correctly and the customer can directly decide what, why and how much. A truly great attitude and it also shows in what time such a huge business has been built.

Jesse: [00:22:24] For those who aren’t familiar with publishers and advertisers and the incentives that they both have and what they’re trying to accomplish, unpack the concept of yield. You use that word yield. I’m guessing most people listening don’t understand what that actually means. So what do you mean when you say yield? And talk about the advertiser. Another way to ask it is why not give you 10%? Why not give you 80%? What math are they doing that matters to them for their comfortable to pay you? And then on the flip side of that, why is a publisher willing to accept that rate from you?

Adam: [00:22:51] Taboola is a performance marketplace. We don’t care how much you pay. You pay as much as you want to pay as an advertiser, and you only stick around if it works. We have no rate cards. We don’t tell you pay this for that and pay this for that. You can pay a penny, you can pay a dollar. It doesn’t matter. And you stick around and only if it drives the threshold that you’re looking to achieve as a business. So let’s take an example. Let’s say you are a subscription business and you’re willing to pay $20 for a subscriber. And you come to Taboola, and you pay Taboola 20 cents, 10 cents, 50 cents. I don’t know, slash don’t really care. You try it out, and you will monitor on your end whether the users Taboola ended up sending you translated in effect to $20 less or more acquisition costs.

If you did, you’ll never stop working with us, regardless of how much you’ve paid us. And if it didn’t, you stop working with us even if it was the most affordable payment. I love that because when you had a performance business, by the way, especially when you saw that on a pandemic, everybody that’s om the branding advertising space immediately paused to see what’s going on. Everybody in the performance business who knew how to attach some sort of performance metric to their business leaned in.

So that is our business on the advertiser side. And that is why the payment is, and the price is irrelevant. It’s all about whether it’s works or not. And then on the publisher side, publishers optimize for yield, which is what is the revenue they generate per 1000 times a user sees the ad unit or experience. If it’s more, or if it’s less, that’s eventually what they care about.

The second thing, you want to make sure this yield goes up over time. And that usually happens when companies are healthy, plus invest in AI, advertiser base, user experience, quality and all those good things. So that’s what publishers optimized for. And Taboola was able to build a business that is healthy for advertisers and healthy for publishers who choose to work with us for a long time.

3 Likes

Another new deal, NBC Sports this time

Under the agreement, all NBCSports digital properties will adopt Taboola as their exclusive video monetization and content recommendations provider for mid-article placements. These placements offer video advertisers a prominent brand safe environment to reach relevant consumers, while also allowing NBCSports the ability to recommend and promote their own content and initiatives.

1 Like

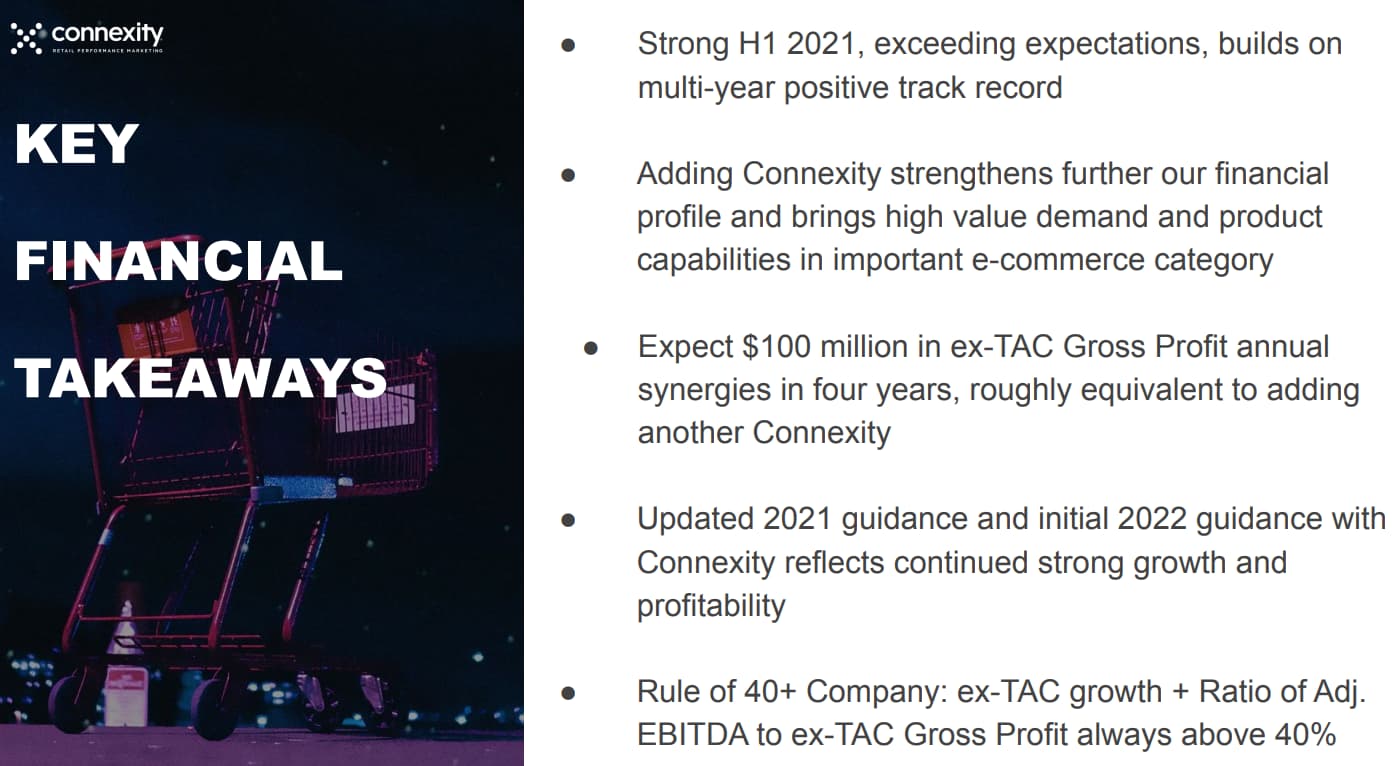
Synergies unveiled between Connexity and Taboola

Valuation has been stated by many sources to be on the low side. Q3 will tell a lot about where things stand.
At least Perion pulled really strong numbers, so there’s some basis for Taboola there too.

https://seekingalpha.com/article/4462753-taboola-stock-expansion-e-commerce-connexity-acquisition

1 Like

Q3 out, the first full quarter after listing.

EPS positive :partying_face:

  • Taboola.com (NASDAQ:TBLA): Q3 GAAP EPS of $0.07 beats by $0.09.
  • Revenue of $338.77M (+16.6% Y/Y) beats by $0.4M.

This should look good in many people’s portfolios, my own expectations were in the same direction based on peer results. A lot of small adjustments in the numbers one way or another, e.g. for warrants, which affect this. But Connexity’s (Connexity) costs are also still coming. With the synergies now coming through, Q4 and 2022 look good. Valuation is not too high, there is plenty of upside potential to analysts’ forecasts, which also have upward pressure after this.

https://investors.taboola.com/news-releases/news-release-details/taboola-reports-strong-q3-results-and-raises-full-year-2021

2021 Outlook Raised

Q4 Estimates

For the Fourth Quarter 2021, the Company currently expects:

  • Revenues of $392 to $396 million
  • Gross Profit of $129 to $132 million
  • ex-TAC Gross Profit of $163 to $165 million
  • Adjusted EBITDA of $61 to $63 million

More automation for customers to manage services

https://investors.taboola.com/news-releases/news-release-details/taboola-announces-smartbid-dimensions-new-autonomous-driving

Analysts’ estimates saved before updates

3 Likes

More investor presentation slides:

https://investors.taboola.com/static-files/e4ea9edd-dbfe-4c0f-bff8-6224daa46a36

Diversified customer base

Connexity’s operating model, fits well with Taboola.


Synergies and integration


1 Like

I went through the investor call transcript and made some notes here.

https://seekingalpha.com/article/4468076-taboola-com-ltd-tbla-ceo-adam-singolda-on-q3-2021-results-earnings-call-transcript

While adjusted EBITDA is a good proxy for profitability, Taboola generates good cash flow. Over the last two years, about 60% of our adjusted EBITDA converted to free cash flow. I’m very happy with the team’s execution, and these results give us confidence to raise our Q4 and full-year 2021 guidance.

At the center of what we do is proprietary deep learning recommendation engine that is able to infer what a user might be interested in based on context and our own curiosity risk. Looking at what people who read this also read, similar to Amazon, people who bought this also bought. This means that we’re not relying on third-party cookies or IDFA, but whether our own proprietary data

Our Connexity acquisition falls within our recommending anything strategy, allowing us to recommend products and tap into a huge 40 billion open web e-commerce market. Connexity will help us transform the open web into one big shopping cart.

It’s only been a few months and I like seeing these early signs of the market reacting positively. This is only the beginning. Since the acquisition closed, we have worked through the details of our integration and our plan is to capture $100 million of synergies we outlined in our e-commerce with Connexity Information Session in late September

This is also true for Connexity where the e-commerce recommendations are solely intent driven. This quarter, there was a lot of conversation on privacy, impacts on IOS changes and IDFA. We did not see impact from these on our business. Taboola’s yield keep growing through our ability to leverage contextual signals due to our Hearst coated integrations with 9,000 publishers, through which we reach 500 million active users every single day. This is important now and will become even more important over time as advertisers look for alternatives to the walled garden.

So, I would say that the most immediate thing which we’re working on is to bring Connexity demand on to Taboola’s core experiences or Taboola Feeds all around the world on 9,000 publishers. We’ve mentioned that we believe a single-digit percent of our traffic has high intent already and is able to basically absorb those high paying and premium retailers that are looking to convert in the open web. So that’s something that we expect to happen. It’s one of the synergies.

22 views updated with Q4 results. Otherwise, a conservative forecast, wants to see results first and will adjust upwards if necessary.

I think we have very good strength going into 2022 and we’re looking forward to talking to you in February about our Q4 results and then probably revising expectations for 2022 at that point.


A lot of content and good vibes. If you are interested at all, it’s worth reading through. Videos are a big part of the operation, a significant source of revenue and growing.
Many new launches and significant benefits from synergies are coming.

There were many one-time costs in Q2-Q3 that will not recur on the same scale in the future. Of course, there will always be some, but clearly exceptional ones related to the Connexity acquisition, IPO stock-based compensation, and other IPO costs.

Now I’m starting to see the reasons why I got involved with a slightly larger investment. Strong growth and steady, predictable results combined with free cash flow :v:

4 Likes

It’s been less followed, even though I still have a position that was halved before the turn of the year at the bottom of my portfolio. A new contract has been published.

https://seekingalpha.com/pr/18628213-taboola-renews-long-term-contract-siamsport-co-th-marking-10-year-partnership-in-driving

3 Likes

Q4 and 2021 results are out

Compared to other US growth companies and most deSPACs, positive cash flow is unusual. Otherwise, very strong performance, contracts are being published at a steady pace.

  • Cash Flow from Operations decreased $35 million year-over-year and Free Cash Flow decreased $41 million year-over-year reflecting in part higher publisher prepayments due to the timing of renewals as well as higher tax payments.

Investor presentation:
https://investors.taboola.com/static-files/e4ea9edd-dbfe-4c0f-bff8-6224daa46a36

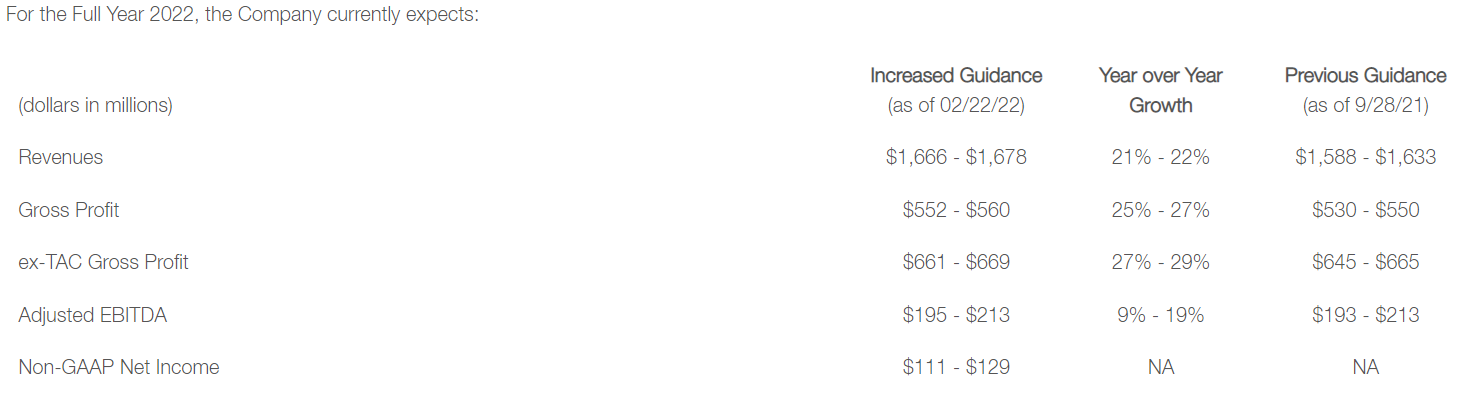
2022 outlook raised

1 Like

@kettunen, can you tell me how these post-EBITDA items are expected to develop from now on? I’m trying to figure out when the company could turn net positive. Apparently, product development is already expensed before EBITDA, and it’s not really capitalized on the balance sheet (and depreciated under D&A).

Currently, last year’s expenses (which include listing costs, etc.) are roughly at the same level as the 2022 EBITDA forecast, so by locking in the expense level, we could reach break-even. However, this probably doesn’t take precedence over maximizing growth in management’s priorities…?

In any case, an interesting company and service, thanks for your monitoring and input to the thread so far!

At least the IPO costs will be gone, and share-based compensation should return closer to previous levels, although it will probably still be higher now that the company is listed. There were some remuneration arrangements for these… I haven’t looked into it in detail.

Without these costs, the result should probably be positive :thinking:

New server and development costs are constant, so capital and depreciations are continuously allocated to them. However, there was a larger item for these last year, I think it was about $30M a larger one-time investment than usual.

The Connexity acquisition involves at least performance-based provisions.

2 Likes

Earnings call transcript to read, need to go through it myself when I have time.
https://seekingalpha.com/article/4489482-taboola-com-ltd-tbla-ceo-adam-singolda-on-q4-2021-results-earnings-call-transcript

1 Like

In connection with the event, the company is announcing it is targeting ex-TAC Gross Profit to exceed $1 billion by 2025 while maintaining 30%+ Adjusted EBITDA margins. The company is also re-affirming Q1 2022 financial guidance ranges that it released on February 22, 2022.