Springvest - Springboard for Growth

Let’s open a separate thread for Springvest.
Trading in Springvest shares will begin on November 30, 2021.
Investor pages: Springvestin sijoittajille

“Why was Springvest founded?
Springvest was founded to meet the financing needs of growth companies and the desire of investors to participate in the stories of growth companies.
Previously, investing in promising, unlisted growth companies was only possible for angel investors and venture capitalists investing large sums.
Since 2012, investing in growth companies has been possible for everyone: through Springvest, one can participate in financing rounds for unlisted growth companies that would otherwise be out of reach for most investors.”

The ten largest shareholders hold a 46.1% stake in the company.
The share was split before listing so that one share yielded 499 new shares.
The listing is a technical listing.

In 2020, Springvest brokered €32 million in growth financing, from which it received €3.2 million in fee income.
Customer examples: Mobidiag, Sensapex, Optitune, Bioretec, NewIcon.

Springvest also invests in companies itself, and the current balance sheet value of the portfolio companies is €14.36 million.
Springvest activates investors by sending an email about an upcoming financing round about a week before the round starts. The customer is not yet revealed at this stage. The customer is announced when the financing round begins. Once the financing round has started, they activate investors via email and, if agreed upon, they call to talk about the customer. Financing rounds include comprehensive brochures about the customer. There are currently about 6,000 investors.

Springvest in numbers

170+ M€

Growth financing raised for target companies (31.10.2021)*

72

Arranged financing rounds (31.10.2021)*

37

Portfolio companies
(31.10.2021)

14.4 M€

Value of portfolio companies on the balance sheet (30.6.2021)

3.3 M€

Revenue 2020

23 %

Operating profit percentage 2020

14.1 M€

Liquid assets on the balance sheet (30.6.2021)

  • During Springvest’s operating history, as of 31.10.2021

Financial targets
The company has set the following medium-term targets:
• Annual growth in investment service income of more than 5% on average
• Operating profit margin of more than 20% on average
• New shares of portfolio companies on the balance sheet annually worth approximately 4 million euros

Company prospectus
https://www.springvest.fi/s/Springvest-Oyj-Yhtioesite-221120214584191-1-compressed.pdf
Marketing brochure
https://www.springvest.fi/s/Springvest_markkinointiesite_final_221121.pdf
The company’s audited information for the 6-month period ending 30.6.2021 and comparative information for the 6-month period ending 30.6.2020
https://www.springvest.fi/s/Yhtion-tilintarkastettu-valitilinpaatos-30620214584181.pdf
10 Likes

Currently, there are 257 shareholders and 5,499,000 shares. The trading volume will probably not be very significant.
In the employee offering before the split, shares cost €1100/share. These were sometimes available for €1200/share years ago.
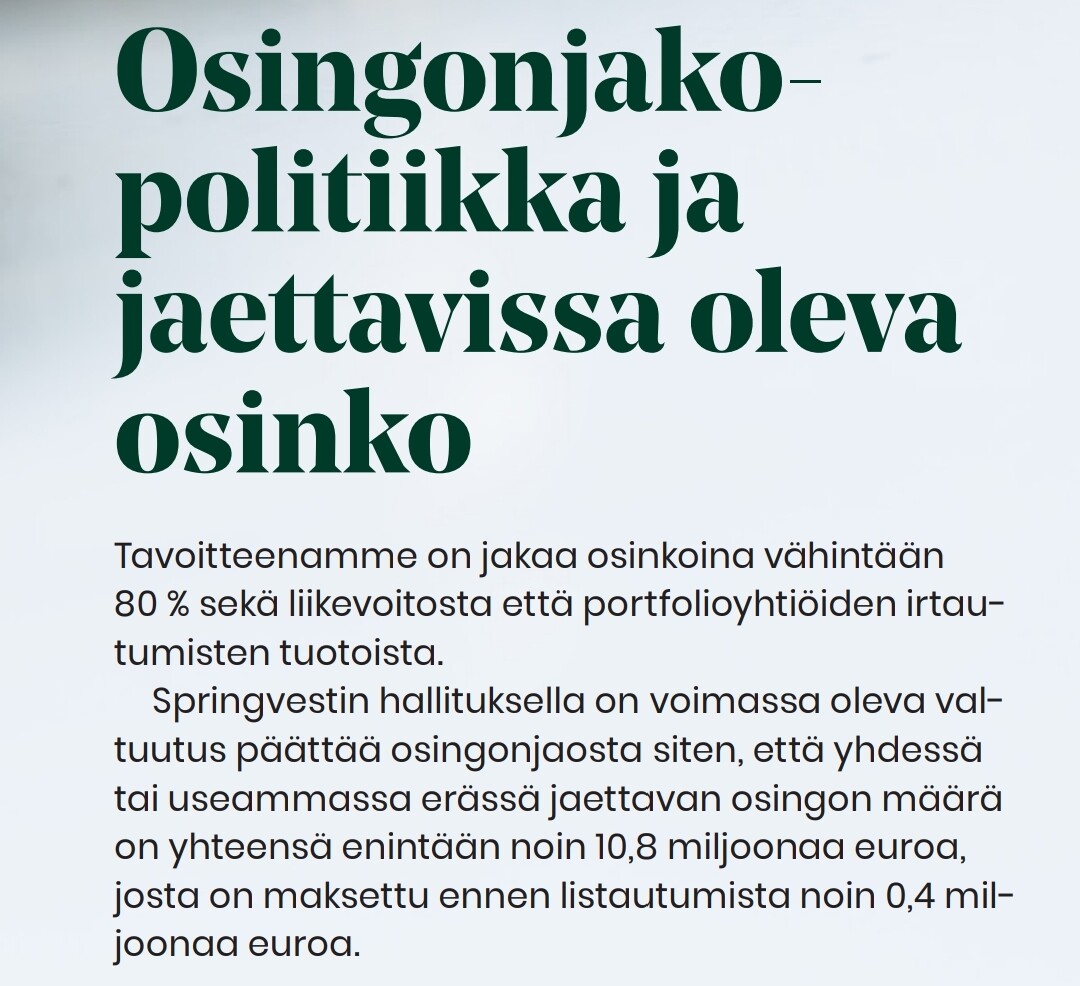
The board has an dividend authorization of approximately two euros per share.

3 Likes

The company doesn’t seem to stir up much emotion on the Forum. Starting trading without a share issue doesn’t attract quick-profit seekers. What’s troubling me these days are negative thoughts like these:

How long will the era of ridiculously loose money enable overinflated share issue financing for unlisted growth companies (Springvest’s bread and butter), with low operating profits, equity inflated this year by an incidental company divestment, and the possibility of distributing possibly illiquid target company shares as dividends (please, no pharma companies). Privanet Oy was known for its eventual demise due to its unlisted activities. On the other hand, a new Wolt might occasionally emerge from the ranks of unlisted companies, and a small diversification into this side of the fence could suit some portfolios.

1 Like

Christmas presents are being handed out.

7 Likes

I wonder why this wasn’t done before the listing, won’t this be more expensive for the old owners now in the form of taxes?

Does anyone with more knowledge on the subject know of any Nordic comparables for Springvest? Or any indicative patterns of listed company valuations for financing activities in general. :slight_smile:

1 Like

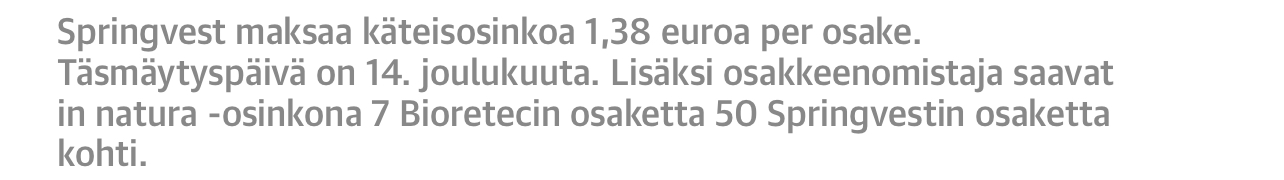
Ohhoh, that was quite a drop. Friday’s quick gains vanished in an instant at the open. Quite an impressive dividend % now available :wink:

Is there an error there, as the ex-dividend date is mentioned as 13.12 and the record date as 14.12? Aren’t they usually the other way around? The smart ones had time to buy and sell and grab the dividend in between.

It is worth reading, among other places, here.

https://www.inderes.fi/fi/inderes-sijoituskoulu-osingot

There’s no mistake. The record date is the day one needs to be on Euroclear’s (Euroclear) shareholder register, which means one must have been an owner two days prior. In this case, you need to own the share at the end of December 10th to be on the shareholder register on December 14th. Consequently, the dividend ex-date is December 13th, because if you buy then, you will only be on the shareholder register on December 15th and will not receive the dividend.

It’s another matter how sensible it is for the market that the stock rises by the amount of the dividend upon dividend announcement, and now that the company’s cash reserves are significantly lower, it returns to the same price as before the dividend announcement. :sweat_smile:

1 Like

Dividends paid 2-4 times a year reduce the need/opportunities to buy quick wins in the form of dividends. I’ll have to keep an eye on this S, it could be an interesting company if the development meets expectations, but I didn’t get into this dividend “craze.”

Hi! We’ve just started tracking Springvest, and the comprehensive report initiating the coverage can be found here :point_down: Springvest is an investment service company that arranges funding rounds for unlisted growth companies.

Springvest is a very exceptional company in the sense that only a fraction of its value creation is reflected in its income statement. The ownership stakes in unlisted growth companies received as fees from funding rounds are directly reflected as growth in the balance sheet. In terms of value creation, it shares similar characteristics with investing in earlier-stage growth companies, meaning it is to some extent a game of probabilities: value creation typically depends on a small number of very successful investments. This probability can, of course, be influenced by selecting good investment targets, as Springvest aims to do by choosing companies with, in its estimation, the best potential for funding.

The valuation of Springvest requires assumptions (e.g., what is the fair value of future share-based compensation from companies yet to be funded and unknown?), so the margins of error are wide. This applies to all analyses and opinions presented by others, but I recommend reading the analysis more closely and considering whether you agree with the arguments and assumptions we have used :slight_smile: I’m happy to answer any questions that arise concerning the analysis or the company :+1:

Tomorrow, there will also be a video where we will go through the company in more detail with @Kaisa_Vanha-Perttula :tv:

16 Likes

Here’s a new video where we go through Springvest as an investment target with @Antti_Luiro. :blush:

-Topics-
00:00 Start
00:17 Springvest in a nutshell
01:13 Selection criteria and process for target companies
02:30 Development and consolidation of the crowdfunding market
05:33 Market competition situation
07:03 Growth outlook
10:15 Risks
12:12 Business model and revenue streams
14:49 Value creation and share valuation level

4 Likes

Here’s an updated report from last night and a comment on the report’s front page from this morning :point_down:

No significant changes in forecasts or the company’s situation; the share price had fallen to the target price level, and a review of the recommendation was in order :+1:

2 Likes

Springvest published an investor survey :point_down: interesting data on the company’s customer base and investors in unlisted vs. listed companies :thinking:

One highlight: Among the responding Springvest investors, the war in Ukraine has

  • increased investment interest for approx. 10%,
  • decreased it for approx. 45%, and
  • had no effect on 45% of respondents.

It is good to note, however, that most of these effects are mild. The data nevertheless supports our view that the current year’s environment is more challenging than previous years in terms of financing availability. It is also interesting that among those investing in listed companies, the effects have been neutral overall, meaning investment interest has grown and declined in similar proportions among respondents.

https://www.springvest.fi/ajankohtaista/sijoittajatutkimus-2022-uudet-kasvusijoittajat-kaipaavat-helppoutta-sijoittamiseen-ja-kokeneemmat-odottavat-uusia-kasvuyhtiode-menestystarinoita

6 Likes

Small update to the target price due to dividend detachment :point_down:

2 Likes

It would be an interesting thought experiment to consider the current fair value of Springvest’s portfolio companies and completed rounds. Given that the 24% IRR is calculated based on exits (16/37), the Mobidiag acquisition will probably provide a nice boost.

In the “Health technology and medicine” sector (October 31, 2021), there’s a 41% allocation in the portfolio, and in technology, it was 19% last year. These are exciting times when considering the current state of the debt market and the runway for biotech, not to mention the current market valuation compared to Springvest’s post-money valuation. Of course, as long as retail investors continue to believe and rounds fill up, we won’t be in a case-Invesdor situation, nor will our own VVK (Venture Capital Fund) appear on the list :thinking:

Edit: Kudos for the good and comprehensive analysis on the video from 4/2022, which I only just watched.

With Springvest, I’m slightly concerned about the growth strategy and the future of these option-based bonuses (2022-2024). One might imagine that the company would want to expand into, for example, interest-bearing investments like Invesdor and numerous other private market growth investors. The question is, will a Vauraus Oyj-like dynamic emerge due to the background individuals’ connection to Vauraus, making them unwilling to compete? I don’t know, but at least I ask myself why, with the market trend and potential IRR returns (biotech allocation) weakening, they wouldn’t want to enter the private debt market due to its short duration, which would allow capital to circulate faster.

Regarding top investments, with the option bonus model, will the sharpest edge be left out due to this retail investor mentality, and will Springvest negotiate higher valuations than VC funds, which might now come back to haunt them in 2022-2023 as macro factors reflect on private valuations? I don’t know.

But good analysis of the company, and I’ll be following with interest :+1:

Edit 2:

I don’t remember if this was discussed in the analysis, but in my opinion, Springvest differs dramatically in the VC/PE field in that it’s a sales organization in my eyes, and the substance/experience years of the personnel in private equity might not be at the same level as in many other companies in the sector. Instead, Privanet / Vauraus are perhaps closer as organizations than, for example, Tesi, Verdane, or Evli, which in turn increases this already significant risk in finding top companies and achieving risk-adjusted returns for investors in this market.

4 Likes

@Antti_Luiro, do you have any thoughts on expanding into, for example, interest-bearing investments, a large allocation to biotech/technology, or valuation of rounds and potential challenges with follow-on investments in the current market? The HR side and comparison of organizations are mainly my own thoughts on the competitive landscape :slight_smile:

There doesn’t seem to be much “action” in the thread, but at least I’m interested in following how the company’s business side progresses in the current market. I should probably subscribe to Inderes Premium :thinking:

Edit: The longer I examine the company, the more questions arise regarding its investment philosophy, earnings logic, and the actual quality of its portfolio, so it’s better to follow this one from the sidelines.

2 Likes

Hi @Makromies-1987! I consider simple and consistent round structures to be one of Springvest’s advantages for private investors. If debt-based models were introduced alongside the current share issues, the company’s offering would become more complex :thinking: For this reason, I believe that rounds will very likely continue to be share issues in the future.

Springvest’s emphasis in company selections is on scalable businesses, and from this perspective, the high proportion of biotech/technology companies is also natural. Currently, the financing situation for companies with negative cash flow is, to my understanding, difficult even outside the stock exchange. From this perspective, Springvest could have a very good leverage to negotiate valuations downwards for the rounds it organizes.

In the short term, I am most concerned about the prerequisites for exit events and the readiness of Springvest’s investor clients to participate in new funding rounds. The current economic environment (rising interest rates + electricity prices + inflation), however, cuts into the savings portion of many people’s incomes. The company’s clients may also have had more extra cash than usual from the exit events of 2020-2021 (especially Mobidiag), which they may have invested in new rounds. If exits now remain low as per our expectations, Springvest’s investor clients’ investments in previous rounds are tied up in illiquid unlisted companies, and less liquid capital would be available. This, combined with a lower savings accumulation, seems to me like a challenging equation from the perspective of the capital available for Springvest’s organized funding rounds.

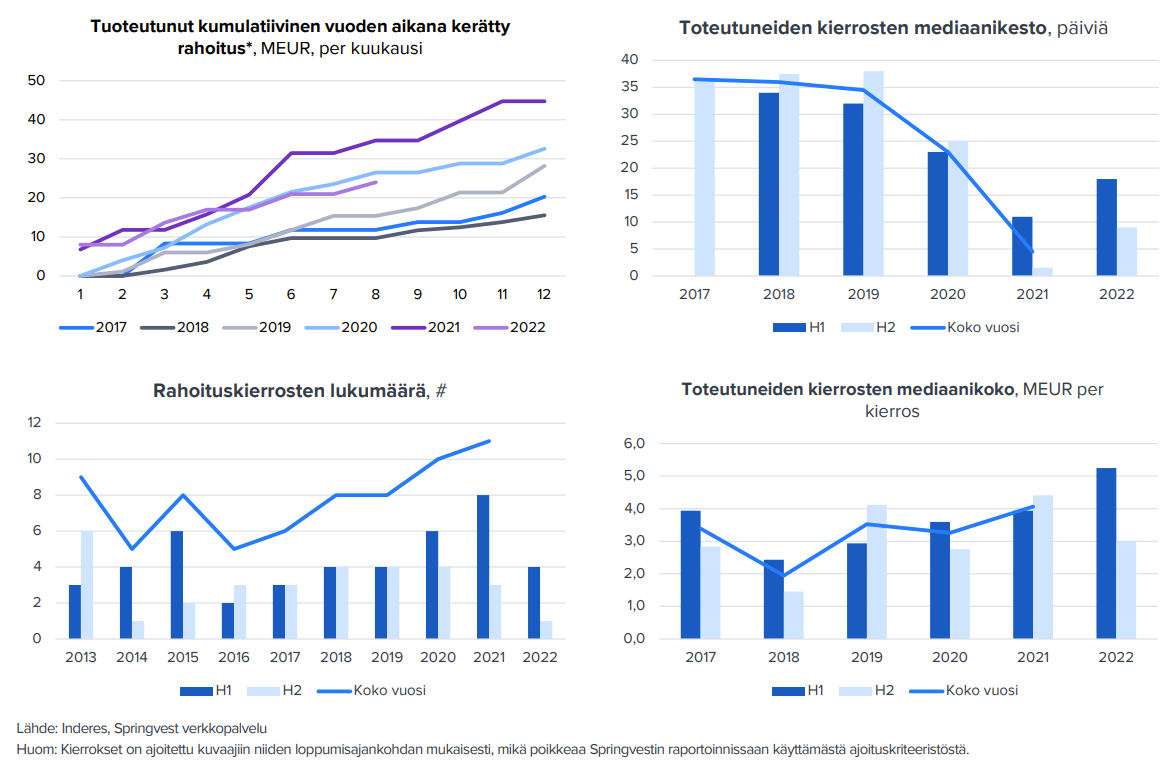
Regarding the monitoring of the company’s business: Portfolio exit events are somewhat of a black box, meaning they are largely guesswork based on general market sentiment and company communications. Funding rounds, on the other hand, can be monitored in real-time on the company’s service at https://app.springvest.fi/, and through this, there is excellent transparency regarding the amount of funding raised :+1: We include charts of these in our reports as rounds are completed. Here’s the situation as of September 7th:

3 Likes

Greetings Antti,

Thank you for your quick and excellent response :slight_smile:

I articulated my point a bit unclearly, but I was thinking about the same things: when there’s a strong allocation in biotech/technology companies where negative cash flow can very well be a reality, and with VPO & OPO offerings drying up and investors’ (retail) available funds decreasing, the combination is not the best possible. Does investor dilution with potential follow-up rounds eat away at motivation?

Of course, there are two sides to the coin, and Springvest might indeed allow participation at favorable valuations due to market conditions, although these might already involve larger institutions providing capital through capital loans or similar means. For example, ArcDial (a portfolio company) seems to have a funding round ongoing on Invesdor, which apparently hasn’t gained much popularity. An interesting winter and near future lie ahead as exit events slow down.

However, your reporting is working well, and we’ll keep following how the story unfolds :+1:

3 Likes