Päädyin tutustumaan Tritiumiin (yhdistyy tosiaan DCRN:n kanssa) kun @naata meni yhtiöstä mainitsemaan osta/myynti-ketjussa. Piti lopettaa näiden lottoaminen ja näihin tutustuminen, mutta…
Yhtiöhän keskittyy nopean latauksen ev-latausjärjestelmiin ja on kotoisin Australiasta. Yhtiöhän julkaisi q3 tietoja lokakuussa, mistä ilmenee kysynnän kiihtyneen q3 aikana merkittävästi jopa yhtiön itsensä antamista arvioista:
For the three months ended September 30, 2021, Tritium booked record orders of approximately $55 million (31% higher than the September 30, 2021 forecast in the Analyst Day update released on September 21). The Company’s backlog continued to grow throughout the three months ended September 30, 2021, ending at a record of approximately $78 million (18% higher than the September 30, 2021 forecast in the Analyst Day update), or an increase of 333% over the backlog at December 31, 2020.
Total Tritium DC fast chargers sold globally now stand in excess of 5,250, compared to 4,400 when Tritium announced its proposed business combination with DCRN - an increase of 19% in only 18 weeks.
Production in the three months ended September 30, 2021 was a record of approximately $22 million, representing a 64% increase over the three months ended June 30, 2021 and a 140% increase over the three months ended March 31, 2021.
Total backlog of approximately $78 million as of September 30, 2021 represents the largest backlog ever recorded by Tritium, an increase of 86% over the June 30, 2021 backlog of $42 million and an increase of 189% over the March 31, 2021 backlog of $27 million.
Lähde;
Yksi mielipide arvostuksesta:
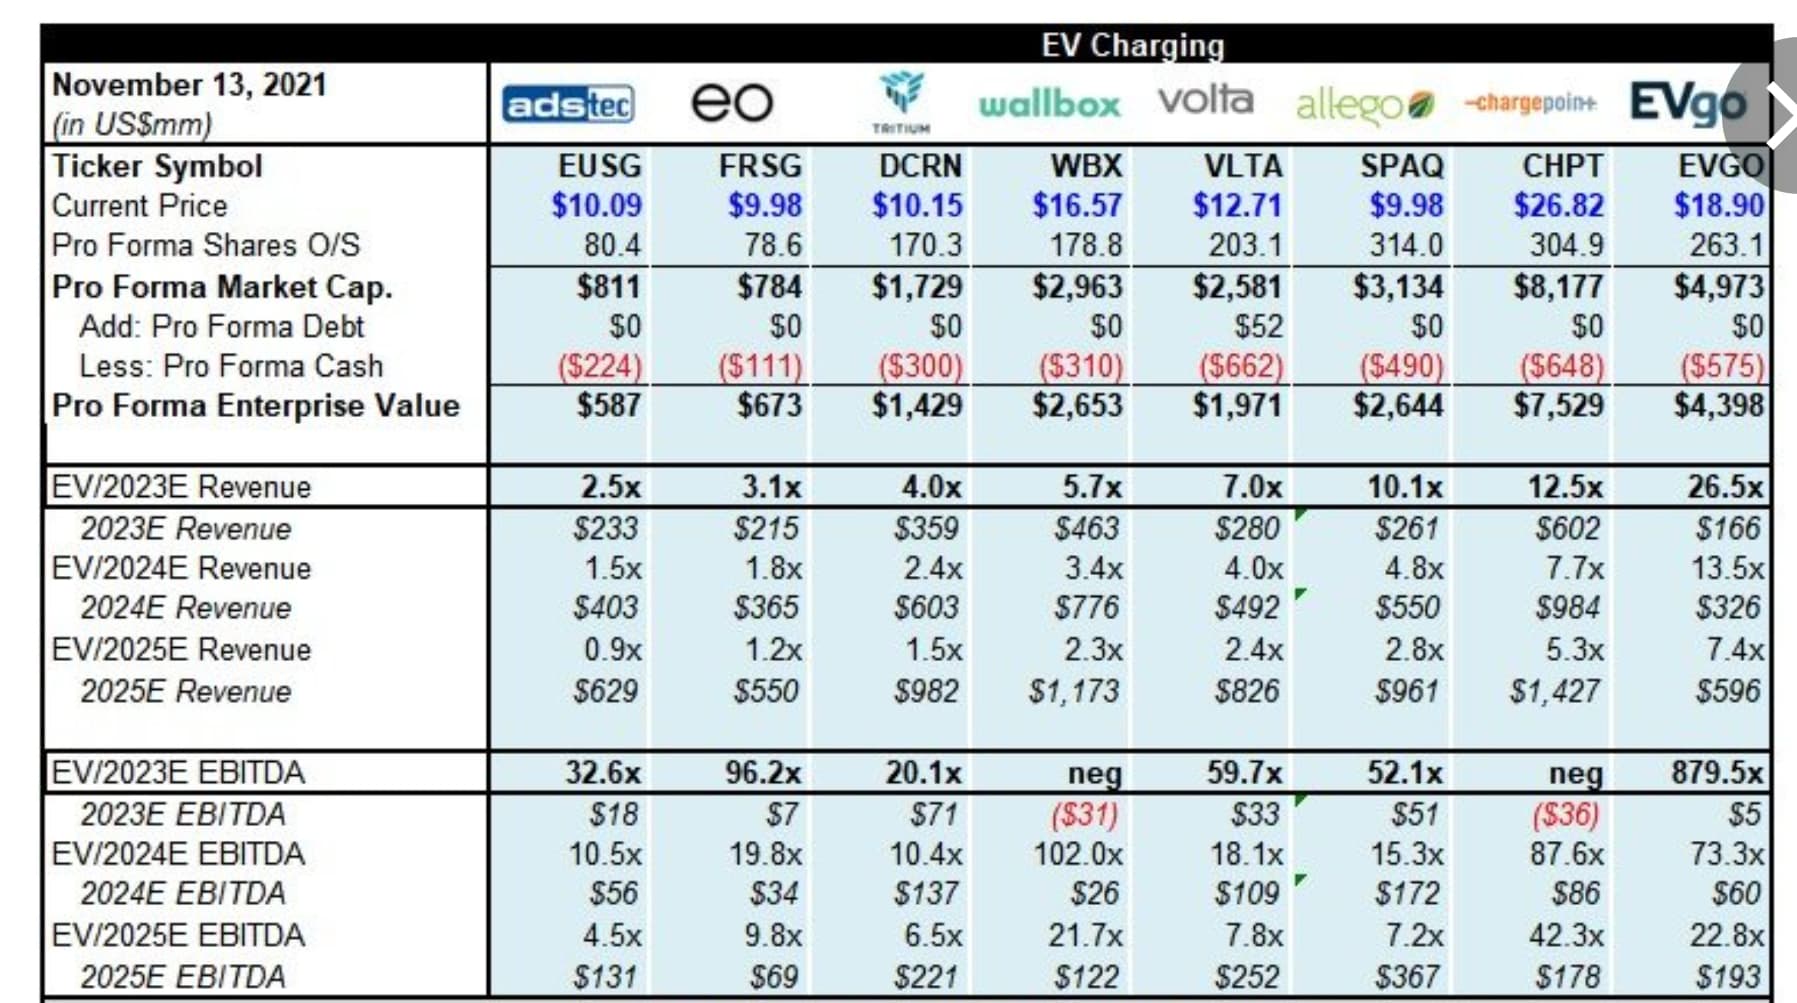
With an implied market cap of $1.7 billion and estimated revenues of $84 million for 2021, Tritium’s simple valuation ratio comes in at around 20. To put that number in perspective, we won’t touch any stock with a ratio of 40 or higher. We can also compare this to another publicly traded EV charging stock, ChargePoint (CHPT), which is extremely overpriced right now. Market cap / Q2-2021 annualized revenues
$7,000 million / $162 million = 43
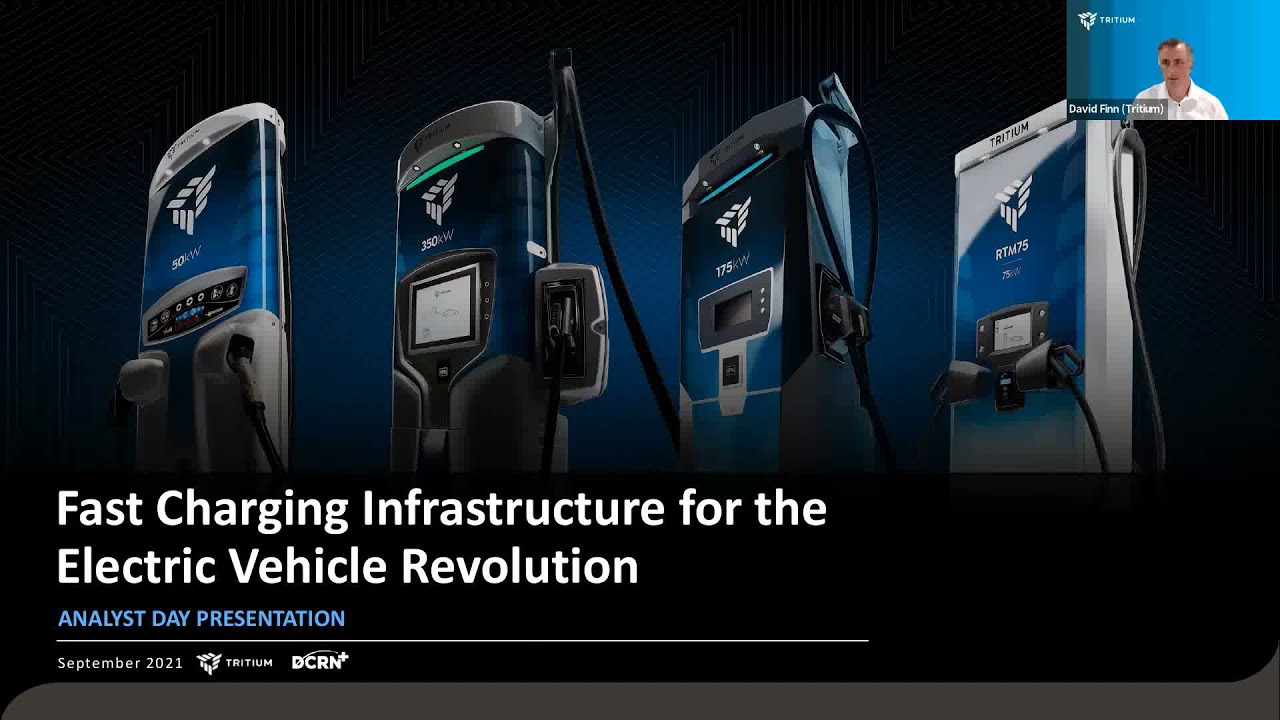
Ja tuolta yhtiön oma presentaatio toukokuulta, missä mm. yhtiön omaa vertailua verrokkien arvostukseen:
Lopuksi: Tutkittuani yhtiötä sanoisin, etten näe syytä sille, miksi hype ei voisi tähän tarttua, kunhan tästä lähempänä yhdistymistä (jossain oli joulu-tammikuu) ruvetaan kirjoittelemaan. Yhtiön tunnusluvut myös alhaisemmat verrokkeihin nähden ja odottavat voitollista tulosta 2023. Viimeaikainen uutisvirta ollut lisäksi kiihtyvän positiivista. Löytääkö kukaan mitään negatiivista tähän liittyen ja mielellään ennen ma pörssejä ja omaa ostotoimeksiannon tekemistä? 
 Piti itsekin ottaa pitkästä aikaa SPAC positio. Ei ole ollutkaan näitä sitten kesän. Diili on ilmoitettu jo puoli vuotta sitten, eli tässä pitäisi olla aivan loppusuoralla yhdistymisen suhteen? Hinta aivan NAV:in tuntumassa ja Stocktwitsissäkään ei näy kuin 1200 seuraajaa. Tässä EV mania markkinassa lentää kyllä aivan tutkan alla.




 .