Could I get a safe parking spot for my money in these bad times? Put in 10€ and let it sit there. Speculation or finding a target would yield a good return. In the worst case, a 0% return, which practically corresponds to a basic bank account interest rate.
1 Like
VAC works a bit differently; there’s actually a 10% risk to the capital—at least at the IPO price—if a target isn’t found within 36 months. A quote from the article:
After listing, the SPAC has 36 months to find a company to acquire. If no company is found, the remaining funds, at least 90 percent, are returned to investors.
Potentially, it could start trading below the IPO, and the risk premium would decrease afterward. These are new to the market, so the movements could be unexpected.
2 Likes
It’s important to remember that the risk doesn’t come from the VAC/SPAC premium above NAV, but from the terms and conditions of the merger, and which company is being merged. With SPACs, we’ve seen some truly comical merger deals where valuation multiples have been stretched to the heavens right from the start…
2 Likes
Yes, I was mainly referring to the bank account comparison, in this case, the risk being 10% of the IPO price. US SPACs are currently widely available below NAV, so the bank account comparison works better there.
However, in connection with a merger, it is possible to redeem the share at the NAV price, so the risk is limited in that respect, regardless of the target company.
One more affordably valued option, in my opinion, is Taboola / $IACA, which I have also referred to here before. I opened a thread for Taboola, so discussions related to it will continue there in the future.
3 Likes
3 Likes
GHVI (+15%) today’s SPAC boost.
4 Likes
Things are slowly starting to liven up with new announcements. For example, Legato Merger $LEGO was “in talks” yesterday with Canadian steel company Algoma Steel. Warrants were up +32% and even went as high as $0.70.
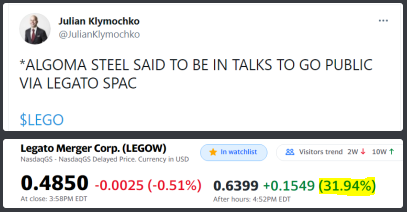
In addition, many de-SPACs are in an uptrend, and several merger votes are coming in June. Likely, after the SEC (Securities and Exchange Commission) chaos, new DA (Definitive Agreement) announcements will also follow.
The crypto dip probably also has some effect. SPAC investors shifted to cryptocurrencies during the spring, so retail money, in addition to institutional money, was pulled from the market with the observed consequences. There are signs of rotation in the other direction, and sentiment is improving. I’ve already started accumulating small additions to warrants, mainly at the cheaper end, where a potentially higher ROI (Return On Investment) is available, for example, $LEGO as an example.
Edit:
A suitably updated calendar; at least 2-3 of my own targets are coming in June or early July in addition to these.
https://twitter.com/DJohnson_CPA/status/1396135988087427072?s=19
12 Likes
An interesting video, just over an hour long, that goes through ARK Invest’s, Draftkings, and Skillz deals with Eagle Equity Partners, the operating principles of SPACs, views on the future, and possible needs for change, e.g., from the SEC’s perspective.
Eagle’s SPACs have been of higher quality, and based on these views, my confidence in their operating model increased.
The beginning is a comprehensive explanation of the SPAC process, but the more interesting part is at the end.
Content:
Key Points From This Episode:
● Introducing Harry and Eli and how they got into doing SPACs.
● A brief definition of a SPAC and how presents a different way of going public than an IPO.
● Initial SPACs our guests worked on and why they chose the companies they did.
● Advantages of using SPACs instead of regular way IPOs.
● Why the observation that 70% of IPOs are SPACs now needs to be reframed.
● A deep dive into the process of how SPACs work: IPOs via SPAC, the purpose of PIPE, etc.
● How there is so much scarcity value attached to PIPEs and why this is causing a bubble.
● Exploring the idea that ‘SPAC sponsors are gig economy IPO bankers for investment banks’.
● Many SPAC sponsors raise too many deals unfortunately making things into an AUM game.
● Why Harry and Eli are different from other players in the game by working harder for longer on each SPAC.
● What goes into the extra work Harry and Eli put into SPACs regarding getting to know target companies.
● Why the projections made by SPACs are often less trustworthy than those by more mature publicly traded companies.
● Difficulties drawing the line of when is it too early to take a company public using a SPAC.
● The problem of too much gambling or speculation in the stock market right now.
● Another issue of people not voting to get deals done because of retail access to options.
● Final perspectives on why the SPAC phenomenon feels speculative and retail-heavy.
● Harry comments on the Churchill leak and why leaks are a problem for SPACs but not regular IPOs.
● Problems about SPACs that the SEC should address; leaks and long-term projections.
● Whether the amount of SPACs will continue to grow or hit a wall instead.
● The problem of SPAC funds using leverage to increase their funds.
5 Likes
Now DA $LEGO came in.
https://twitter.com/DJohnson_CPA/status/1397001995651792899?s=19
5 Likes
PIPE financings are becoming challenging to achieve, and valuations and more realistic outlooks will be more important in the future. Current valuations may be re-evaluated, as was discussed here previously.
Alternatively, new agreements may only use the SPAC fund share without additional financing. Potentially, smaller deals are coming, but with better valuations. Or, several SPACs will be dissolved within a couple of years if the sentiment does not change.
3 Likes
It tells you how greedy the valuations were when those SPAC deals were put together… the market is overheating so suddenly all sorts of things are being tried. Then when suddenly not everything is acceptable anymore and someone even pulls out Excel and does some calculations before getting rid of their money, then…
4 Likes
The same problem with growth companies also applies to already listed and traditional IPOs. Valuations went out of control and came back down across the board. Good targets can still be found - or rather, precisely now after the decline - if one is willing to dig and even at reasonable or affordable valuations.
The risk of holding through a merger now is redemption if the stock trades below NAV. In the worst case, it dissolves if not enough target capital is raised. Conversely, companies that have gone through a merger have also started to rise well recently, e.g., $BRPA or $OWL.
CNBC has just published its 50 Disruptors, which are still private. These lists have previously featured several targets for IPOs or SPACs.
https://www.cnbc.com/2021/05/25/these-are-the-2021-cnbc-disruptor-50-companies.html
Edit, let’s continue with a quick comment here
The movements from DA announcements are starting to look good. A gradual change in sentiment 
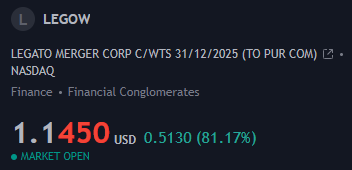
LEGOW warrants +80% with good volume. My own shares went out at $0.68 with the rumors 
6 Likes
2 Likes
1 Like
APXT / AvePoint just announced the merger vote date for June 30th! 
This has been long awaited…
S-4 filing:
https://sec.report/Document/0001193125-21-175949/d270676ds4a.htm
a special meeting of stockholders (the “special meeting”) of Apex Technology Acquisition Corporation, a Delaware corporation (“Apex,” “we,” “our” or “us”), will be held on June 30, 2021, at 10:00 a.m., Eastern time
6 Likes
https://twitter.com/spacanpanman/status/1398323642958848002?s=20
Russell 2000 additions for 6/25:
$GCMG $GMTX $MPLN $TLMD $FREE $OUST $ETWO $UTZ $HIMS $VIEW $AEVA $EOSE $STEM $BFLY $GOEV $PCT $MILE $SKIN $PRCH $DM $GNOG $APPH $ASTS $SFT $VLDR $RSI $HYLN $MP $XL $TTCF $RMO $RIDE $LAZR $DNMR $OPEN $LOTZ $CHPT $NKLA $QS $FSR $DKNG $PLBY $CLOV
Names mentioned here that have been featured:
Ouster, UTZ, Aeva, Canoo, Porch, AppHarvest, Velodyne Lidar, Hyliion, Tattooed Chef, Luminar, Opendoor, Nikola, Fisker, Draftkings, Playboy
4 Likes
Stockholm-listed PE firm $VNV announced that their largest holding, Babylon Health, is planning to go public via a SPAC. I bought VNV for my portfolio during the SPAC frenzy precisely for this scenario. We’ll see how it develops… 
4 Likes
FTOC / Payoneer merger date 23.6.
5 Likes
SPNV Supernova and OfferPad released their Q1 results.
Offerpad compares well to Opendoor, which is currently trading in the $15-16 range. However, Offerpad’s valuation is lower, although it is still in the red and smaller than $OPEN. The potential is good, and the merger is nearing completion at the beginning of Q3.
Operations are soon turning profitable, with new state openings made and more to come. Adjusted EBITDA has been positive for a couple of quarters now. The bottom line also shows only a small deficit.
Previous post with more information. After that post, my mind has changed regarding this, and I will probably even add more at some point if the SPAC sentiment moves in a favorable direction.
Offerpad Reports First Quarter 2021 Results
First Quarter 2021 Highlights - as compared to the prior year first quarter (unless otherwise noted)
- Revenue for the quarter was $284.0 million and increased 27.2% from $223.2 million in the fourth quarter 2020
- Loss per share improved to ($0.03) from ($1.49)
- Net loss improved $11.2 million to nearly break even at ($0.2) million
- Adjusted EBITDA increased $8.3 million to $3.0 million from ($5.2) million
- Gross profit increased $8.6 million to $33.5 million from $24.9 million
- Gross profit per home sold increased 101% to $32,900 from $16,400
- Gross profit margin improved 500 bps to 11.8% from 6.8%
- Contribution profit after interest per home sold increased 349% to $23,100 from $5,100
Source: SEC filing Redirecting...
2 Likes
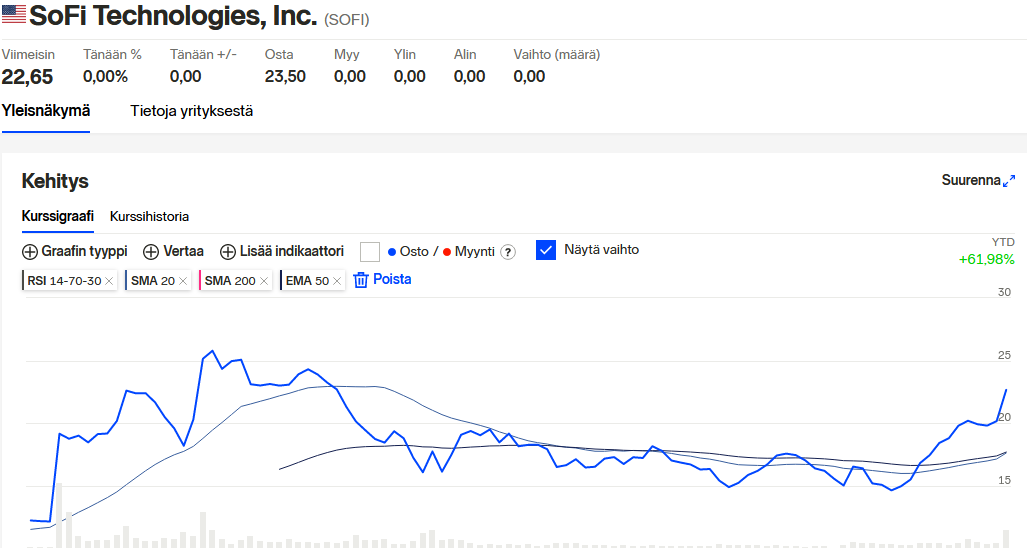
We’re starting to see more SPACs (Special Purpose Acquisition Companies) that don’t drop drastically after a merger. The latest is SoFi, where the ticker changed yesterday and the price keeps climbing:
DA’s (Definitive Agreements) have also started to rise again on the SPAC side:
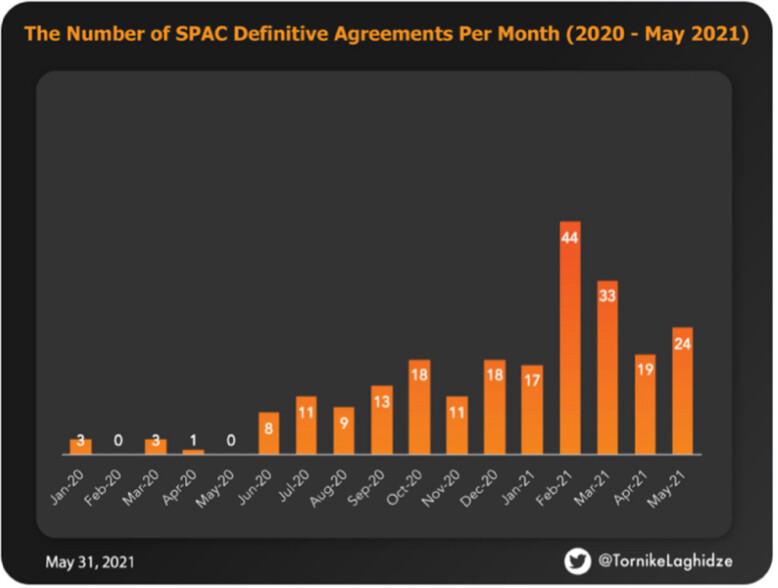
Could the sentiment be turning positive again for SPACs?
6 Likes